
Yokohama Rubber Company (TSE:5101) Could Be 66% Below Fair Value At ¥6,825
Yokohama Rubber Company (TSE:5101) drew fresh attention after its recent trading session, with the share price closing at ¥6,825. This has prompted investors to reassess performance over the past month and year.
Recent moves suggest momentum has cooled in the short term, with the 30 day share price return down 9.75% and the 90 day share price return down 13.96%. However, Yokohama Rubber Company's 1 year total shareholder return of 22.55% and 5 year total shareholder return of 293.22% still point to strong long term compounding.
Compare Yokohama Rubber Company’s recent pullback with other resilient auto and industrial plays by scanning our hand picked list of list of solid balance sheet and fundamentals (21 results)
The pullback to ¥6,825 leaves Yokohama Rubber Company trading well below both analyst targets and one intrinsic value estimate. The real task now is to work out where fair value sits inside that spread.
Price-to-Earnings of 7.6x: Is it justified for Yokohama Rubber Company?
On a simple earnings lens, Yokohama Rubber Company screens as inexpensive, with a P/E of 7.6x pointing to an undervalued share price at ¥6,825 compared with both its peers and one internal fair value check.
The P/E ratio compares what you pay per share with the profit attributable to each share. For a mature industrial group like Yokohama Rubber Company, which operates in tires and diversified rubber products, this metric is a common shorthand for how much investors are willing to pay for current earnings power.
Here, the market is assigning a 7.6x multiple at the same time one internal estimate suggests the stock is trading at 65.8% below an assessed fair value, and the fair P/E implied by regression analysis is 14.1x. That gap is large, and it clearly signals that the current price embeds lower expectations than what that fair ratio would point to if sentiment shifted toward the modelled level.
Relative to the JP Auto Components group, where the average P/E sits at 9.8x and peer comparisons show about 10.6x, Yokohama Rubber Company trades at a clear discount. The market is pricing its earnings materially lower than both the sector average and the modelled fair P/E of 14.1x, which is a level the valuation framework suggests pricing could gravitate toward if conditions and perceptions align with that benchmark.
Explore the SWS fair ratio for Yokohama Rubber Company.
Result: Price-to-Earnings of 7.6x (UNDERVALUED)
Still, the Yokohama Rubber Company story can shift quickly if demand for tires and industrial products weakens or if input costs squeeze profitability.
Find out about the key risks to this Yokohama Rubber Company narrative.
Another View on Yokohama Rubber Company’s Value
The P/E story points one way, but the SWS DCF model is even more aggressive. It pegs Yokohama Rubber Company’s future cash flow value at ¥19,948.89 per share versus the current ¥6,825, which suggests a very large gap that investors need to judge for themselves. Could that spread be justified by future cash flow risk?
Look into how the SWS DCF model arrives at its fair value.
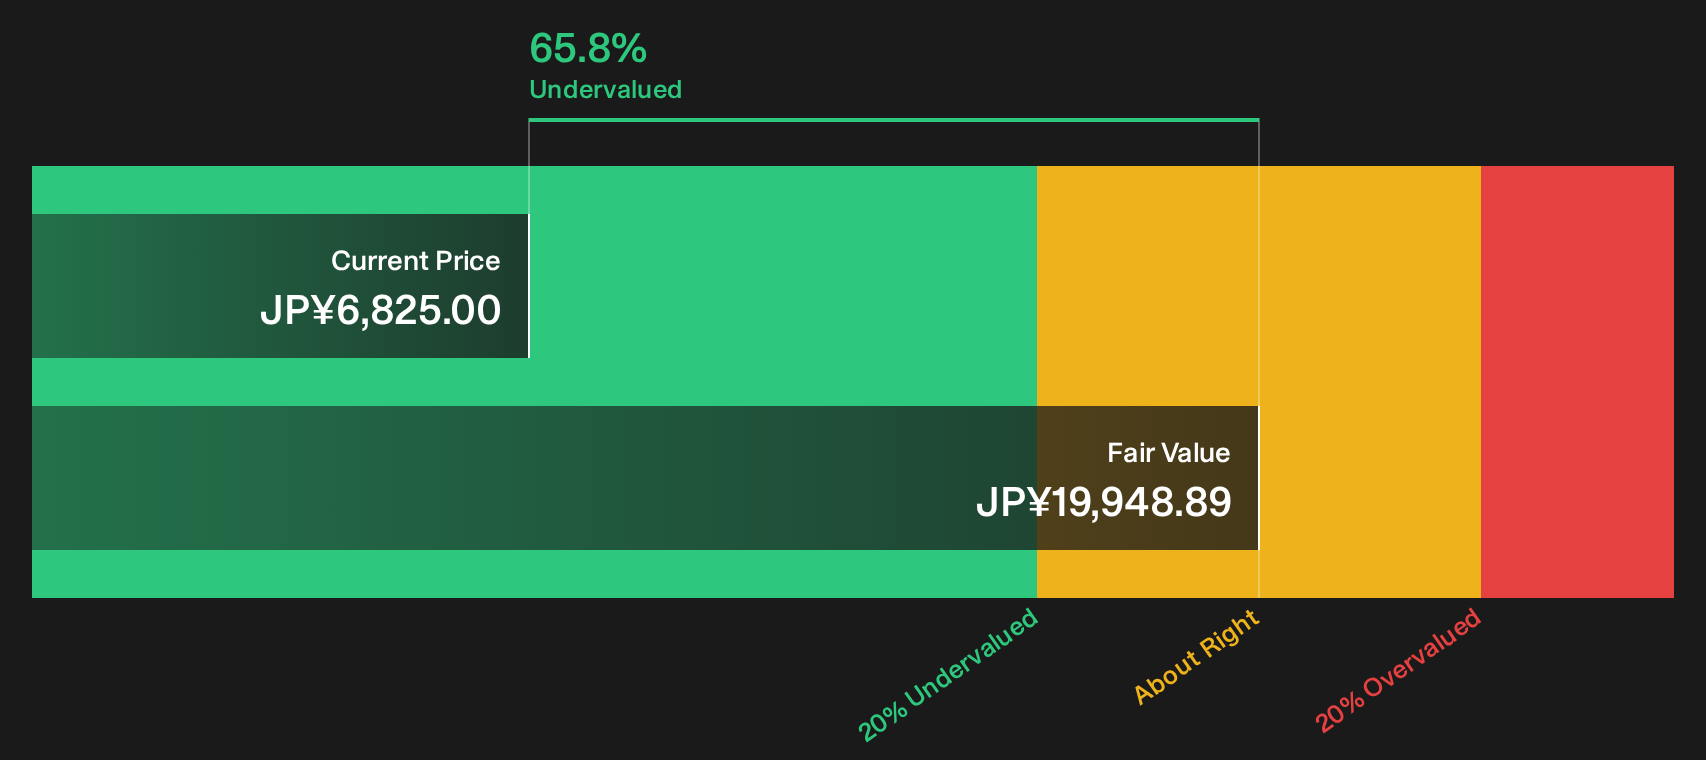
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Yokohama Rubber Company for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or a clear setup around Yokohama Rubber Company, your next step is to move fast enough to test the numbers yourself and weigh both sides of the story. To help frame that view, start with these 5 key rewards and 2 important warning signs
Looking for more investment ideas beyond Yokohama Rubber Company?
If Yokohama Rubber Company has sharpened your focus on valuation, do not stop here. Broaden your watchlist with fresh ideas that fit clear financial filters.
- Target potential mispricings by scanning companies filtered for 17 high quality undervalued stocks that may offer stronger fundamentals than their current share prices suggest.
- Prioritise resilience first and search for businesses screened as 21 resilient stocks with low risk scores so you can focus on steadier balance sheets and clearer risk profiles.
- Get ahead of the crowd by reviewing 75 high quality undiscovered gems before they attract wider attention and tighter pricing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com