
CleanSpark (CLSK) Signs 20 Year Lease, Is A 39% Discount Still Real?
CleanSpark (CLSK) just locked in a 20-year, US$6.6b triple-net lease for its Sandersville, Georgia, site, tying that data center footprint to an anticipated US$330m in annual revenue.
That lease news lands after a busy run for CleanSpark, which has been lining up long dated funding through US$2.2b in senior secured notes and reporting fresh production figures. The stock now trades at US$14.47, with short term share price momentum building, while longer term total shareholder returns are still defined by a very large three year gain and a more modest one year outcome.
Spot 88 AI infrastructure stocks that, like CleanSpark, are tying long-dated leases and heavy capex to the rising demand for AI, colocation, and high performance computing.CleanSpark shares have run hard on the back of the Sandersville lease and fresh funding, yet the business still reports a loss and mixed recent returns. How much of this latest jump reflects fundamentals versus sentiment?
Most Popular Narrative: 39% Undervalued
CleanSpark last closed at $14.47, while the most followed valuation storyline pegs fair value at $23.81. This sizeable gap puts the new Sandersville lease and long-dated contracts under a brighter spotlight.
CleanSpark's fully self-operated, scalable, and power-efficient infrastructure enables it to mine Bitcoin at a significantly lower cost than the market price. Further capacity expansion (an additional 10 exahash and over 200 megawatts of contracted power ready for rapid deployment) is described as being poised to drive sustained increases in Bitcoin production, improving revenue and supporting higher net margins. The company's strategic focus on sourcing flexible, low-cost, and increasingly renewable energy, combined with operating in supportive states, is described as reducing exposure to volatile energy markets and supporting stable or expanding gross margins, fostering long-term earnings resilience in an industry prone to input cost shocks.
See why 129 investors see CleanSpark as 39% undervalued.
Result: Fair Value of $23.81 (UNDERVALUED)
Still, the CleanSpark story can break if Bitcoin economics weaken, or if heavy capex and frequent fleet upgrades drag on already loss making results.
Find out about the key risks to this CleanSpark narrative.
Another View: CleanSpark Through a Sales Multiple Lens
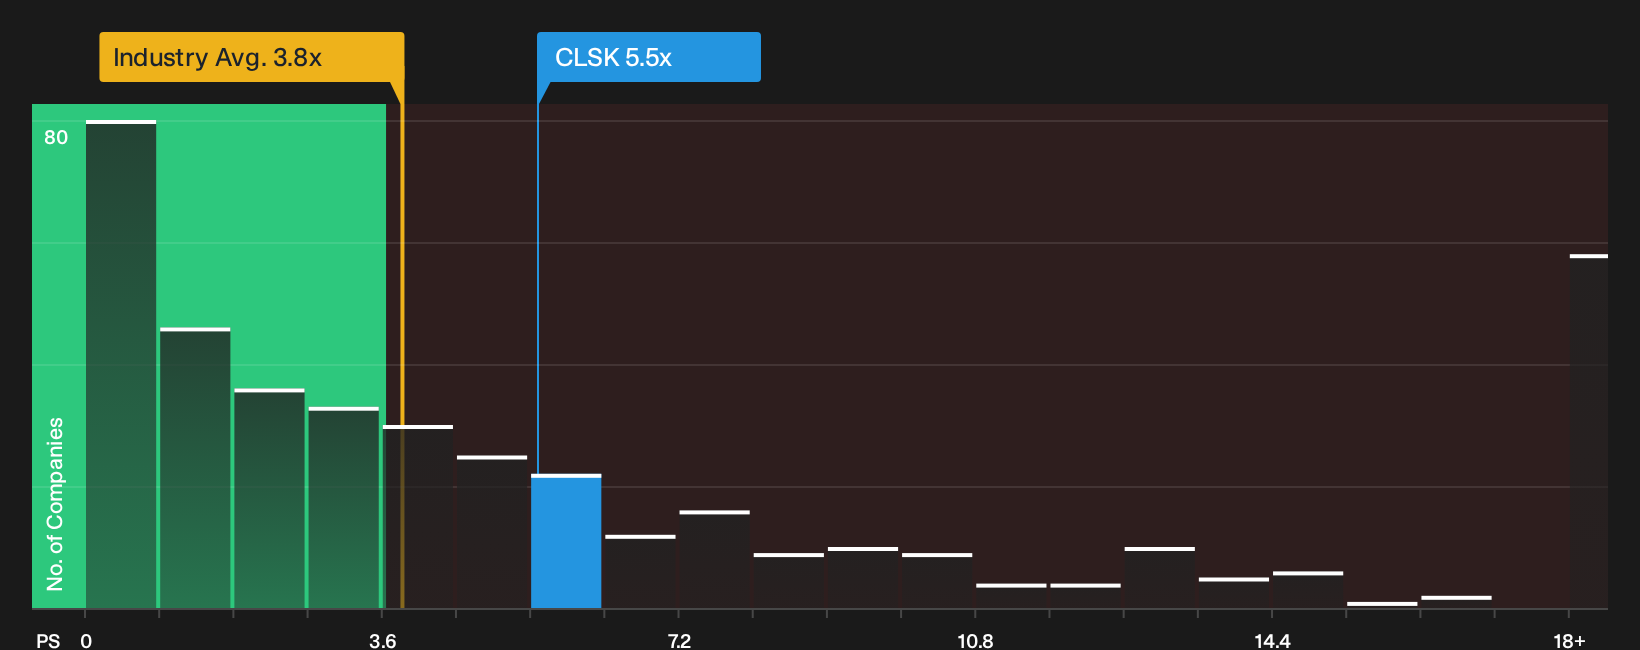
Analysts see CleanSpark as 39% undervalued on their fair value narrative, yet the market is already charging a P/S of 5.5x. That is richer than the US Software industry at 3.8x and above a fair ratio of 2.8x, even if it screens cheaper than peers at 6.7x.
This gap suggests investors are already paying up for the Sandersville lease story and potential future AI infrastructure. The key question is whether that premium leaves more upside on the table or instead increases the risk of a painful reset if expectations soften.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals across CleanSpark's valuation and fundamentals make this a judgment call. Move quickly to review the numbers, weigh both sides, and decide whether the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond CleanSpark?
If CleanSpark has your attention, do not stop there. Use the Simply Wall St screener to uncover other opportunities that fit your style and risk tolerance.
- Target steady compounding potential by reviewing a curated 33 high quality undervalued stocks that combine fundamental strength with prices that some investors may see as conservative.
- Prioritize staying power and balance sheet resilience by scanning a list of solid balance sheet and fundamentals (23 results) that can better handle shocks and funding demands.
- Hunt for lesser known opportunities before the crowd by checking a 16 high quality undiscovered gems with quality metrics many investors are only starting to notice.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com