
SK Hynix (KOSE:A000660) Stock May Trade At A Discount On Earnings
SK hynix has delivered an extremely strong run over the past few years, which naturally puts a spotlight on whether the current share price is still grounded in its earnings. With that kind of history in the rear-view mirror, the key issue now is whether the income the business generates can carry the valuation where the market has taken it.
- Over the past 5 years, SK hynix has produced a share price gain that is close to 18x, which raises a direct question about how much earnings power is now being priced in.
- The company’s focus on memory and storage chips means future profitability can hinge on how efficiently it converts heavy capital spending into sustainable earnings and cash generation through the cycle.
- Your read on SK hynix is one view; the desks covering it have another. See what analysts think SK hynix's shares could be worth.
The stock's next move may depend on whether the current price fairly reflects what SK hynix is earning today and what those earnings reasonably support.
If you want a broader watchlist alongside SK hynix while you weigh what its earnings justify, a focused screener built around 179 high quality undervalued stocks can be a useful next research step.
Does SK hynix Look Undervalued on Earnings?
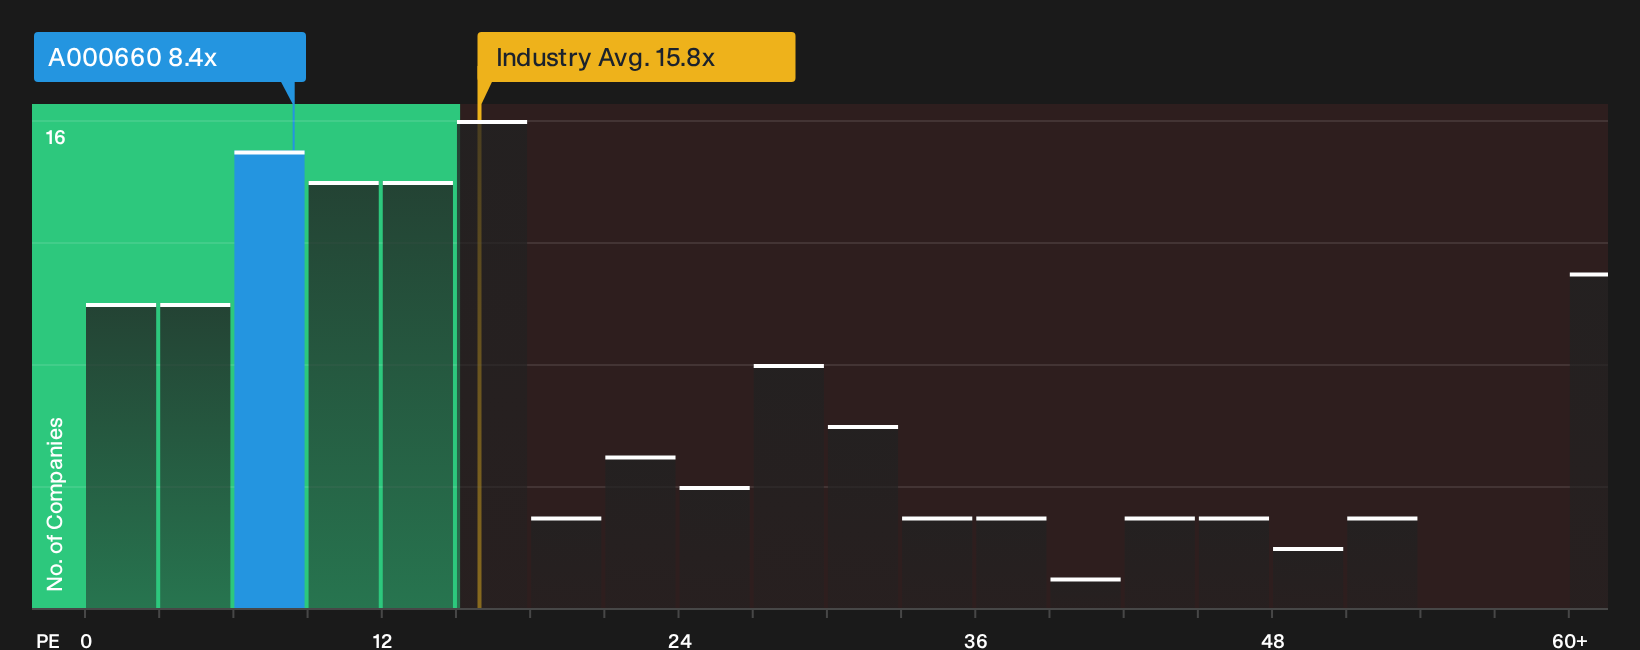
P/E works well for a chipmaker like SK hynix because earnings are a key anchor for how investors usually think about its value over a full cycle. On that lens, the stock trades on roughly 8.4x earnings, well below the semiconductor industry average of about 15.8x and also under the peer group near 47.2x. That is a wide gap to both the broader sector and closer competitors.
The fair multiple implied by a more tailored model, which factors in SK hynix's growth profile, margins, scale and risk, sits higher than where the current P/E is today. That suggests the shares screen as undervalued on this earnings yardstick. However, you still need to judge how reliable current profits are given the capital intensity and cyclicality of memory and storage. Explore the numbers behind SK hynix's P/E valuation.
The SK hynix Narrative: What Would Justify Today's Price?
SK hynix's recent run raises a simple question for anyone looking at the chart and the P/E side by side. Narratives on Simply Wall St’s Community page connect that valuation puzzle to a set of explicit assumptions about future growth, margins and earnings that would need to hold for the stock to be worth materially more or materially less than today’s price. Rather than one headline multiple or model result, each narrative sets out the key drivers behind its fair value view so you can compare those assumptions with SK hynix's actual results as they are reported.
Community views on SK hynix are split between a tight-supply AI winner story and a more cautious read on geopolitics and heavy spending.
Bull case: 62% undervalued
"SK hynix's accelerating investment in new fabs and advanced packaging, combined with visible long-term supply agreements with major hyperscalers, provides insulation against cyclical downturns…"
Discover why this Narrative puts SK hynix at 62% undervalued.
Bear case: 16% overvalued
"Intensifying geopolitical tensions, including tightening US export controls on China and persistent trade frictions, could severely restrict SK hynix's access to key international markets…"
Explore why this Narrative puts SK hynix at 16% overvalued.
One more SK hynix piece that could change how you see the stock
Price multiples and community narratives tell you what people think today. The next real check is where professional models expect SK hynix to be a few years from now. Explore where analysts expect SK hynix to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com