
U.S. Bancorp (USB) Just Gave Investors Something To Think About
U.S. Bancorp (USB) just raised its quarterly common-stock dividend to $0.54 per share, a 3.8% bump that comes alongside plans to resume buybacks and expectations for solid third quarter net interest and fee income.
Recent price action has been choppy. The share price has eased over the past week and month, yet U.S. Bancorp still shows an 11.37% year to date share price return and a 23.89% total shareholder return over the past year. This suggests momentum has been building over a longer horizon as dividend hikes, fresh bond issuance and new product launches keep the story moving.
Seize this moment around U.S. Bancorp's dividend move and compare it with a curated 6 dividend fortresses that share a focus on income and resilience.U.S. Bancorp’s richer dividend and planned buybacks signal management confidence, while the share price has cooled in recent weeks. Is the market rethinking the story, or simply slow to reflect the strength of the underlying business?
Most Popular Narrative: 14% Undervalued
U.S. Bancorp’s most followed valuation narrative points to a fair value of about $69.98 against a last close of $60.06, which frames the current dividend and buyback plans against a market price that still sits below that narrative estimate.
Continued investments in digital banking platforms and artificial intelligence are enabling durable operating efficiencies, expense control, and the potential for higher net margins, positioning the company to benefit from scale as customer banking preferences stay increasingly digital.
See why 94 investors see U.S. Bancorp as 14% undervalued.
Result: Fair Value of $69.98 (UNDERVALUED)
Still, U.S. Bancorp faces two clear swing factors: rising fintech competition in payments and ongoing credit risk around commercial real estate exposure.
Find out about the key risks to this U.S. Bancorp narrative.
Another View on U.S. Bancorp’s Valuation
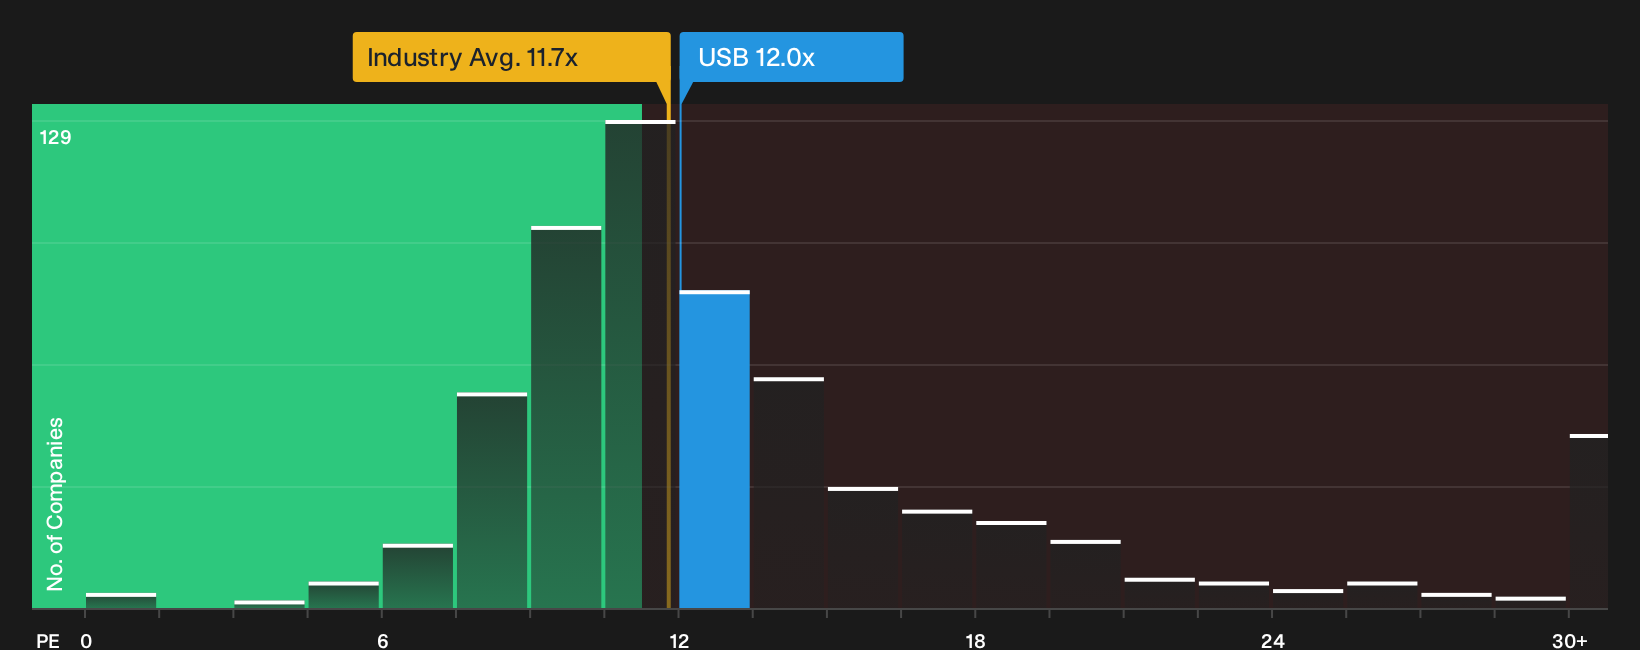
The first narrative leans on analyst targets and future earnings assumptions. A simpler P/E check paints a different picture. U.S. Bancorp trades around 12x earnings, slightly above the US Banks industry on 11.7x, yet below a peer average of 16.6x and a fair ratio estimate of 14.3x.
Put plainly, the stock looks a bit richer than the sector, but cheaper than similar banks and the level our fair ratio suggests the market could move toward. That mix of relative premium and potential catch up raises a practical question for investors. Is this a modest valuation risk or a pricing gap worth watching more closely?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around U.S. Bancorp’s valuation narrative and dividend reset make this a good moment to move from headline to homework and decide where you stand. To pressure test both the concerns and the upside potential, walk through the 4 key rewards and 1 important warning sign
Looking for more U.S. Bancorp-sized opportunities?
Do not stop with U.S. Bancorp. Use this momentum to scan fresh ideas, weigh different risk levels, and build a watchlist that fits your own playbook.
- Target dependable income streams by reviewing 6 dividend fortresses that focus on consistent payouts and balance sheet strength.
- Hunt for mispriced quality by checking the 33 high quality undervalued stocks that combine solid fundamentals with appealing valuations.
- Strengthen your downside protection by scanning the 30 resilient stocks with low risk scores that emphasise resilience and measured volatility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com