
Did $200 Million Loan Facility Just Shift Aura Minerals' (AUGO) Investment Narrative?
- Aura Minerals has secured a US$200,000,000 syndicated loan at the holding company level, paying interest of SOFR + 2.70% with a two year grace period and five year maturity, to fund supplier payments and prepayment of production and sales costs.
- The facility gives Aura Minerals added financial flexibility to support its project pipeline and day to day working capital without immediately tapping equity markets.
- We will look at how Aura Minerals' investment narrative evolves as it layers in this US$200,000,000 syndicated loan facility.
Aura Minerals Investment Narrative Recap
To own Aura Minerals, you need to be comfortable with a multi mine gold and copper operator that is still leaning into growth projects while carrying a meaningful debt load. The US$200,000,000 syndicated loan sits right in the middle of that equation. It supports supplier payments and production costs, so the near term focus stays on execution at Borborema, MSG, Almas and the rest of the portfolio.
The most important short term swing factor is operational delivery on ramp ups and productivity work, especially at MSG and Borborema. The biggest risk remains balance sheet pressure if cash generation falls short of expectations, given existing leverage and a new facility priced at SOFR + 2.70%. This news does not remove that risk, but it can soften liquidity strain if projects perform as planned.
The fresh loan announcement ties directly into Aura Minerals’ growth pipeline. Ramp up at Borborema and planned developments at Era Dorada and either Matupa or Guatemala all require consistent funding for contractors, materials and pre operating costs. This facility gives the group more room to keep those programs moving while maintaining operations across Minosa, Aranzazu, Almas and Apoena.
For you as a shareholder, the key question is whether that extra funding translates into reliable volume growth and cost control rather than creeping financial risk. Some analysts describe earnings as growing faster than the wider US market and classify the stock as trading well below certain fair value estimates. Actual project delivery, supported by this loan, will be what tests those expectations.
Aura Minerals’ current analyst narrative points to revenues of US$2.3b and earnings of US$1.0b by 2029, built on assumed yearly top line growth of 21.0% and an earnings increase of about US$701.4m from current earnings of US$298.6m.
Uncover why Aura Minerals' fair value indicates a 13% potential upside to its current price before that discount to Aura Minerals' valuation gap closes.
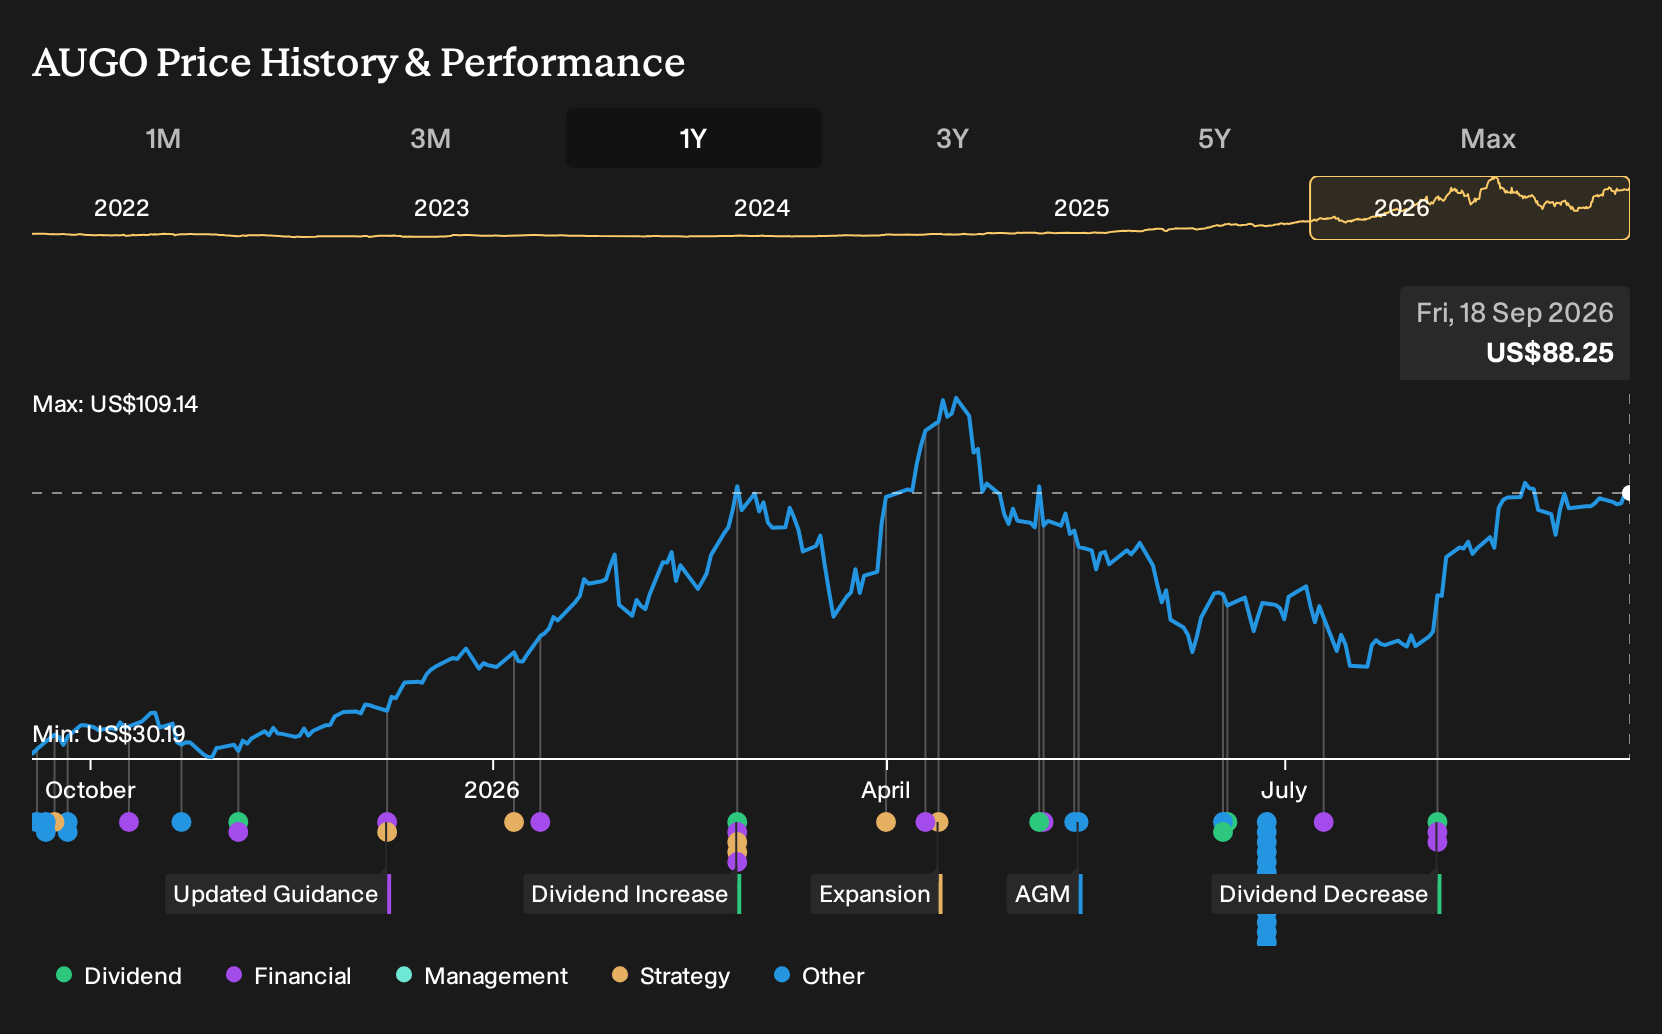
Exploring Other Perspectives
One alternate view puts execution risk front and center. Those more cautious analysts worried that big capex at Borborema, Era Dorada and Matupá could squeeze free cash flow, so they were only pencilling in about US$2.1b of 2029 revenue and US$819.7m of earnings. This new Aura Minerals loan may nudge those stories in new directions.
Explore 4 other Aura Minerals fair value estimates, including one that suggests as much as 6% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider doing your own research and going with your instincts.
- A great starting point for your Aura Minerals research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Aura Minerals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate Aura Minerals' overall financial health at a glance.
Looking For More Investment Ideas Beyond Aura Minerals?
If the Aura Minerals story has sharpened your thinking about risk, funding and project pipelines, it can help to line it up against other opportunities. The Simply Wall St Screener gives you a structured way to scan for stocks that better match your risk appetite, income needs or valuation preferences.
- For investors who want potential mispricing on their side, consider starting with a curated 33 high quality undervalued stocks that already clears quality and balance sheet checks.
- If capital preservation and stability matter most to you, narrow the field to a 30 resilient stocks with low risk scores that scores well on financial strength and lower volatility.
- When the goal is to spot under followed opportunities with solid fundamentals, filter for a 16 high quality undiscovered gems that might not yet be widely watched.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com