
How Investors May Respond To USA Compression Partners (USAC) $600 Million Debt Raise
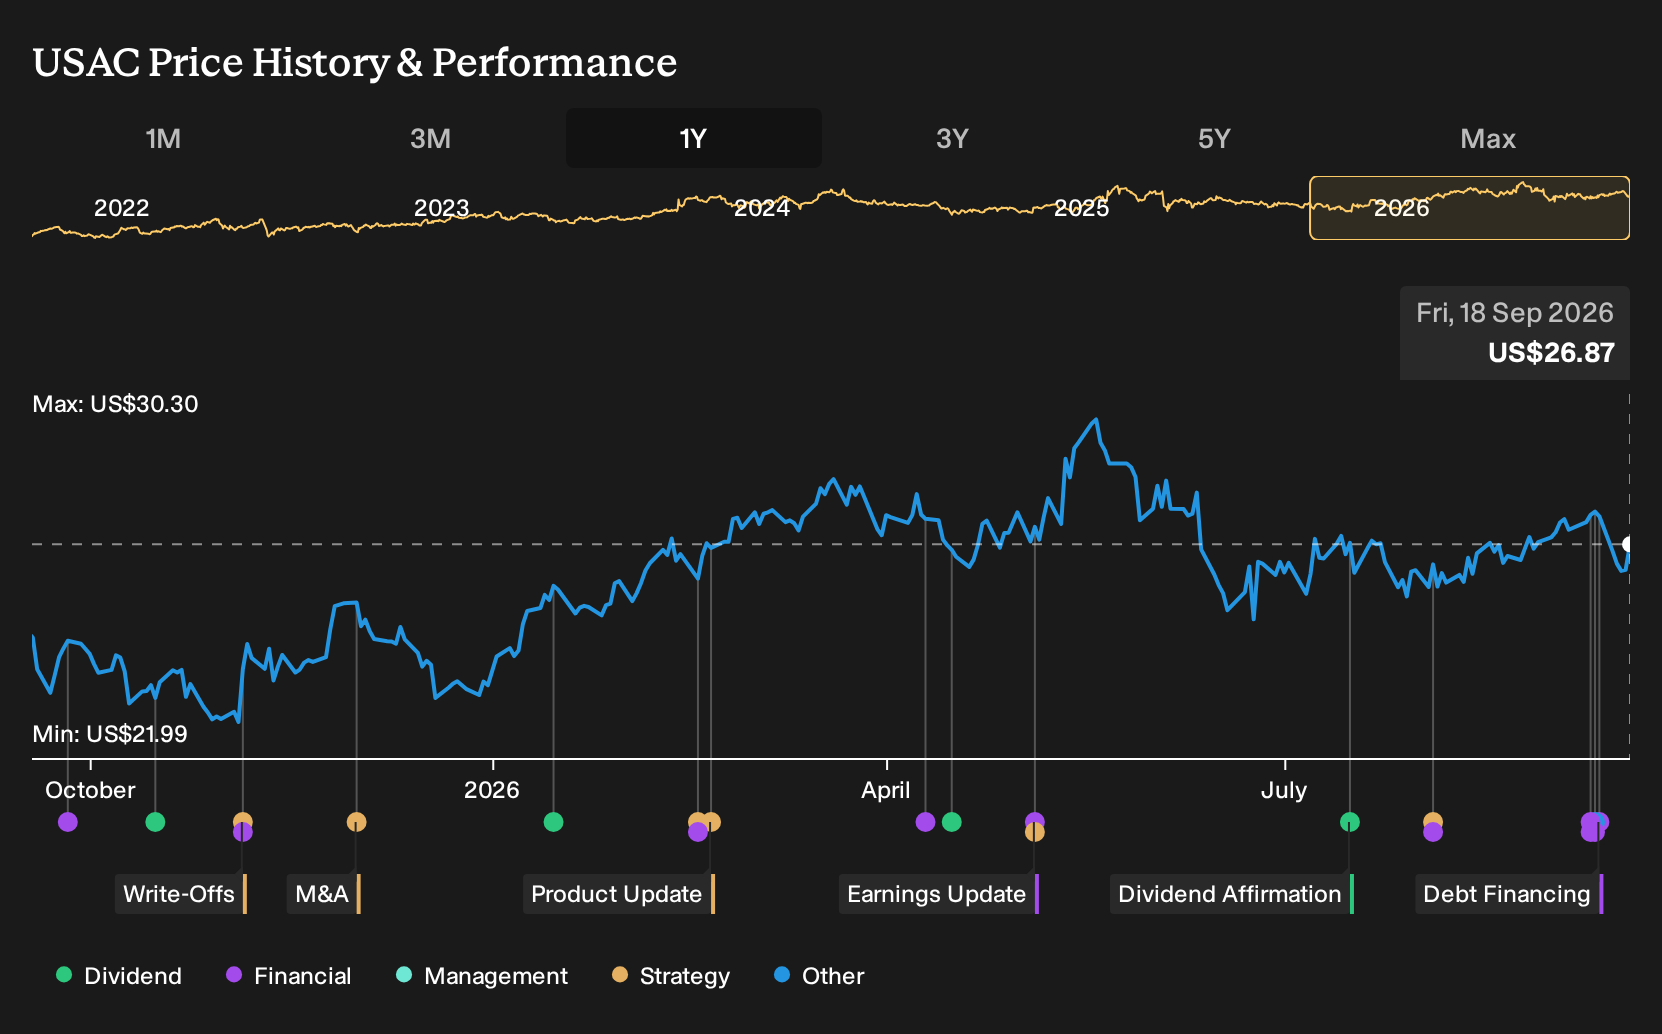
- USA Compression Partners priced a private placement of US$600 million senior unsecured notes due 2035 at a 6.750% coupon, with about US$592.1 million in expected net proceeds earmarked mainly to repay borrowings under its credit agreement.
- The partnership is also shifting its common unit listing from the NYSE to the Texas Stock Exchange. This move could reshape trading liquidity and investor access even as USA Compression Partners fine tunes its capital structure with new long dated debt.
- We will now assess how USA Compression Partners' investment narrative might shift as fresh 2035 notes refinance bank debt and trading moves to Texas.
USA Compression Partners Investment Narrative Recap
To own USA Compression Partners, you need to be comfortable with a capital intensive compression services business that leans on long term contracts and a distribution heavy payout. The near term story still revolves around keeping fleet utilization and pricing healthy enough to support earnings, while managing a balance sheet already carrying meaningful debt and interest obligations.
The new 6.750% 2035 notes primarily refine the funding mix rather than change the operating story. The key short term swing factor remains contract activity linked to natural gas infrastructure buildout. The biggest risk stays the same. A combination of customer concentration and high leverage could strain cash flows if activity or pricing softens.
The most relevant update is the US$600 million senior unsecured notes due 2035. This refinancing shifts borrowings from the credit facility into long dated fixed rate debt. That can give management more visibility on interest costs as they work through fleet investments, shared services with Energy Transfer, and cost discipline across engines, parts, and labor.
There is a trade off. Higher fixed coupon payments sit on top of a payout that analysts already flag as thinly covered. Execution now leans on keeping renewal rates high, protecting pricing on high horsepower units, and avoiding hiccups with large customers. If any of those weaken, the added interest load could tighten room to maneuver on distributions and new growth projects.
USA Compression Partners' current analyst storyline points to revenues of US$1.5b and earnings of US$271.6m by 2029, based on 12.3% yearly revenue growth and an earnings increase of about US$146.4m from US$125.2m today.
Uncover how USA Compression Partners' fair value indicates a 10% potential upside to its current price before that discount starts to close.
Exploring Other Perspectives
Only two fair value estimates from the Simply Wall St Community cluster tightly between about US$27.17 and US$29.67 per unit, so you are seeing a narrow band rather than extreme views. That leaves room for you to weigh USA Compression Partners' higher leverage, refinancing and upcoming Texas Stock Exchange listing as you compare more community opinions.
Explore another USA Compression Partners fair value estimate, including one that suggests as much as 10% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your USA Compression Partners research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for USA Compression Partners. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate USA Compression Partners' overall financial health at a glance.
Looking for more investment ideas beyond USA Compression Partners?
Once you have a view on USA Compression Partners, it can help to compare it with other opportunities that match your income goals, risk tolerance, and quality criteria using the Simply Wall St Screener.
- If you want potential value combined with quality fundamentals, scan a curated set of 33 high quality undervalued stocks that may warrant a closer look.
- For investors who prioritize dependable balance sheets, filter opportunities using the list of solid balance sheet and fundamentals (23 results) to see businesses with sturdier financial footing.
- If you are hunting for lesser known opportunities with solid metrics, cast a wider net across a 16 high quality undiscovered gems that might not yet be widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com