
Is AMETEK (AME) Priced Too Richly Following Its Laguna Conference Appearance?
Conference appearance puts AMETEK in focus
AMETEK (AME) heads into Morgan Stanley's 14th Annual Laguna Conference on September 15, 2026, with investors watching how management frames the business after a solid year of share price gains.
The conference, held at The Ritz Carlton Laguna Niguel in California, offers AMETEK a platform to update institutions on its electronic instruments and electromechanical segments, which together generated revenue of about US$7.9b and net income of roughly US$1.6b.
Recent trading has cooled a little, with the 7 day share price return down 1.75% and the 30 day share price return down 0.80%. However, AMETEK still carries a year to date share price gain of 13.63% and a 1 year total shareholder return of 27.27%. This points to momentum that has been building over several years, given the 3 year and 5 year total shareholder returns of 59.72% and 89.40% respectively, as investors weigh growth potential against risk ahead of the Laguna conference.
Scan how AMETEK compares with other industrial leaders by reviewing a curated set of list of solid balance sheet and fundamentals (23 results).
After a strong 1 year run and a recent pause, AMETEK now forces a choice. Do you pay up today for consistency, or wait and hope for a better entry after Laguna?
Most Popular Narrative: 14% Undervalued
AMETEK's most followed valuation story pegs fair value at $277.50, above the recent $237.64 close, which puts extra weight on what management says at Laguna.
Adoption of digital reality, automation, and advanced metrology solutions is accelerating across key end markets such as aerospace, defense, and architecture, recently reinforced by the FARO Technologies acquisition, expanding AMETEK's addressable market and supporting both revenue and margin growth through higher value, software-enabled recurring revenue streams.
See why 17 investors see AMETEK as 14% undervalued.
Result: Fair Value of $277.50 (UNDERVALUED)
Still, the AMETEK story depends on assumptions that can break, including weaker demand in semiconductor or research budgets and any difficulties integrating recent acquisitions.
Find out about the key risks to this AMETEK narrative.
Another View on AMETEK's valuation
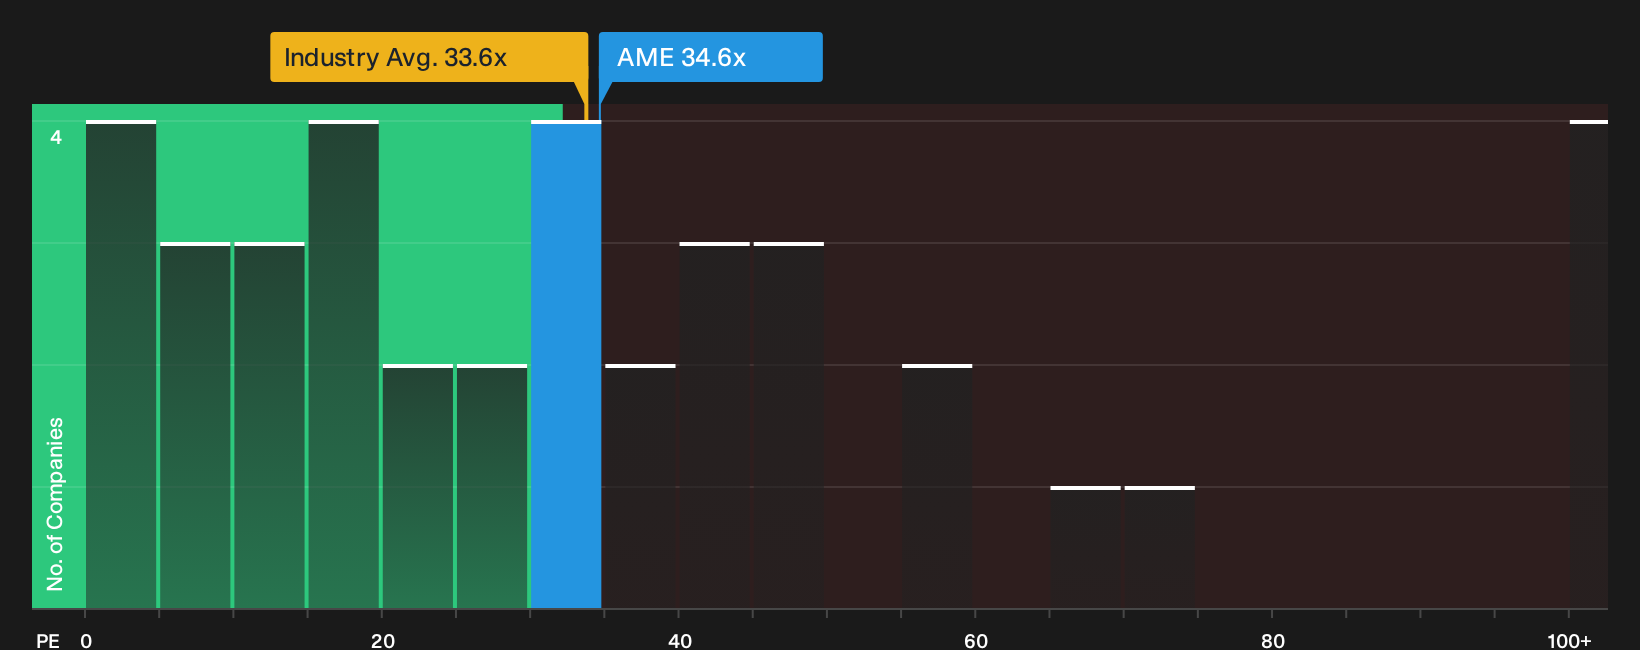
Analyst narratives frame AMETEK as about 14% undervalued at $277.50, yet the market is already paying a P/E of 34.6x. That is higher than the estimated fair ratio of 27.3x and above the US Electrical industry at 33.6x, which leaves less room if expectations cool.
For a closer look at how this pricing stacks up against the broader market and peers, have a look at our valuation breakdown, then weigh how much optimism you want to price into AMETEK at today’s multiple. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on AMETEK is upbeat yet cautious, which is exactly when it can be useful to move quickly and test the story against your own expectations. To see what is driving that optimism and how it lines up with your thesis, start with the 2 key rewards
Looking for more AMETEK style investment ideas?
If AMETEK has sharpened your focus on quality, now is the moment to cast a wider net and pressure test your watchlist against fresh ideas.
- Target potential mispricings by scanning companies that combine quality fundamentals with attractive valuations through the 33 high quality undervalued stocks.
- Anchor your portfolio with steady income prospects by reviewing a lineup of reliable payers using the 6 dividend fortresses.
- Dial up resilience by filtering for businesses with strong financial footing via the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com