
Will Repeat Ona Licensing Change WuXi XDC Stock Narrative
- WuXi XDC Cayman announced that Ona Therapeutics has obtained an exclusive global license to the WuXiTecan-2 payload-linker platform for one antibody drug conjugate, with WuXi XDC also providing chemistry, manufacturing and controls support plus potential upfront, milestone and royalty revenues.
- The new out-licensing deal, the second ADC collaboration between WuXi XDC and Ona in two years, points to recurring client demand for WuXi XDC’s proprietary linker payload capabilities and deeper integration of its ADC CRDMO offering into partners’ pipelines.
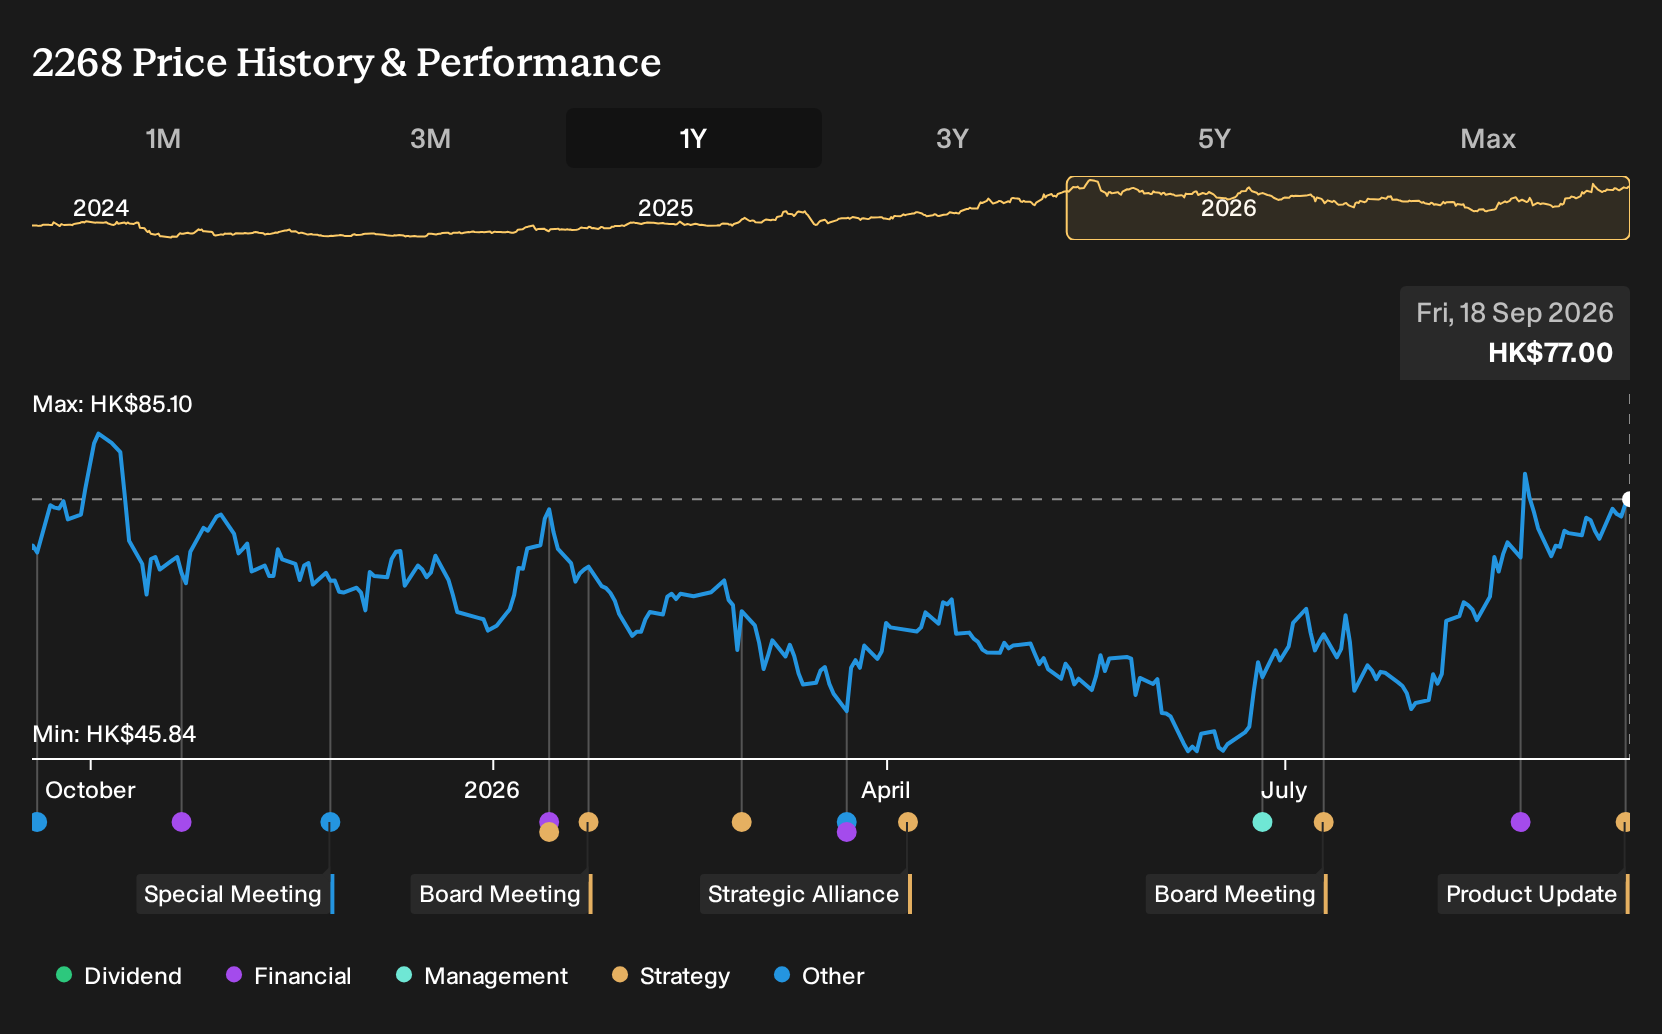
- This development highlights how WuXi XDC Cayman's investment narrative is influenced by repeat Ona licensing of the WuXiTecan-2 ADC platform.
WuXi XDC Cayman Investment Narrative Recap
For WuXi XDC Cayman, the core belief is that antibody drug conjugates and wider bioconjugates keep deepening the project funnel, and that the company converts that work into higher value services over time. The Ona agreement helps here, but the most important near term swing factor still looks like how quickly new capacity in China and Singapore fills.
The biggest operational risk remains underutilization if ADC demand or client project advancement slows, especially with BioDlink and Singapore still ramping. This Ona extension helps support the backlog and project pipeline. On its own, though, the deal does not materially change that utilization risk in the short run.
The fresh Ona Therapeutics license on the WuXiTecan-2 platform is the clearest recent datapoint tied to this story. It reinforces that WuXi XDC Cayman is not just supplying capacity. It is selling proprietary linker payload technology plus CMC support wrapped into a broader ADC CRDMO service, which matters for how much value each project can carry.
For catalysts, investors are still likely watching how the US$2.2b service backlog converts into recognized sales, and how quickly Singapore and other newer facilities pass audits and commercialize work. The Ona deal feeds that funnel and may support higher value work per program, while the familiar risks of competition, pricing pressure and slower client R&D cycles remain intact.
WuXi XDC Cayman's current analyst narrative points to CN¥15.6b in revenue and CN¥3.9b in earnings by 2029, based on an assumed 30.9% yearly revenue growth rate and an earnings increase of about CN¥2.3b from CN¥1.6b today.
Uncover how WuXi XDC Cayman's fair value indicates a 20% potential upside to its current price before that discount closes.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between about 92 and 103, which already shows how far private investors can spread on WuXi XDC Cayman. Those views were formed before the fresh Ona license and before any impact on capacity utilization risk, so use them as a starting line and compare several alternative takes.
Explore 2 other WuXi XDC Cayman fair value estimates, including one that suggests it could be worth just HK$92.10.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your WuXi XDC Cayman research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for WuXi XDC Cayman. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate WuXi XDC Cayman's overall financial health at a glance.
Looking For More Ideas Beyond WuXi XDC Cayman?
If WuXi XDC Cayman has put ADC contractors on your radar, it can be useful to widen the lens and compare it with other businesses that fit different quality or risk profiles. The Simply Wall St Screener lets you filter by balance sheet strength, valuation and income potential so you can build a watchlist that matches your own approach rather than relying on a single stock story.
- For investors who want staying power over excitement, consider businesses with strong finances and robust cash generation by starting with this curated list of solid balance sheet and fundamentals (198 results).
- If value is your priority and you want candidates where the market price sits below fundamental estimates, use this focused 179 high quality undervalued stocks as a hunting ground.
- Those aiming to build a portfolio with meaningful income potential can scan for higher yielding payers through this targeted 156 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com