
Why Did Bruker (BRKR) Move As Investors Take A Closer Look?
Bruker (BRKR) is presenting to investors at two healthcare conferences, starting with Wells Fargo in Boston on September 9, followed by Morgan Stanley in New York on September 16, putting its scientific instruments business under closer scrutiny.
The recent 14.9% 7 day share price return and 27.6% year to date gain suggest momentum has been building in Bruker, while the 85.99% 1 year total shareholder return contrasts with slightly negative 3 and 5 year total shareholder returns. This highlights how quickly sentiment around the stock has shifted.
Spot similar momentum shifts beyond Bruker by scanning our hand picked 33 high quality undervalued stocks, which combines recent strength with solid underlying fundamentals.Bruker’s sharp one year swing invites a simple test. Are investors finally catching up with what the instruments and diagnostics franchise is doing, or has sentiment run ahead of what the current fundamentals support?
Most Popular Narrative: 3% Overvalued
At a last close of $61.39 against a widely followed fair value estimate of $59.75, Bruker is framed as slightly expensive, with that small gap putting extra weight on whether the current tools story can really hold up over time.
The analysts have a consensus price target of $59.75 for Bruker based on their expectations of its future earnings growth, profit margins and other risk factors. In order for you to agree with the analysts, you would need to believe that by 2029, revenues will be $4.1 billion, earnings will come to $328.4 million, and it would be trading on a PE ratio of 35.4x, assuming you use a discount rate of 8.2%.
See why 17 investors see Bruker as 3% overvalued.
Result: Fair Value of $59.75 (OVERVALUED)
Still, pressure on research funding in the US and China, along with weaker order backlogs, could quickly challenge the upbeat Bruker narrative that investors are leaning on.
Find out about the key risks to this Bruker narrative.
Another View On Bruker’s Valuation
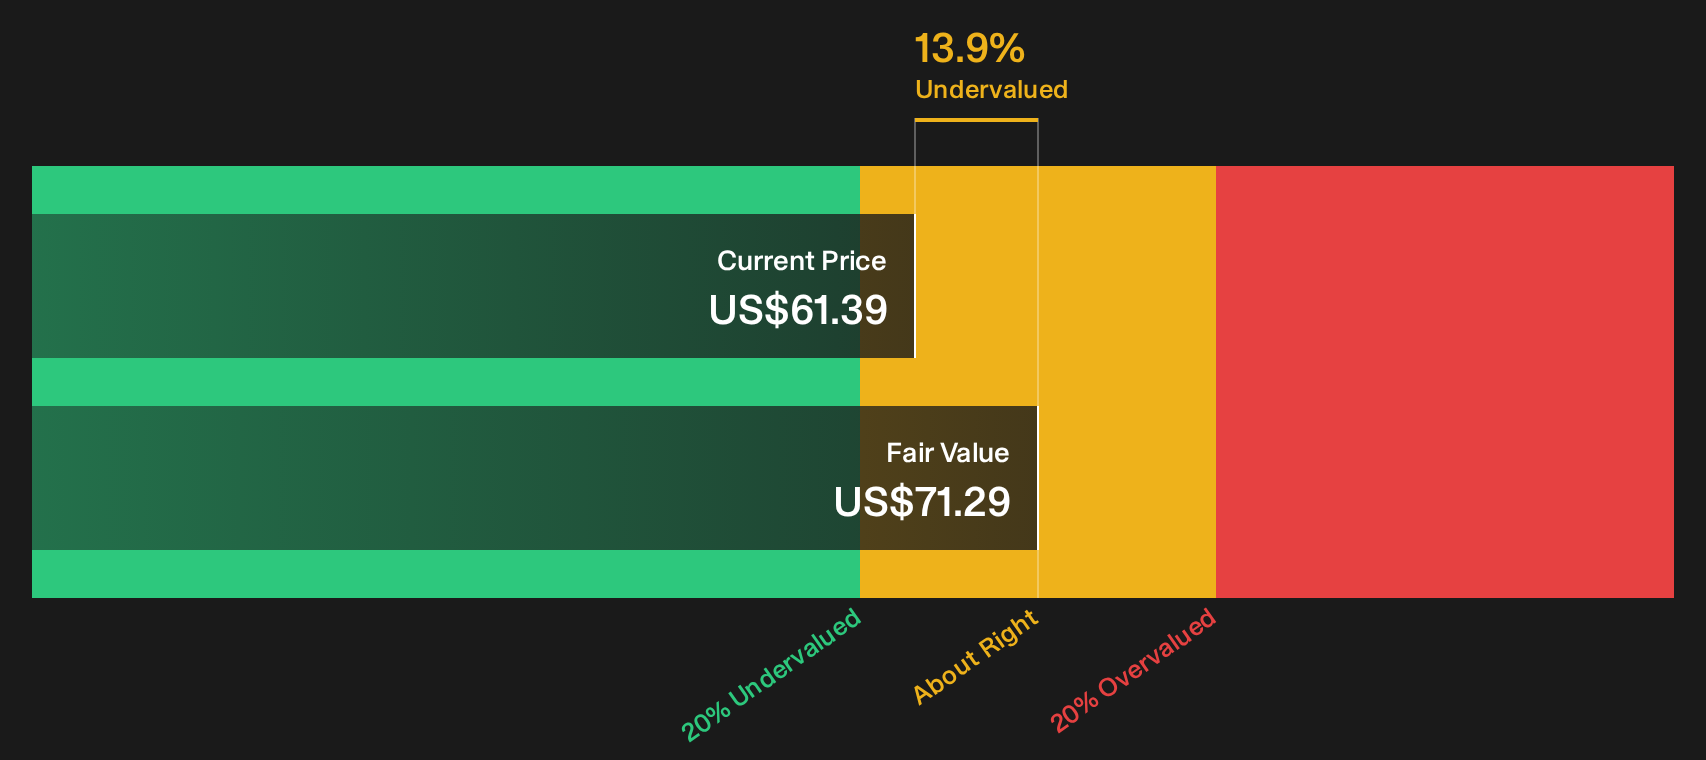
Analysts tilt toward Bruker being slightly overvalued at $61.39 versus a $59.75 fair value, yet the firm’s own metrics tell a different story. Our DCF model points to a future cash flow value of $71.29, which frames the current quote as trading at a discount instead of a premium. That leaves a simple question for you: which set of assumptions feels more realistic?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
That mix of optimism and caution around Bruker sets the tone. If you want to act while sentiment is still forming, weigh both sides by checking the 3 key rewards and 1 important warning sign
Looking for more Bruker sized investment ideas?
Do not stop your research at Bruker. Use fresh ideas from carefully filtered lists to keep building a watchlist that really earns your attention.
- Target stability first by checking companies with resilient balance sheets and consistent fundamentals through our list of solid balance sheet and fundamentals (23 results).
- Chase quality at a reasonable entry point by scanning the 33 high quality undervalued stocks before pricing shifts away from you.
- Spot potential market leaders early by reviewing the 16 high quality undiscovered gems that rarely appear on mainstream radars.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com