
Why Altius Minerals (TSX:ALS) Is Getting Attention Now
Recent trading has put Altius Minerals (TSX:ALS) back on radar for investors watching royalty-focused resource businesses. The stock has logged gains over the past month and past 3 months, alongside double-digit 1-year total return.
At a CA$67.83 share price, Altius Minerals has recently posted a 30-day share price return of 5.54% and a year-to-date share price return of 64.40%, while longer term total shareholder returns of 114.46% over 1 year and 234.94% over 3 years signal momentum that has been building rather than fading.
Scan for other royalty and resources plays showing similar momentum to Altius Minerals by reviewing the hand picked 9 high quality undiscovered gems that share strong fundamentals and under the radar profiles.
Altius Minerals has already delivered a powerful run, yet the current share price still sits below both analyst targets and some intrinsic value estimates. Is most of the upside now spent, or is the market still catching up?
Most Popular Narrative: 2% Overvalued
At a CA$67.83 share price versus a narrative fair value of about CA$66.29, Altius Minerals is only slightly above that reference point. This puts the spotlight on how future royalties and financing choices could shift that balance.
The sizeable liquidity build from recent royalty sales, coupled with a historically patient capital deployment approach, increases the risk that cash remains underutilized for an extended period. This would dilute return on equity and constrain growth in per share earnings if reinvestment lags.
See why 4 investors see Altius Minerals as 2% overvalued.
Result: Fair Value of CA$66.29 (OVERVALUED)
Still, two things could quickly reframe that 2% overvaluation call on Altius Minerals: faster deployment of its sizeable cash pile, and stronger-than-modeled royalty volumes from key projects.
Find out about the key risks to this Altius Minerals narrative.
Another View On Altius Minerals Valuation
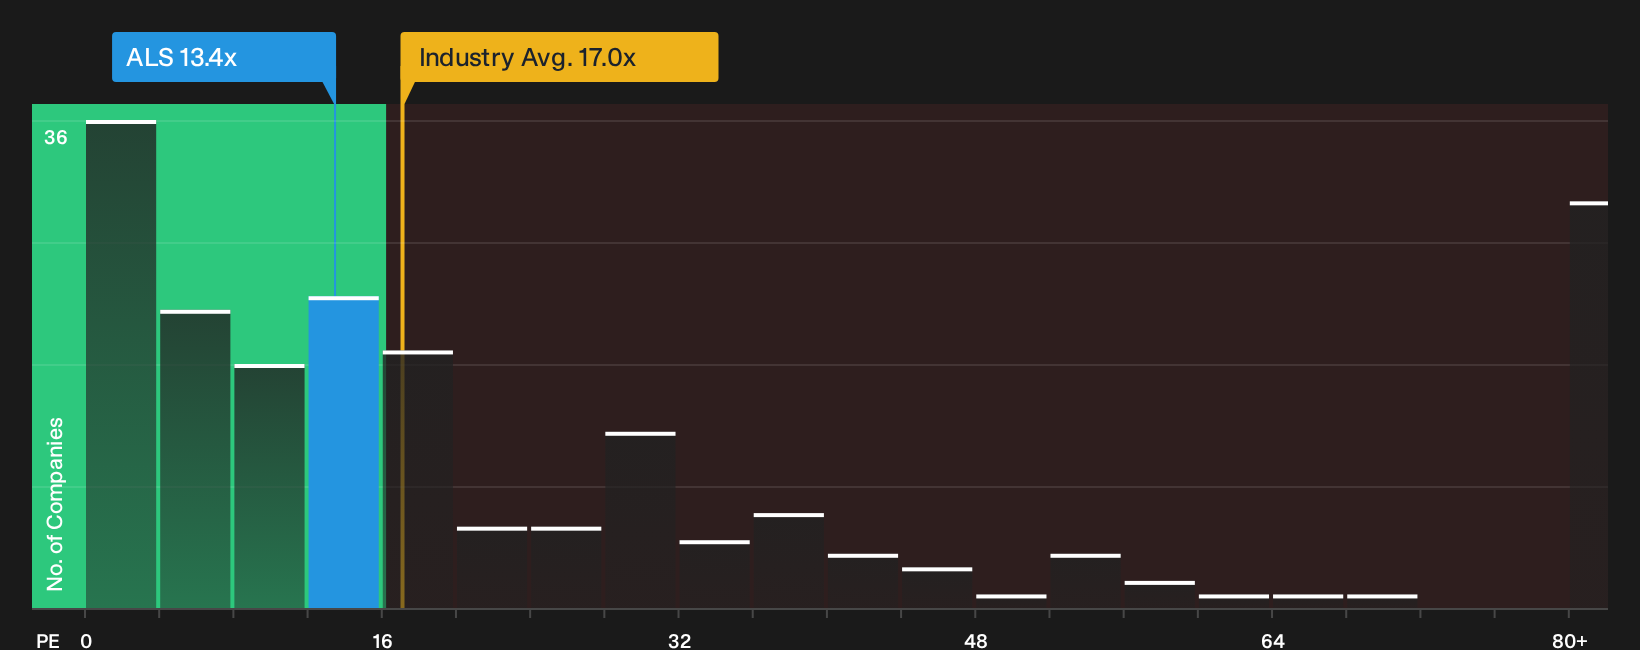
The earlier fair value narrative has Altius Minerals about 2% above its CA$66.29 reference point, which hints at a mildly rich price. On a simple P/E check, things look very different. The stock trades on 13.4x earnings, while peers sit near 29.4x, and the estimated fair ratio is 7.8x.
That mix suggests investors are paying less than the sector on earnings, yet still above the fair ratio that the market could eventually move toward. Is that a margin of safety or a sign that expectations have already crept ahead of fundamentals?
Investors who lean more on earnings multiples than on narrative fair value can pressure test their view by stepping through the detailed valuation work in our breakdown. They can then weigh how much comfort that lower P/E really provides relative to peers and the fair ratio benchmark. See what the numbers say about this price — find out in our valuation breakdown.
For a visual read on how Altius Minerals stacks up against the broader group, review the comparative chart that lines up its current valuation against industry levels and the fair ratio reference point.
Next Steps
Are investors seeing mixed signals or a clearer narrative forming around Altius Minerals? Act while the facts are current and consider both perspectives with the help of 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Altius Minerals?
If the Altius Minerals story has you thinking about what else might be hiding in plain sight, now is the time to widen your search with a few focused screens.
- Target potential upside by reviewing companies that screen as 4 high quality undervalued stocks before others start paying attention.
- Prioritise resilience by checking a curated list of solid balance sheet and fundamentals (7 results) that can help steady your portfolio when conditions change.
- Hunt for overlooked opportunities by scanning a 21 elite penny stocks with strong financials that pairs smaller market caps with stronger financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com