
Ryman Hospitality Properties (RHP) Could Be 12% Undervalued On Its Latest Resort Deal
Ryman Hospitality Properties (RHP) has been active in September, declaring a third quarter cash dividend of $1.20 per share and recently closing the acquisition of the Grande Lakes Orlando Resort for about $1.38 billion.
Against that backdrop, Ryman Hospitality Properties’ share price has climbed 27.71% year to date, while the 1-year total shareholder return of 33.82% and 3-year total shareholder return of 70.87% suggest momentum has been building despite a 5.11% 30-day share price pullback as the market weighs the Grande Lakes deal and ongoing dividend income together.
Scan how Ryman Hospitality Properties compares with other hotel and leisure real estate plays by reviewing the hand picked list of solid balance sheet and fundamentals (23 results) for potential additions to your watchlist.
Ryman Hospitality Properties now trades below both analyst targets and an internal fair value estimate, even after the Grande Lakes deal and dividend news reset expectations. Is that discount reflecting caution or mispricing?
Most Popular Narrative: 12% Undervalued
Ryman Hospitality Properties is trading at $121.94 against a widely followed fair value estimate of about $138.79. This frames the current pullback as a valuation gap that depends on how durable future earnings from Grande Lakes and the broader portfolio prove to be.
Recent acquisitions and ongoing capital investments (e.g., JW Marriott Desert Ridge, meeting space upgrades at Gaylord properties) put Ryman in a strong position to capitalize on renewed appetite for large-scale experiential travel and gatherings, supporting revenue growth and long-term cash flow.
See why 7 investors see Ryman Hospitality Properties as 12% undervalued.
Result: Fair Value of $138.79 (UNDERVALUED)
Still, Ryman Hospitality Properties carries real execution risk if new hotel supply and labor cost inflation pressure margins, or if group travel demand softens from current expectations.
Find out about the key risks to this Ryman Hospitality Properties narrative.
Another View: What Ryman Hospitality Properties’ P/E Is Telling You
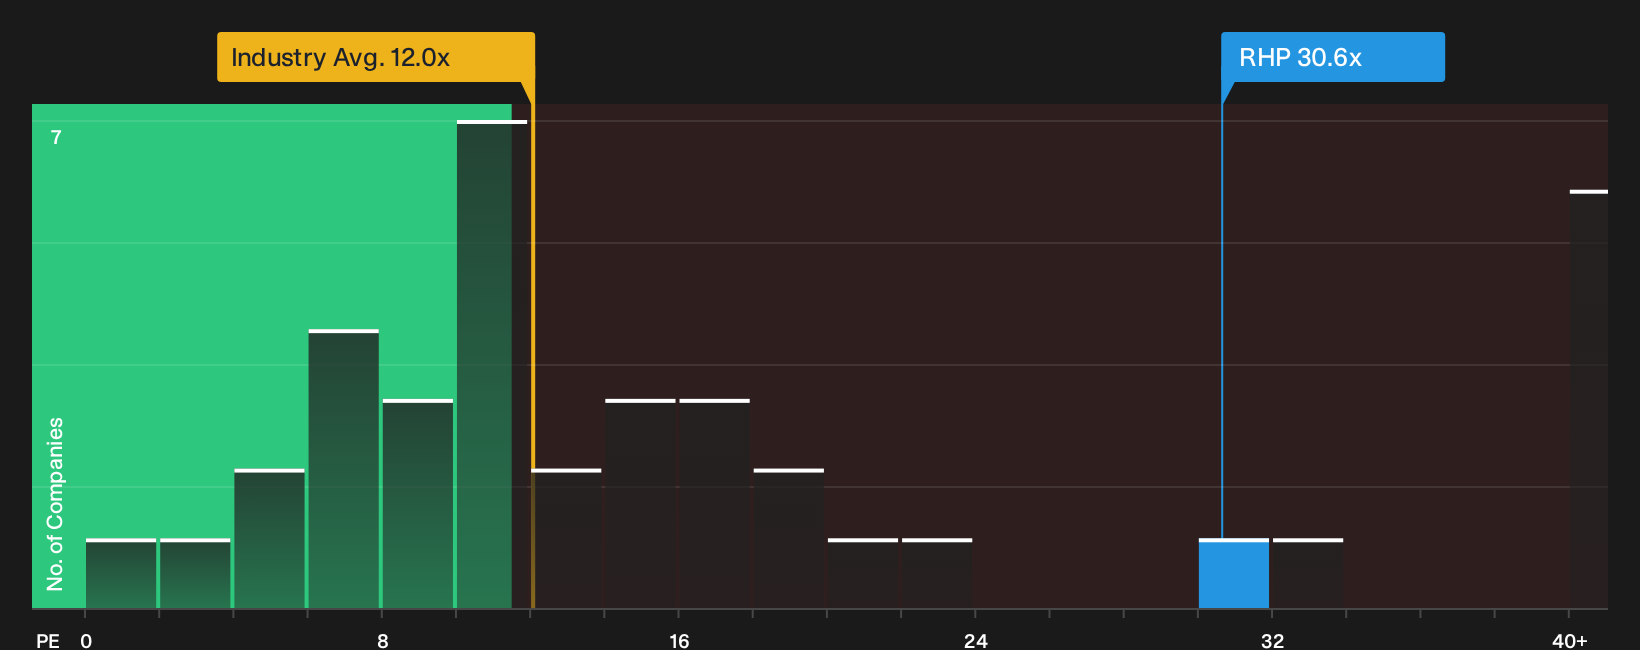
The cash flow work points to Ryman Hospitality Properties trading at a discount, yet the earnings multiple paints a very different picture. The stock changes hands at a P/E of 30.6x, compared with 12x for the global Hotel and Resort REITs group and 25.3x for peers, even though the fair ratio estimate sits higher at 41.6x. That gap suggests investors face a real trade off between paying up for perceived quality today and waiting to see if expectations or the share price move closer to that fair ratio in time.
See what the numbers say about this price and how they stack up to peers in the valuation breakdown by checking See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Ryman Hospitality Properties can feel tricky, so move quickly from headlines to hard numbers and shape your own thesis by weighing its 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Ryman Hospitality Properties?
If Ryman Hospitality Properties has your attention, do not stop here. Broader ideas can sharpen your portfolio and help you spot opportunities others ignore.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (23 results) that meet your quality bar before risks pile up elsewhere.
- Hunt for priced-in pessimism that may not match business strength by reviewing the 33 high quality undervalued stocks that could offer more upside than the crowd expects.
- Build a list of potential income workhorses by checking the 7 dividend fortresses that clear your yield and stability thresholds.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com