
ESCO Technologies (ESE) Shares Just Moved, What Is Driving Attention Now?
ESCO Technologies (ESE) is drawing fresh attention after investors focused on its multi-year backlog tied to submarine and underwater defense programs, where naval filtration and power systems play a central role in future revenue visibility.
Recent trading has been choppy for ESCO Technologies, with the share price down 24.67% over the past 90 days and 7.42% over the last month. At the same time, the year to date share price return of 34.56% sits against a 5 year total shareholder return of 251.65%. This suggests longer term momentum has been strong while shorter term sentiment has cooled as investors reassess how quickly the submarine focused backlog turns into reported results.
Scan ESCO Technologies alongside other defense and infrastructure contractors by reviewing the hand picked 39 power grid technology and infrastructure stocks positioned to benefit from long duration government backed projects.
After a sharp pullback yet a strong multi year run, ESCO Technologies now asks a simple question of investors: Does the current setup skew the risk reward toward fresh buyers or toward those already in the stock?
Most Popular Narrative: 31% Undervalued
On the Simply Wall St narrative, ESCO Technologies screens as undervalued, with a fair value of $385 against a last close of $265.92. That gap only matters if you think the underlying thesis on power infrastructure and defense demand holds together.
Continued long-term growth in global electricity demand, driven by trends such as electrification of transportation, grid expansion for data centers and AI, and increased renewable integration, positions ESCO's Utility Solutions Group and Doble for sustained order momentum and rising recurring revenues in utility infrastructure, supporting future top-line growth and improved earnings visibility.
See why 2 investors see ESCO Technologies as 31% undervalued.
Result: Fair Value of $385 (UNDERVALUED)
Still, the ESCO Technologies story can unravel if geopolitical or tariff shocks hit its global supply chain, or if the Maritime acquisition delivers weaker than expected integration benefits.
Find out about the key risks to this ESCO Technologies narrative.
Another View: ESCO Technologies Through The P/E Lens
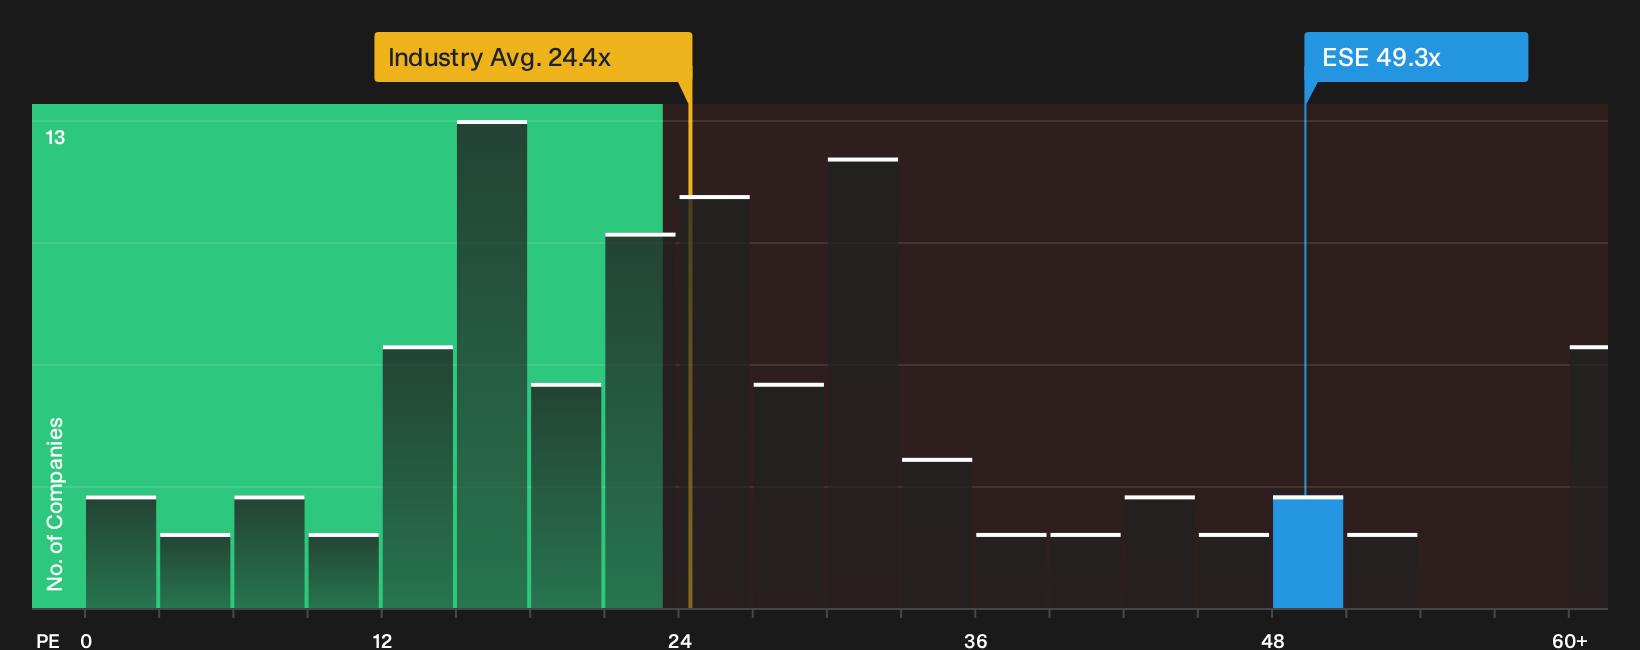
There is a catch with ESCO Technologies on simple valuation ratios. The stock trades on a P/E of 49.3x, while the Machinery industry sits around 24.4x and the fair ratio from the model is 27.1x. That implies investors today are paying up heavily for future execution. Is that a premium you are comfortable underwriting?
To see how that premium compares with peers and what the fair ratio could mean for future repricing, take a look at the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around ESCO Technologies is mixed, with valuation upside on one side and execution risk on the other. Move quickly and stress test the thesis against independent data points, including the 4 key rewards.
Looking for more investment ideas beyond ESCO Technologies?
If ESCO Technologies has sharpened your thinking on quality and valuation, you can keep that momentum going by widening your watchlist with a few focused screeners.
- Target resilient balance sheets and stronger fundamentals by reviewing the list of solid balance sheet and fundamentals (23 results) that could better handle tougher business conditions.
- Hunt for mispriced quality by scanning the 33 high quality undervalued stocks that might offer more compelling entry points than what is already on your radar.
- Secure potential income streams by checking the 7 dividend fortresses that combine higher yields with more robust financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com