
Adidas Stock And Youth Footwear Names Worth Watching After The Converse Ad Backlash
Converse and Nike are under the spotlight after a pulled global ad raised fresh questions about how fast brand reputation can shift in a social media storm. That kind of scrutiny can create pockets of opportunity for investors watching youth-focused footwear, where sentiment sometimes moves faster than fundamentals. This article walks through three stocks exposed to the same theme and explains how this controversy might matter for your watchlist.
The stocks covered below are only a small sample of what sits in youth-oriented athletic footwear and athleisure, and the full screen surfaced 39 more listed businesses with equally compelling narratives that are not unpacked in this article.
If you want to go straight to the source, analyze, compare, and identify your highest conviction angles in this theme by working through the Youth-Focused Athletic Footwear and Athleisure Brands screener.
On Holding (ONON)
Overview: On Holding is a Zurich based performance footwear and apparel company focused on premium running, training and athleisure for trend driven consumers.
Operations: On Holding generates about CHF 3.2b from athletic footwear, with CHF 616 million reported from Asia Pacific alongside a large segment adjustment.
Market Cap: US$9.1b
On Holding fits this youth focused footwear screen because the brand is built around performance gear that also works as everyday style. This matters when social media can quickly reward or punish what younger runners and gym goers choose to wear.
Expansion of On's premium global brand, amplified by elite athlete victories and culturally resonant collaborations with figures like Zendaya and Burna Boy, is deepening demand among younger and more affluent consumers worldwide.
The real swing factor for On Holding is how one unseen pressure on its premium pricing power ultimately plays out with those fans.
That pressure on pricing is exactly what the full narrative for On Holding unpacks, showing where On Holding's brand heat could be masking risk or accelerating upside.

Birkenstock Holding (BIRK)
Overview: Birkenstock Holding designs and sells footbed based sandals, clogs and closed toe footwear that have become fashion staples for younger consumers globally.
Operations: Birkenstock Holding generated about €1.14b in the Americas, €863 million in EMEA and €257 million in APAC from footwear sales.
Market Cap: US$5.4b
Birkenstock Holding fits this youth focused footwear theme as a comfort brand that has crossed over into social media driven fashion. Shifts in taste or online sentiment can matter quickly when investors are assessing how durable that appeal really is.
Expansion of owned retail to an expected 140 doors by the end of fiscal 2026 and ongoing high single digit same-store sales growth increase Birkenstock Holding's control over pricing and product mix.
What happens to margins if one quietly building cost and demand imbalance in that premium mix starts to bite just as expansion peaks?
If that pressure really bites, read the full narrative for Birkenstock Holding to see how Birkenstock Holding's expansion math could be accelerating or quietly stalling future returns.

adidas (XTRA:ADS)
Overview: adidas designs and sells athletic footwear, sportswear, and related gear worldwide, targeting performance needs and trend driven lifestyle demand.
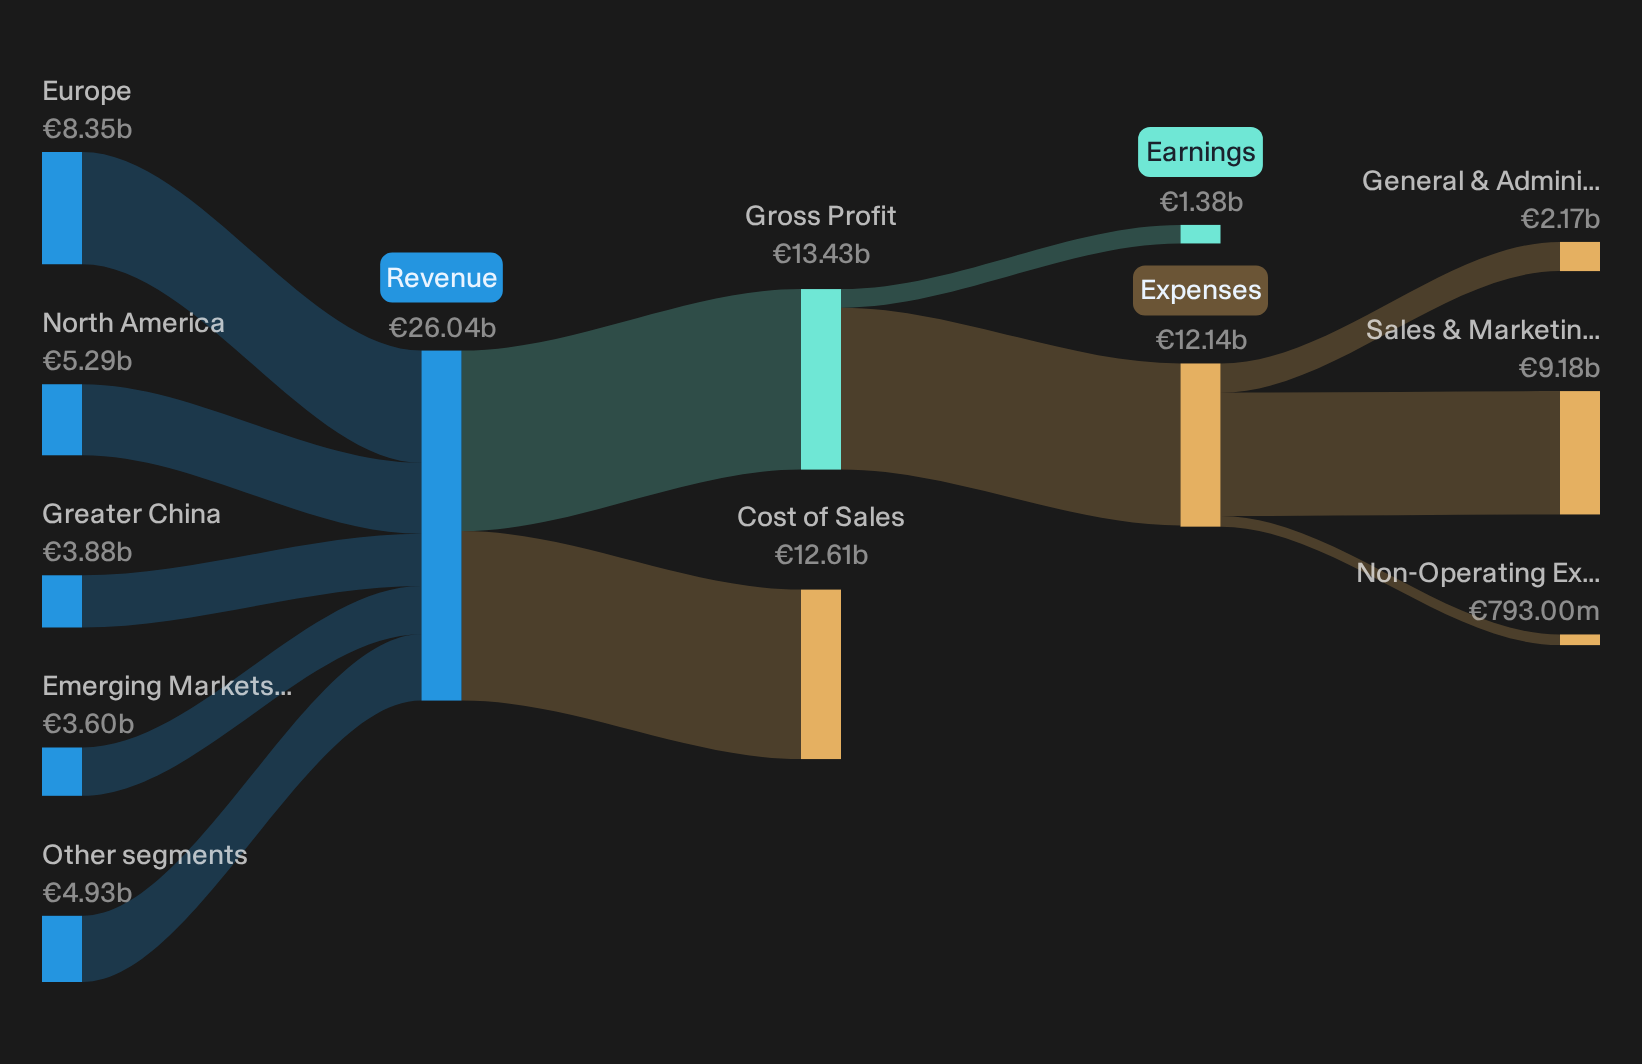
Operations: adidas generates about €8.4b in Europe, €5.3b in North America, €3.9b in Greater China, and €3.6b in Emerging Markets.
Market Cap: €24.7b
For youth focused footwear and athleisure, adidas matters because its sneaker lines, social media presence, and World Cup style campaigns directly shape what younger consumers want to wear.
The ongoing shift to direct-to-consumer e-commerce and retail channels (+9% e-commerce, +9% brick & mortar, continued D2C expansion) is improving adidas' control over branding, driving higher-margin sales, and strengthening customer data utilization, which will gradually enhance net and gross margins as the channel mix evolves.
The real test for adidas now is how one unresolved pressure on pricing power and promotion in youth heavy markets ultimately plays out.
That pricing squeeze is exactly what the full narrative for adidas unpacks, revealing where adidas youth demand could be accelerating, stalling, or quietly decoupling from headline sentiment.
Curious About Alternative Stock Themes?
Momentum shifts fast and the next breakout ideas rarely stay under the radar for long. Scan fresh opportunities before the crowd, while it matters, and look for ways to gain exposure early.
- Explore steady compounding potential by reviewing a curated list of solid balance sheet and fundamentals (23 results) that can help you avoid fragile stories and focus on sturdier foundations.
- Consider structural trends in critical materials by checking a hand picked 17 top copper producer stocks connected to electrification and long term infrastructure demand.
- Review resilient income ideas by scanning a focused 7 dividend fortresses built around high yields that could matter when markets start dropping again.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com