
How Autonomous Vehicle Partnership Will Impact Lucid Stock (LCID)
- Lucid Group has partnered with Bolt to co-develop SAE Level 4 autonomous mobility services in Europe, targeting deployment of at least 25,000 ADS ready vehicles built on Lucid's upcoming midsize platform using NVIDIA Hyperion architecture.
- The deal pushes Lucid Group deeper into a fleet and software centric revenue model, with Lucid Technologies positioned to commercialize autonomy, data, and digital features alongside Bolt's owned and operated robotaxi network.
- We will now assess how Lucid Group's Bolt backed plan to deploy 25,000 autonomous vehicles could reshape its broader investment narrative.
Scan Lucid Group's move into autonomous fleets alongside a curated group of potential peers by reviewing 95 robotics and automation stocks that are building the hardware and software backbone for self driving mobility.
Lucid Group Investment Narrative Recap
To own Lucid Group, you need to believe the business can turn strong technology and platform partnerships into a healthier manufacturing and software operation before funding pressure bites. The Bolt deal tilts the story further toward fleet and autonomy, but it does not change the near term reality of deep losses and heavy cash needs.
The most important short term catalyst remains execution on vehicle ramp and cost discipline, because gross margins have been deeply negative and cash runway is under a year. The biggest risk stays the same. Persistent losses may keep forcing external capital raises, which brings dilution and higher funding costs.
The Bolt partnership links directly to Lucid Group’s existing focus on autonomous fleets through the earlier Uber and Nuro arrangement around Lucid Gravity robotaxis. Together, these agreements point to a business model that leans more on high volume fleet deployments and software or technology monetisation rather than purely on premium retail sales.
For you, the operational question is whether management can actually deliver midsize platform vehicles, integrate NVIDIA Hyperion, and support thousands of Level 4 capable units while still fixing gross margins. If volumes slip, or if autonomy rollouts are slower than partners plan, the funding strain and share dilution risk do not go away.
Lucid Group's analyst narrative points to US$7.2b in revenue and US$167.8m in earnings by 2029, built on a forecast 72.3% yearly revenue growth rate and a move from a current loss of US$4.1b to the projected profit, which is an earnings swing of about US$4.3b.
Uncover why Lucid Group's fair value indicates a 105% potential upside to its current price that could close more quickly than many investors expect.
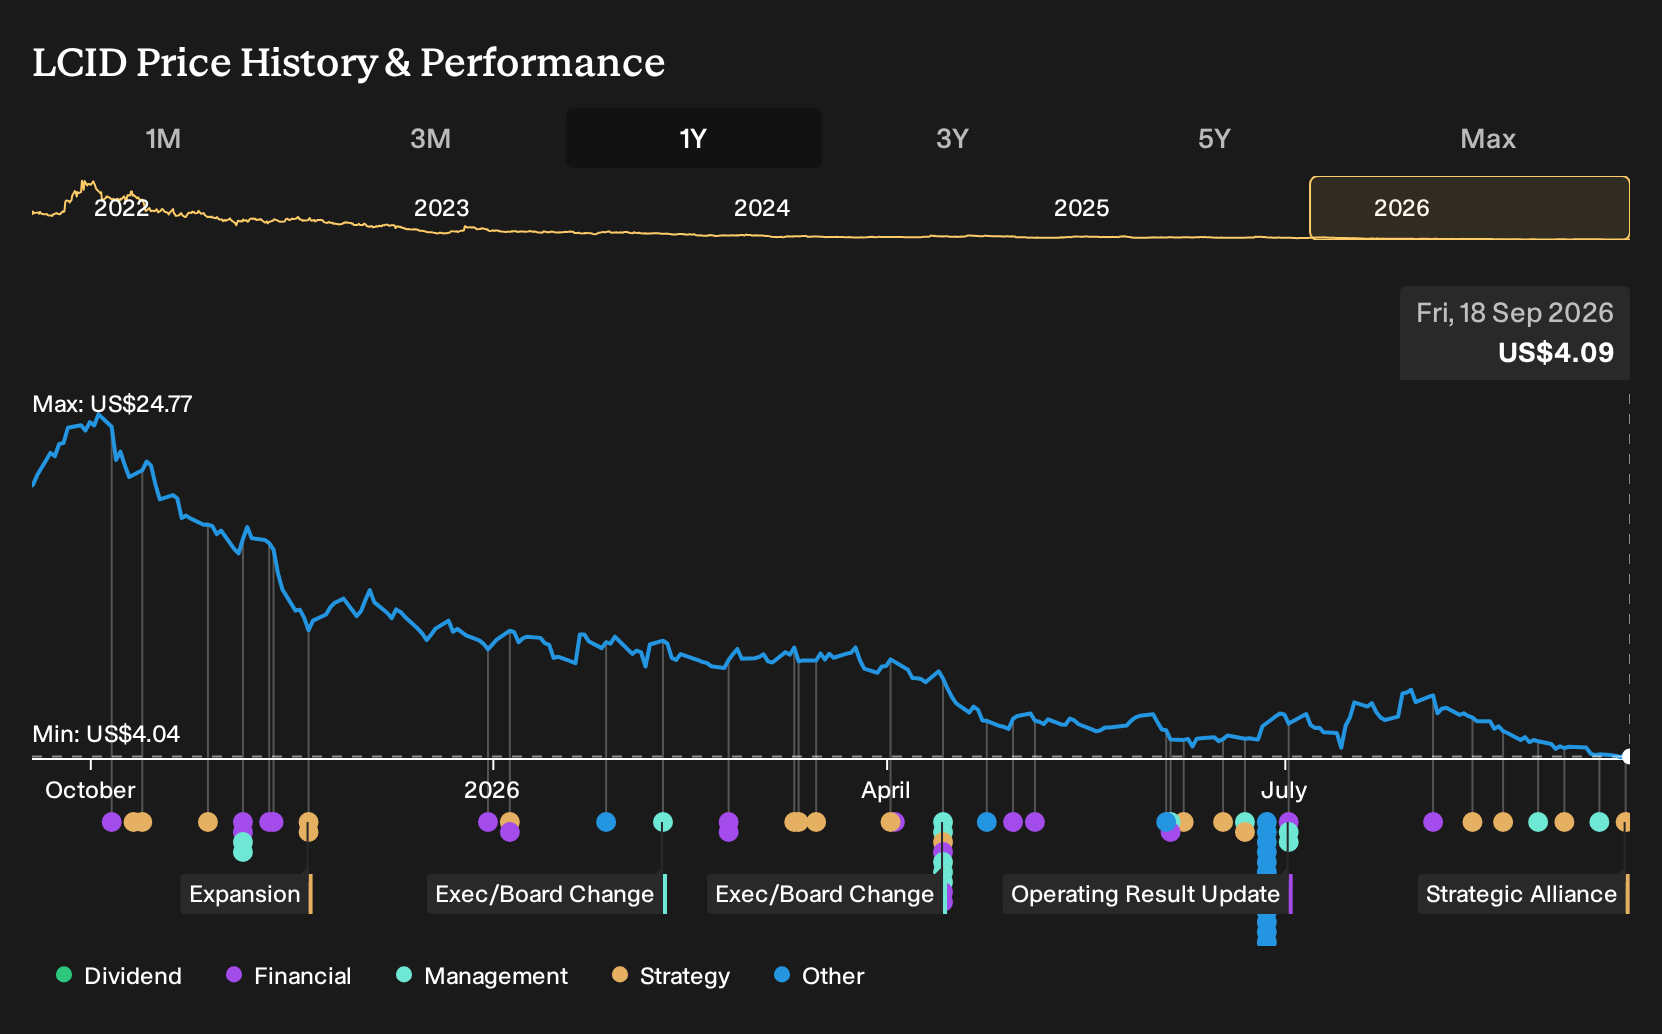
Exploring Other Perspectives
One alternate view focuses on weak demand risk rather than autonomy upside. The most bearish analysts were pencilling in revenue of about US$4.3b and earnings of roughly US$98.6m by 2029 for Lucid Group, well below consensus. Those estimates were set before this Bolt partnership, so expectations on both sides may shift as details sink in.
Explore 3 other Lucid Group fair value estimates, including one that suggests it could be worth just $5.00!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Lucid Group research is our analysis highlighting 1 key reward and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Lucid Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lucid Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Lucid Group?
If Lucid Group's autonomy and fleet story has you rethinking where you want exposure, it can help to line it up against other companies with different strengths, risk profiles, and balance sheet setups using the Simply Wall St Screener.
- For investors who want quality at a discount, scan a curated set of potential bargains through the 33 high quality undervalued stocks that match strong fundamentals with appealing pricing.
- If capital preservation matters just as much as upside, filter for steadier businesses using the 30 resilient stocks with low risk scores that prioritises resilient financial profiles and lower risk scores.
- When you want sturdier finances behind any growth story, focus on companies with robust funding positions using the list of solid balance sheet and fundamentals (23 results) to narrow in on stronger balance sheets and underlying fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com