
Will Free FHA Access Change Fair Isaac (FICO) Stock Narrative
- Fair Isaac announced that FICO Score 10T, which uses trended and rental data and is described as the most predictive mortgage score, became approved for FHA lenders and is scheduled for no cost availability alongside Classic FICO from January 1, 2027.
- The decision to offer FICO Score 10T for free to FHA lenders directly targets first-time homebuyers with lower down payments. It also responds to pressure on Fair Isaac related to competition, regulation, and the value of its scoring models.
- We will now assess how Fair Isaac's investment narrative could be influenced by FICO Score 10T's upcoming free availability to FHA lenders.
Scan how Fair Isaac's mortgage scoring pivot compares with other credit and risk analytics specialists by reviewing the hand picked list of solid balance sheet and fundamentals (23 results) that could benefit from similar adoption trends.
Fair Isaac Investment Narrative Recap
To own Fair Isaac, you need to believe its credit scoring moat and higher margin software engine both keep pulling their weight, even as regulation and rivals push hard. The big operational swing factor right now is how fast lenders shift to FICO Score 10T and newer tools, and whether software growth, which recently slowed, regains momentum.
The FHA decision to make FICO Score 10T available at no cost looks important for near term adoption optics but does not instantly change the biggest risk. Competitive and regulatory pressure around lender choice, VantageScore, and alternative data still hangs over pricing power and mortgage score share.
The clearest recent announcement that ties into this is the downward revision of Fair Isaac’s fair value estimate from US$1,512.25 to US$1,440.16. That reset explicitly folded in concerns about regulatory scrutiny, VantageScore competition, mortgage share questions, and the Direct Licensing Program.
Seen alongside the free FHA rollout of FICO Score 10T, that earlier revision frames the current setup. Product adoption and SaaS platform progress sit on one side of the scale. On the other side are execution on software bookings, cost pressures, and whether Fair Isaac can keep its scoring economics resilient as lender choice expands.
What The FHA Shift Means Against Long Term Fair Isaac Assumptions
Fair Isaac now sits on a mortgage scoring decision that lines up directly against the analyst model already on file. The free rollout of FICO Score 10T for FHA lenders speaks to adoption and mix, while the consensus numbers anchor on how the whole business might look by the late 2020s.
Those projections assume Fair Isaac can keep revenue climbing at 13.8% a year over the next three years, with profit margins moving from 34.1% today to 36.7% by year three. Analysts also see earnings today at US$815.0 million and point to a consensus earnings figure of US$1.3b by 2029, which implies an earnings increase of about US$485 million from current levels. The same 2029 framework calls for Fair Isaac to be running US$3.5b of revenue with that US$1.3b earnings number in place, using 2029 as the anchor year for those estimates.
Fair Isaac's narrative projects US$3.5b revenue and US$1.3b earnings by 2029. This assumes 13.8% yearly revenue growth and an earnings increase of about US$485 million from US$815.0 million today.
Uncover why Fair Isaac's fair value indicates a 52% potential upside to its current price that may not last much longer.
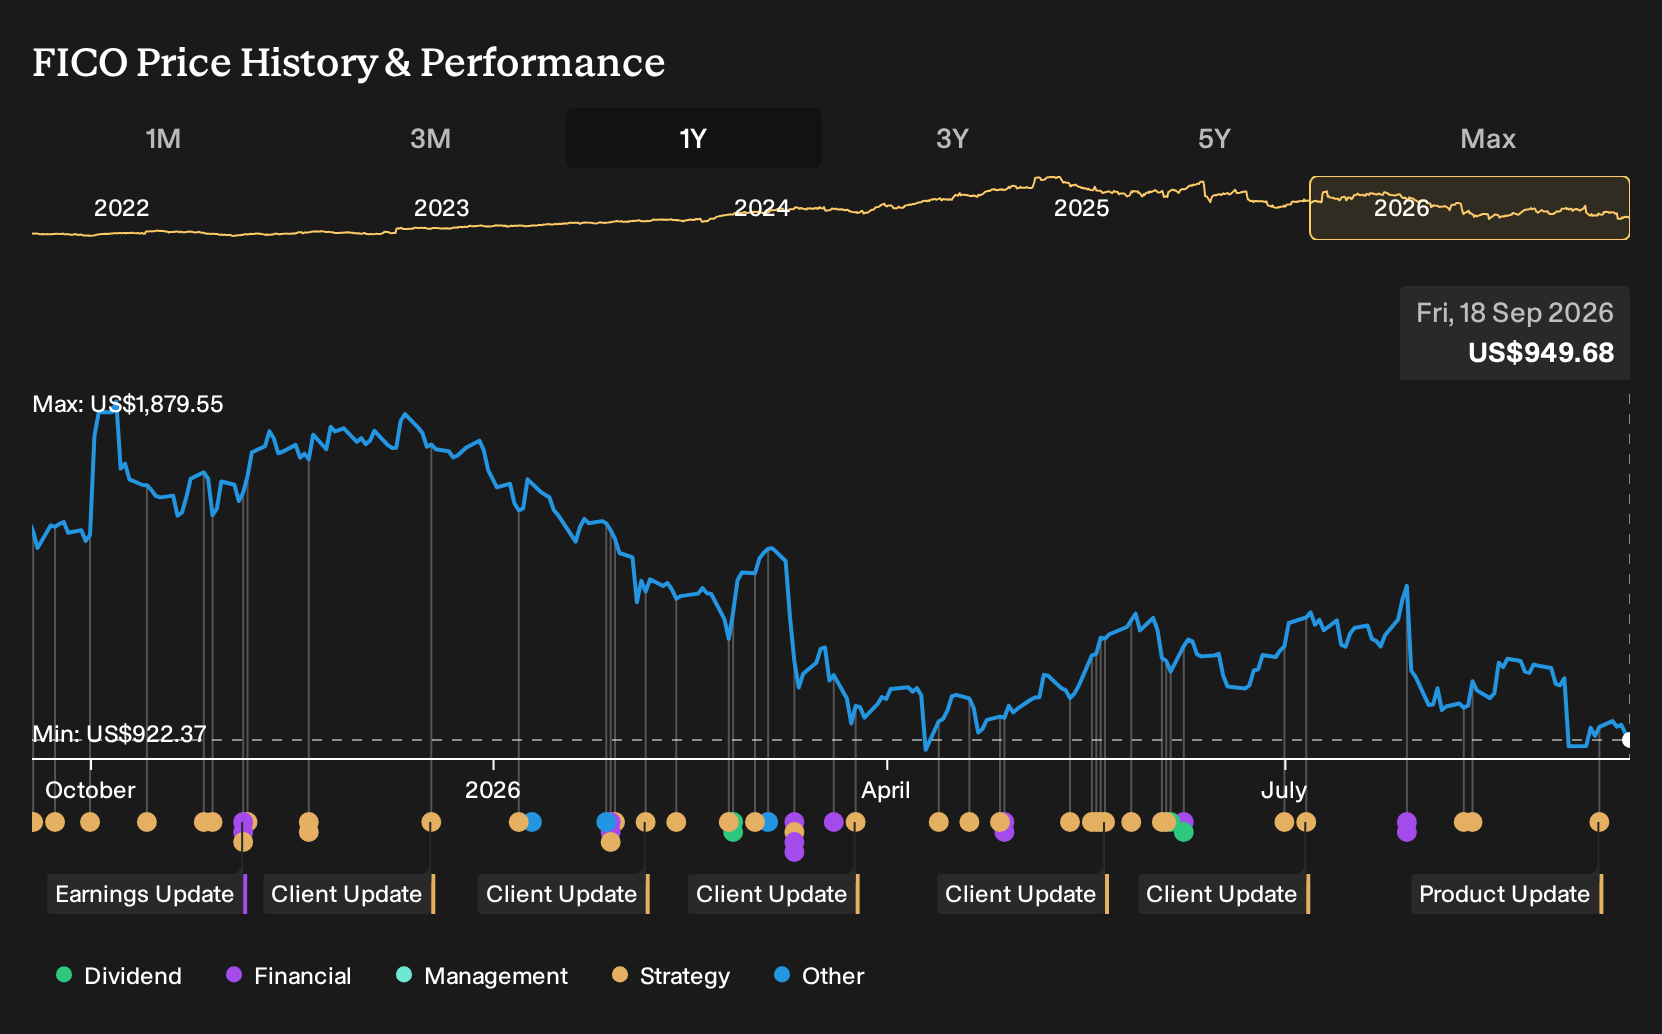
Exploring Other Perspectives
One alternate view on Fair Isaac leans hard into regulatory risk. The most bearish analysts were already penciling in slower revenue progress at about US$3.3b by 2029 and a much lower implied P/E of 17.6x before this FHA news. That is a far more cautious story. Treat this announcement as a chance to compare those pre news assumptions with your own and explore how opinions might shift.
Explore 4 other Fair Isaac fair value estimates, including one that suggests it could be worth just $1440!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Fair Isaac research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Fair Isaac. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Fair Isaac's overall financial health at a glance.
Looking For More Ideas Beyond Fair Isaac?
If you want to put Fair Isaac in context, it helps to scan a wider field of opportunities. Use the Simply Wall St Screener to line up businesses by quality, balance sheet strength, or income potential so you can compare like for like and build a watchlist that reflects your own style.
- If resilience is your priority, start with companies that pair stronger fundamentals with sturdier finances through the 30 resilient stocks with low risk scores.
- For investors hunting for mispriced quality, line up businesses that blend solid cash flows with attractive valuations using the 35 high quality undervalued stocks.
- If income is central to your plan, focus on stocks offering higher yields that still look supported by their fundamentals via the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com