
Pennant Group (PNTG) Could Be 14% Undervalued On Mainplace Real Estate Purchase
Why Pennant Group’s latest real estate move matters
Pennant Group (PNTG) recently acquired the real estate of Mainplace Senior Living in Orange, California, shifting from a triple net lease to ownership of a community it has operated since 2019.
Pennant Group’s share price has climbed 42.36% year to date to US$39.62, with a 90 day share price return of 17.81% pointing to building momentum around its story. The 1 year total shareholder return of 64.26% and 3 year total shareholder return of 247.54% show how strongly long term holders have been rewarded as moves like the Mainplace real estate purchase reshape expectations around growth prospects and risk.
Scan for other healthcare operators quietly building value through real estate moves with the curated list of solid balance sheet and fundamentals (23 results) that echo Pennant Group’s focus on stability and disciplined capital deployment.
The Mainplace purchase could reflect deeper confidence in Pennant Group’s operating engine, or it could highlight investors warming to the story. The valuation work starts by asking which of those forces is really driving the price.
Most Popular Narrative: 14.5% Undervalued
Against a last close of $39.62, the most followed narrative for Pennant Group pegs fair value at about $46.33, implying the market is pricing its future cash flows below that storyline.
The accelerating demographic shift of an aging U.S. population is leading to rising demand for home health, hospice, and senior living services, as evidenced by Pennant's strong organic and acquisition-driven volume growth and robust occupancy/pricing trends in senior living. This ongoing demographic wave is likely to continue expanding Pennant's addressable market and may support durable, long-term revenue growth.
See why 6 investors see Pennant Group as 14% undervalued.
Result: Fair Value of $46.33 (UNDERVALUED)
Still, the Pennant Group story depends heavily on Medicare and Medicaid reimbursement. Any tougher 2026 home health rule or wage inflation could quickly pressure that upbeat narrative.
Find out about the key risks to this Pennant Group narrative.
Another view on Pennant Group’s valuation
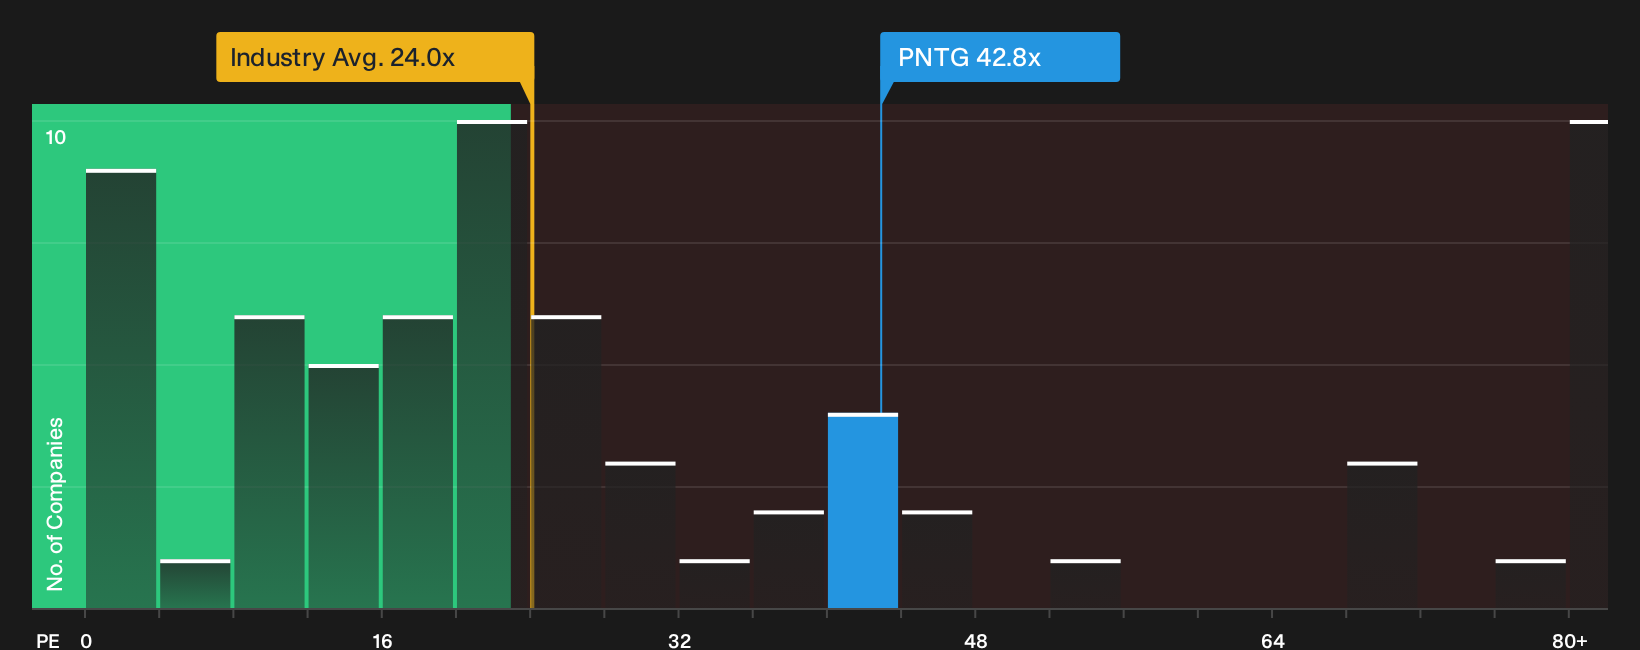
Pennant Group may look 14.5% undervalued on the popular fair value narrative at $46.33, yet the P/E picture paints a very different story. The shares trade on roughly 42.8x earnings versus a fair ratio of 29.8x and a US Healthcare industry average around 24x.
That leaves Pennant Group priced richer than both peers and the fair ratio that the market could move toward over time, which raises the question: Is the gap a sign of optimism that still needs to be earned, or a premium investors are comfortable paying for its recent execution and growth profile?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the Pennant Group story so far feels mixed, use that tension as a prompt to move quickly and analyze the numbers yourself. Start by weighing the 3 key rewards and 1 important warning sign
Looking for more Pennant Group style investment ideas?
Do not stop at Pennant Group. The same tools that helped surface this story can help you quickly spot other opportunities that fit your goals before the crowd notices.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (23 results) that keep financial risk in check.
- Hunt for quality at a reasonable price by using the 35 high quality undervalued stocks that could align with value focused criteria.
- Spot strong businesses hiding in plain sight by working through the 16 high quality undiscovered gems before they attract wider attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com