
3 Japanese Undervalued Stocks To Watch In September 2026
Bond yields around the world have climbed to multi decade highs as governments respond to inflation, higher borrowing needs and geopolitical stress. Higher discount rates can pressure share prices, which sometimes pushes Japanese companies with solid cash generation below their estimated fair value. That gap is where value hunters look. This article highlights three Japanese stocks screened for strong cash flow support that currently trade at a discount to analyst DCF estimates.
The three stocks below are only a sample, since the full screen surfaced 36 more companies with equally cash rich stories that are not covered here and may warrant a closer look for patient value hunters. To identify and analyze those extra candidates with discounted cash flow support, head straight into the Undervalued Stocks Based On Cash Flows screener.
Canon (TSE:7751)
Canon is a global equipment maker that spans office printers, commercial production printers, cameras, medical scanners, and industrial tools, with its office and large format printing ecosystem generating recurring cash from hardware, consumables, and service contracts. The group is sizeable, with a market value of about ¥3.82t.
Canon trades at about a 35.4% discount to an internal DCF estimate and around 11x P/E compared with a peer average near 20x. Its print hardware plus consumables model supports recurring cash flow and recent H1 2026 net income of ¥171,184 million. That combination of discounted cash flows and recurring print economics could look very different if a single assumption about customer print volumes shifts over the next few years.
If that print volume swing is what you care about, start with the DCF valuation analysis for Canon to see how sensitive Canon's valuation is to small demand shifts.
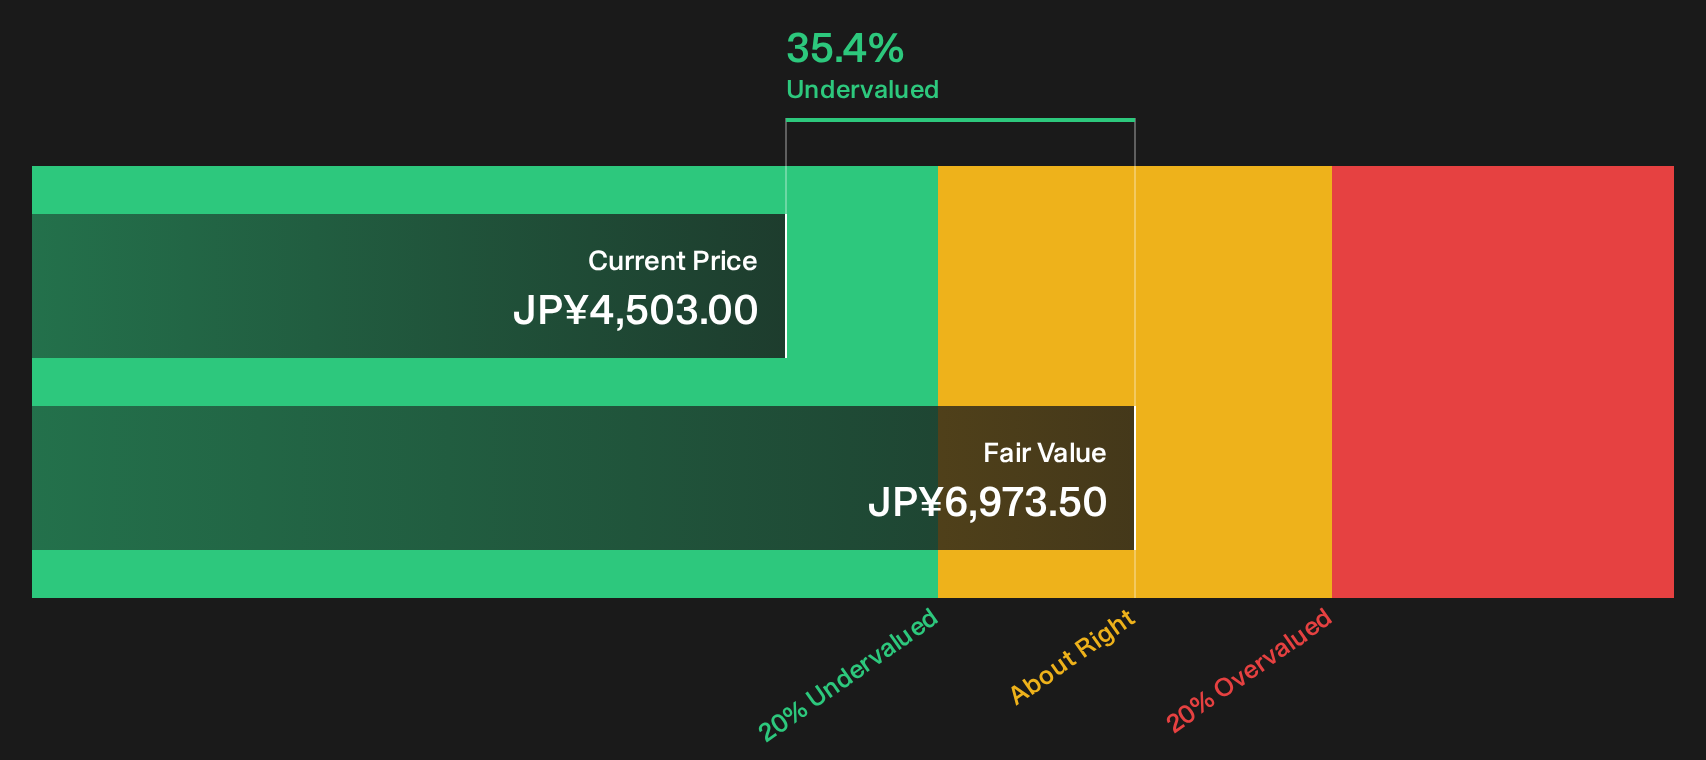
Astellas Pharma (TSE:4503)
Astellas Pharma runs a broad prescription drug portfolio across oncology, ophthalmology, urology, immunology, and women's health, with its marketed cancer treatments such as XTANDI, XOSPATA, and PADCEV creating recurring cash flows that tie directly to the undervalued cash flow theme. The group reports about ¥2,274.4b in pharmaceutical revenue and carries a market value near ¥4,273.6b.
Astellas Pharma brings a different angle to this cash flow screen. Oncology brands already on the market generate meaningful repeat prescriptions, and a deep late stage pipeline helps shape expectations for what that cash stream might look like a few years from now.
Pipeline momentum is accelerating through near-term clinical readouts and global expansion opportunities in oncology and rare diseases. A diversified approach (including targeted protein degradation, Claudin 18.2 assets, and ADCs) provides greater earnings visibility and premium pricing opportunities for future revenue.
The real swing factor is how one pressure on future pricing plays out against that growing base of cash generative cancer drugs.
That pricing overhang is where things get interesting, so read the full narrative for Astellas Pharma to see how Astellas Pharma’s cash engine could decouple from market worries.

Terumo (TSE:4543)
Terumo is a ¥3.30t medical equipment group whose appeal for this cash flow screen comes from recurring consumable sales in Medical Care Solutions and Cardiac & Vascular, which together generated about ¥929b of the roughly ¥1.18t segment total in the latest breakdown.
For Terumo, the cash flow story hinges on repeat-use devices and consumables in hospitals, and the most interesting shifts are happening where volume growth, pricing power, and new technologies intersect.
Expansion of sales channels and volume commitments in China, especially in Neurovascular products, has enabled Terumo to gain market share and increase prices, counteracting typical negative VBP effects in this key emerging market.
What investors really need to watch is how one quiet change in the pricing and mix of those high repeat-use products filters through to long run margins.
That quiet shift in pricing power is only the surface, and the full narrative for Terumo shows how Terumo's recurring devices story could accelerate beyond current expectations.

Seeking Fresh Alternatives Before They Fly
Market momentum shifts fast and the stocks that look quiet today can become tomorrow's breakout stories before most investors even notice. Scan fresh ideas while it matters and get in early.
- Spot income workhorses with staying power by reviewing the 14 dividend fortresses and see which high yield payers could help anchor a long term portfolio.
- Track early AI momentum where profits already matter by using the curated 38 profitable AI stocks that aren't just burning cash before these cash generative stories stop flying under the radar.
- Target resilient balance sheets that can handle shocks by scanning the hand picked list of solid balance sheet and fundamentals (21 results) and avoid being caught holding weak financials when sentiment drops.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com