
Illinois Tool Works (ITW) Could Be 11% Undervalued As Q2 Earnings Beat Expectations
Illinois Tool Works (ITW) just paired a solid earnings print with a regulatory footnote that matters more than it looks at first glance. Q2 results topped forecasts, and the latest hazardous materials permit update adds another angle for investors to watch.
Over the past year, Illinois Tool Works has moved in steps rather than leaps, with a 7.98% year to date share price return and a 5.49% 1 year total shareholder return that point to steady but not runaway momentum.
Compare Illinois Tool Works' steady execution with other industrial players by scanning our hand picked list of list of solid balance sheet and fundamentals (23 results)
After a strong Q2 print and a modest pullback, Illinois Tool Works now presents a cleaner mix of solid execution and regulatory clarity. Does that recent wobble still leave the risk reward skewed toward buyers, or not?
Most Popular Narrative: 11% Undervalued
Illinois Tool Works closed at $269.42, against a widely followed fair value estimate of $302.50, which leaves a valuation gap that hinges on how much faith you put in its long term earnings profile and capital return plans.
ITW is focusing on above market organic growth through customer backed innovation, aiming to enhance revenue by offering differentiated products and services across its diversified portfolio. The company’s 90% plus produce where we sell manufacturing strategy mitigates tariff impacts, which could help maintain or improve net margins by reducing costs associated with tariffs.
See why 44 investors see Illinois Tool Works as 11% undervalued.
Result: Fair Value of $302.50 (UNDERVALUED)
Still, the narrative around Illinois Tool Works can crack if segment softness in areas like Construction or Test & Measurement persists and begins to drag on margins and earnings expectations.
Find out about the key risks to this Illinois Tool Works narrative.
Another View on Illinois Tool Works Valuation
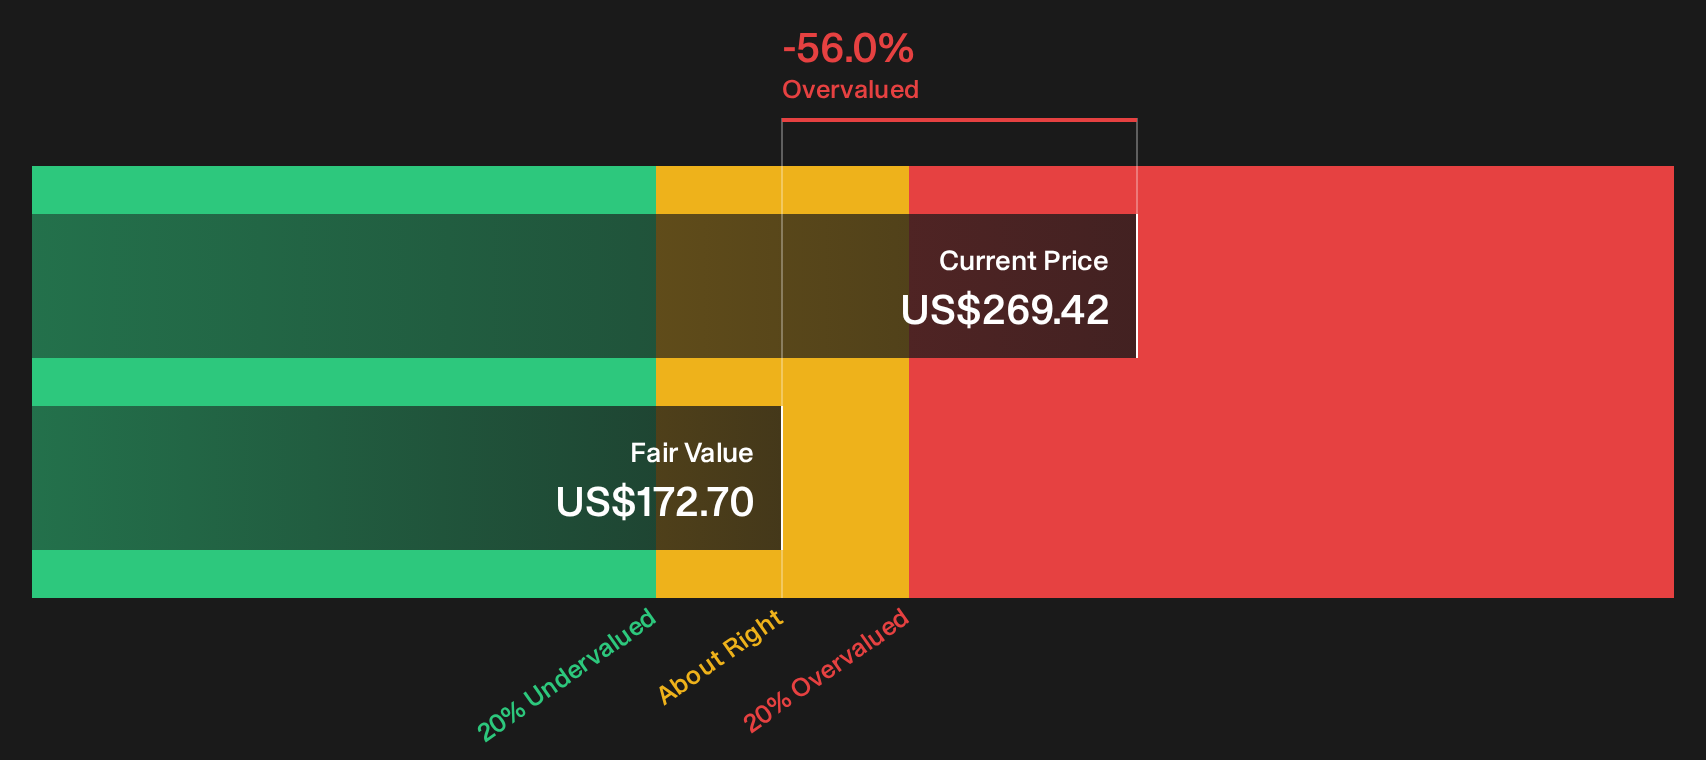
The fair value story for Illinois Tool Works looks less one sided when you bring in the SWS DCF model. On this view, ITW at $269.42 trades well above an estimated future cash flow value of $172.70, which points to the shares screening as overvalued on a pure cash flow basis.
The gap between a DCF value near $172 and an analyst fair value of $302.50 gives you two very different anchors. It raises a simple question. Do you trust the market to keep rewarding earnings resilience, or do you lean toward the cash flow math that flags less room for error?
To see how that cash flow approach is built and where the sensitivities sit, Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Illinois Tool Works for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around valuation and regulation can blur the picture for Illinois Tool Works, so move quickly, inspect the numbers for yourself, and weigh the 4 key rewards and 1 important warning sign
Looking for more Illinois Tool Works style investment ideas?
If Illinois Tool Works has sharpened your focus on quality and price, do not stop here. Use the Simply Wall Street Screener to uncover fresh opportunities across income, quality and value.
- Target reliable income streams by reviewing companies that screen as potential 7 dividend fortresses for yield focused portfolios.
- Spot potential bargains early by scanning a curated 16 high quality undiscovered gems before they appear on everyone else's radar.
- Prioritize resilience by filtering for 30 resilient stocks with low risk scores that may help steady your portfolio when volatility spikes.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com