
China Longyuan Power Group (SEHK:916) Gains On August Solar Strength But Is The Value Case Priced In
China Longyuan Power Group (SEHK:916) just reported August 2026 operating data, with total power generation up 6.35% year on year and solar output advancing 20.67%, even as cumulative 2026 volumes remain slightly lower.
For context, China Longyuan Power Group’s 1-day share price return of 2.42% to HK$5.285 comes after a year to date share price decline of 21.82% and a 1-year total shareholder return that is down 29%. This suggests recent operational updates may be starting to stabilise sentiment after a tougher stretch for longer term holders.
Scan beyond China Longyuan Power Group and compare this operational rebound with 39 power grid technology and infrastructure stocks that may be poised to benefit from similar transmission and renewable build outs.
China Longyuan Power Group now trades well below both recent levels and the average analyst target, so where might fair value actually sit once those estimates and the latest rebound are put side by side?
Price-to-Earnings of 10.3x: Is it justified?
On simple earnings terms, China Longyuan Power Group trades on a P/E of 10.3x, which sits below both the Hong Kong market and key renewable peers while the share price remains at HK$5.285.
The P/E ratio compares what investors are paying for each dollar of earnings, so a lower multiple can point to either a discount or weaker confidence in the profit outlook for a utility and renewable operator like this.
Here, the stock is priced below the Hong Kong market P/E of 10.8x, below the Asian renewable energy average of 14.6x, and below an estimated fair P/E of 13.6x. This indicates the market is assigning a meaningfully lower tag than both peers and that fair ratio level could be where sentiment eventually heads.
Explore the SWS fair ratio for China Longyuan Power Group.
Result: Price-to-Earnings of 10.3x (UNDERVALUED)
Still, the long slide in China Longyuan Power Group’s 1-year and 5-year returns, along with its large parent ownership, could keep sentiment fragile if expectations shift.
Find out about the key risks to this China Longyuan Power Group narrative.
Another View Using The SWS DCF Model
China Longyuan Power Group looks inexpensive on a 10.3x P/E, yet the SWS DCF model points the other way. At HK$5.29, the shares are above an estimated future cash flow value of HK$3.77, which flags potential overvaluation on this lens. Which signal do you trust more?
For a closer look at how those cash flow assumptions are built and what would need to change for that gap to close, Look into how the SWS DCF model arrives at its fair value.
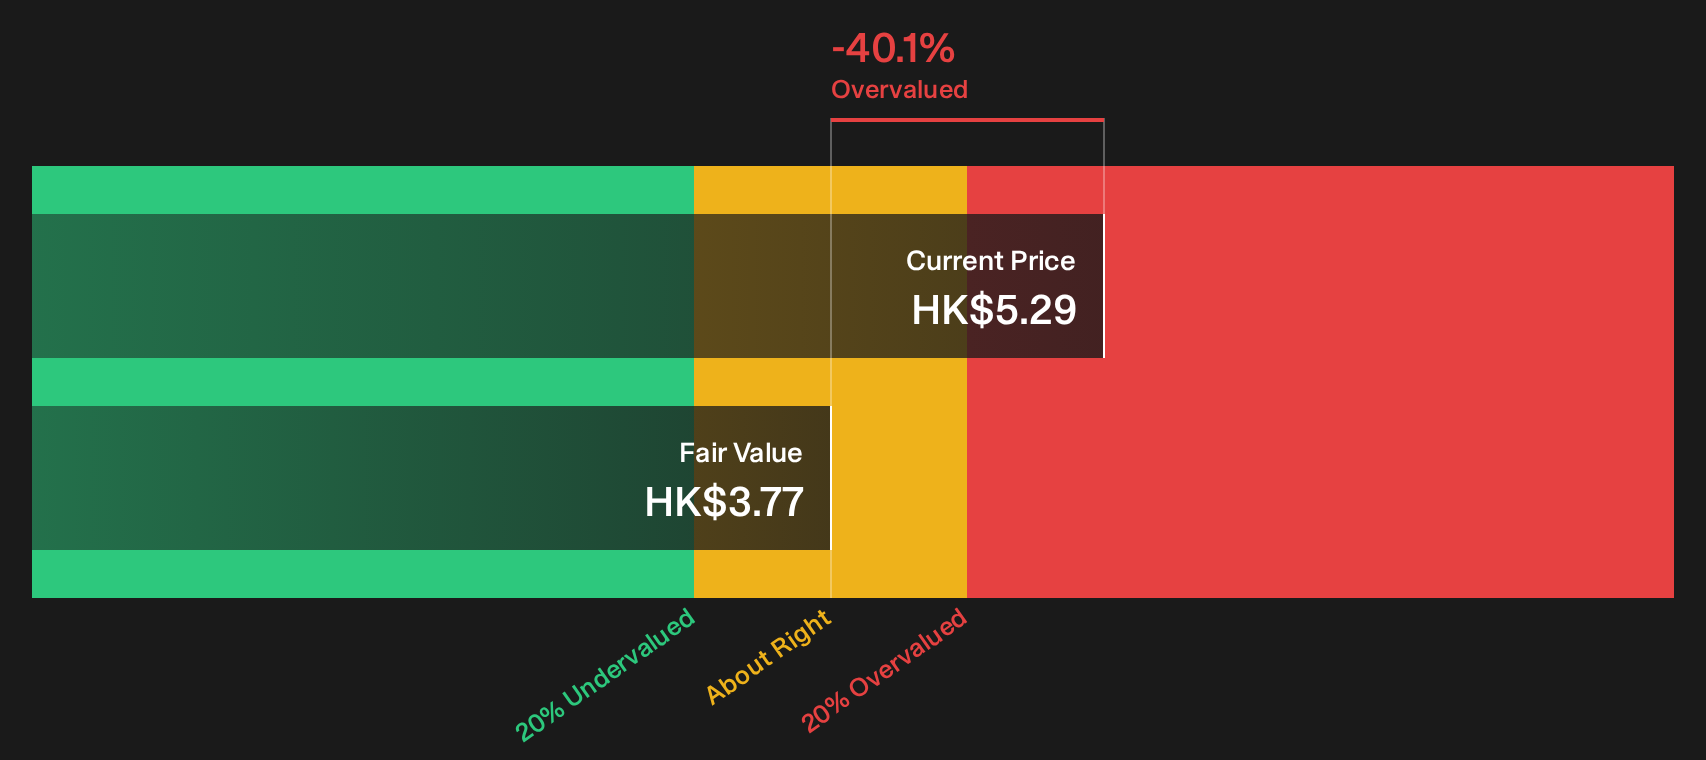
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out China Longyuan Power Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 182 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on China Longyuan Power Group so far. If you want your own take before the market moves on, start with the 4 key rewards and 2 important warning signs
Looking for more investment ideas beyond China Longyuan Power Group?
If China Longyuan Power Group has you thinking harder about value and risk, do not stop at just one stock. Broader idea hunting can sharpen every decision you make.
Use the Simply Wall Street screener to quickly pressure test what “quality” and “value” look like across different sectors and risk profiles before you commit fresh capital.
- Zero in on potential bargains that combine solid fundamentals with discounted pricing by scanning our 182 high quality undervalued stocks.
- Strengthen your income game by focusing on companies built to sustain meaningful payouts through our 157 dividend fortresses.
- Dial down portfolio stress by concentrating on financially resilient businesses screened within the 226 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com