
Earnings Beat Might Change The Case For Investing In Macy's Stock (M)
- Macy's reported second quarter 2026 revenue of US$5,059 million and net income of US$169 million, raised full year net sales guidance, and completed a US$976.18 million share repurchase program covering 17.08% of its shares.
- The combination of higher net sales guidance, expanding earnings per share from continuing operations, and an aggressive multi year buyback directly affects how investors may view Macy's earnings power per share.
- This article examines how Macy's long term investment narrative may be affected by the stronger guidance and the completed multi year repurchase.
Macy's Investment Narrative Recap
To own Macy's today, you need to believe the omni channel reset can keep translating into steady cash generation even if headline revenue is flat or drifting lower. Raised full year net sales guidance suggests management currently sees demand as manageable, which supports the near term earnings story. The main catalyst remains execution on store optimization and digital, which ties directly to how resilient margins look into 2027.
The biggest risk still sits with pressure on discretionary spending and ongoing mix shifts to pure online competitors. Any softening in unit demand or margin squeeze from tariffs and promotions could quickly blunt the recent EPS gains. The latest guidance tweak alone does not erase these structural pressures, so position sizing and time horizon matter.
The most relevant update here is the completed repurchase of 48,034,000 shares, or 17.08% of the company, for US$976.18 million. That reduction in share count means each remaining share now represents a larger claim on Macy's earnings and cash flows, which ties directly to how you think about per share value versus absolute profit.
For catalysts, that buyback matters only if the underlying retail engine holds up. Execution on omni channel, private label, and higher productivity stores is what will decide whether future EPS per share benefits from the smaller share base or stalls against e commerce and macro headwinds. Treat the repurchase as an amplifier of operating outcomes, not a substitute for them.
Macy's Long Term Forecasts and What They Imply
Macy's narrative projects US$20.7b revenue and US$664.5 million earnings by 2029. This assumes revenue declining 3.0% per year and earnings decreasing by US$2.5 million from US$667.0 million today.
Discover how Macy's fair value indicates a 4% potential upside to its current price that may not be available for long.
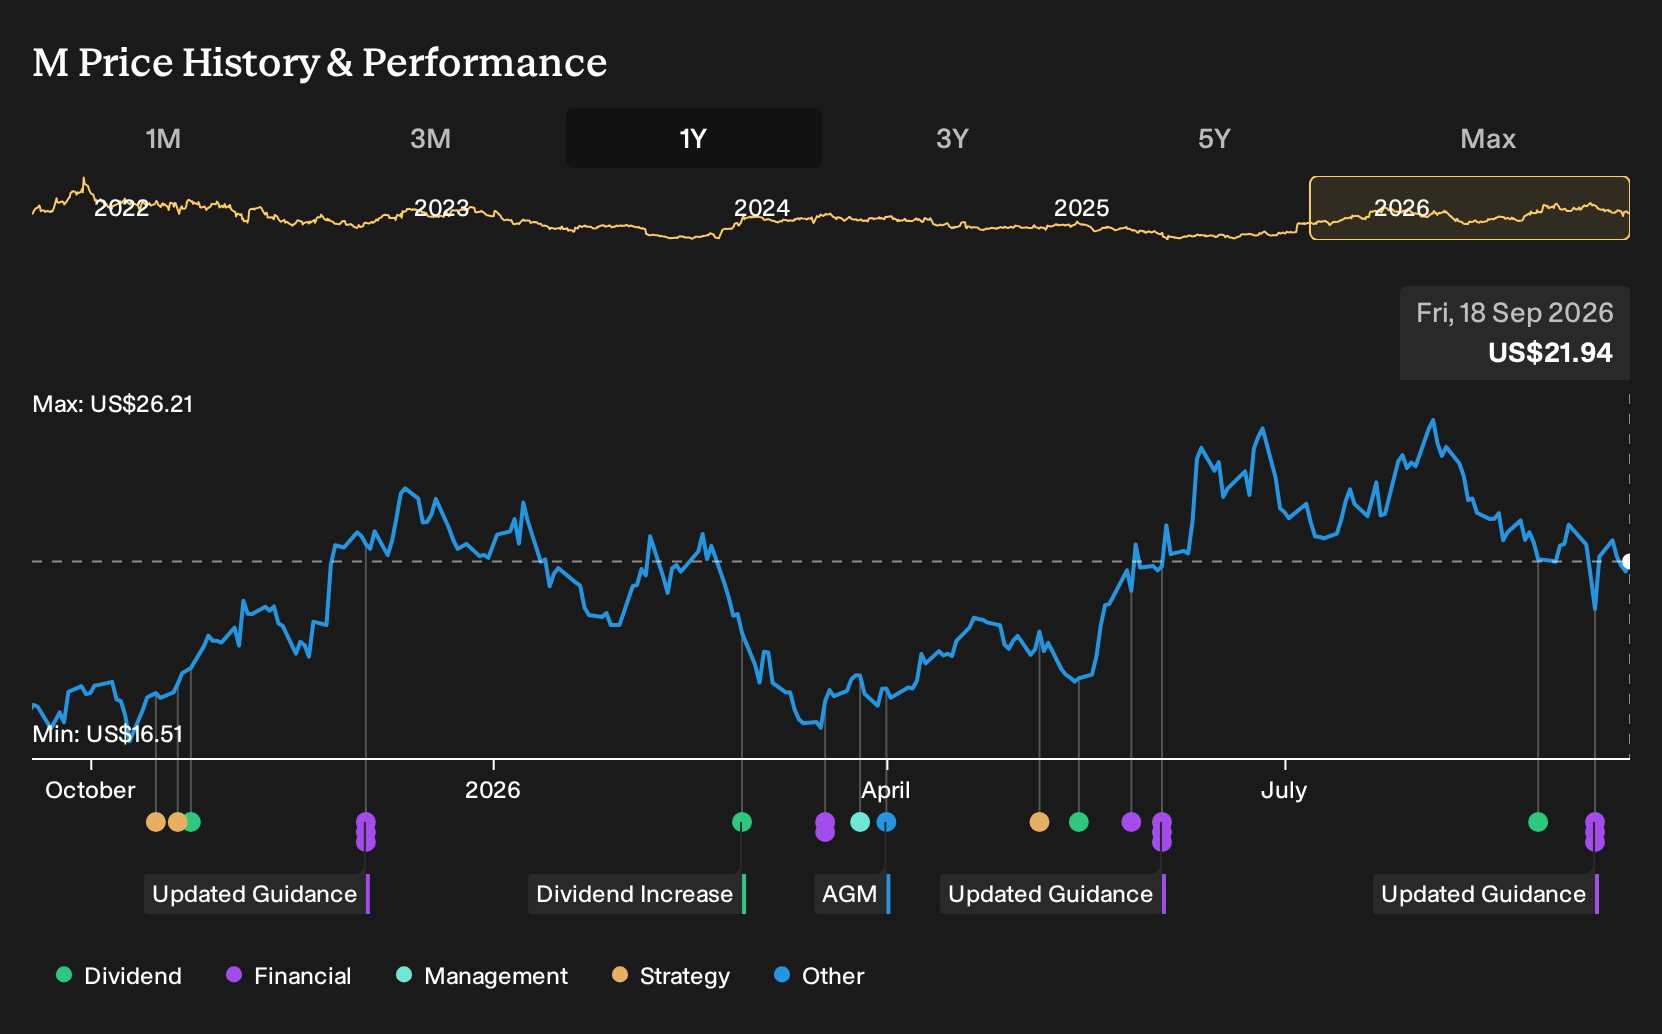
Exploring Other Perspectives
One alternate angle on Macy's focuses on the buyback as a bigger earnings accelerator than consensus assumes. The most optimistic analysts were already penciling in roughly flat revenue near US$22.6b and earnings of about US$660.0 million by 2029, before this updated guidance and completed repurchase. Opinions clearly vary. Explore several viewpoints before deciding how this fits your own thesis.
Explore 4 other Macy's fair value estimates, including one that suggests potential upside of as much as 344% from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own research and judgment.
- A great starting point for your Macy's research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Macy's. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Macy's overall financial health at a glance.
Looking For More Ideas Beyond Macy's?
If the Macy's story has you thinking about where else resilient cash generation and cleaner balance sheets might show up, it can help to widen the search across a broader watchlist of quality stocks. The Simply Wall St Screener gives you pre built sets of companies so you can quickly focus on the traits that matter most to your approach.
- For investors who care about value and quality together, start with companies flagged as having attractive fundamentals and pricing through the 35 high quality undervalued stocks.
- If capital preservation and steadier profiles come first for you, narrow your universe to businesses highlighted as having stronger financial footing by using the list of solid balance sheet and fundamentals (23 results).
- Income focused investors can zero in on higher yielding opportunities by reviewing the 7 dividend fortresses and seeing which payers line up with your risk tolerance and time horizon.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com