
Learn Why The Bull Case For Aecon Group Stock Could Change Following Canada Infrastructure Plan
- Canada previously set out a plan to attract C$1t of fresh capital into infrastructure and energy over five years, spotlighting Aecon Group as a focused contractor across civil, transportation, utilities, industrial, and nuclear projects.
- This policy driven investment push directly targets areas where Aecon Group already has execution capacity and backlog exposure, which ties potential project flow to the company’s existing operating strengths rather than untested new lines of business.
- We will now explore how Aecon Group's investment narrative could shift as Canada targets C$1t of infrastructure and energy capital.
Aecon Group Investment Narrative Recap
To own Aecon Group, you need to believe that record demand for energy transition and public works can translate into steadier earnings from its construction and concessions mix. The recent C$1t Canadian infrastructure and energy push directly aligns with Aecon Group's civil, utilities, nuclear, and transportation focus, but it does not remove execution risk on current projects or fixed commitments.
The near term swing factor is whether management can stabilise construction EBITDA margins after recent compression while keeping backlog quality high through collaborative contracts. The biggest current risk is that heavy reliance on public and utility work meets policy delays or labour shortages, which could slow backlog conversion and keep margins under pressure.
There have been no fresh company specific announcements tied to this Canadian capital plan, so the relevant reference point is Aecon Group's existing positioning. The business is already geared to public private partnerships and recurring style utilities and concessions work, which connects directly to grid, transit, and nuclear refurbishment demand highlighted in the C$1t ambition.
This matters for catalysts because Aecon Group has shifted 76% of its backlog into collaborative, non fixed price contracts and has been strengthening its balance sheet. That combination means any new awards linked to this policy drive are more likely to land in structures aimed at earnings stability. The key watch items remain labour availability, acquisition integration, and whether margins can recover from recent pressure.
Aecon Group's narrative projects CA$7.0b revenue and CA$214.5m earnings by 2029. This rests on 7.5% yearly revenue growth and an earnings increase of about CA$179m from CA$35.2m today.
Uncover why Aecon Group's fair value indicates a 19% potential upside to its current price, which could narrow quickly.
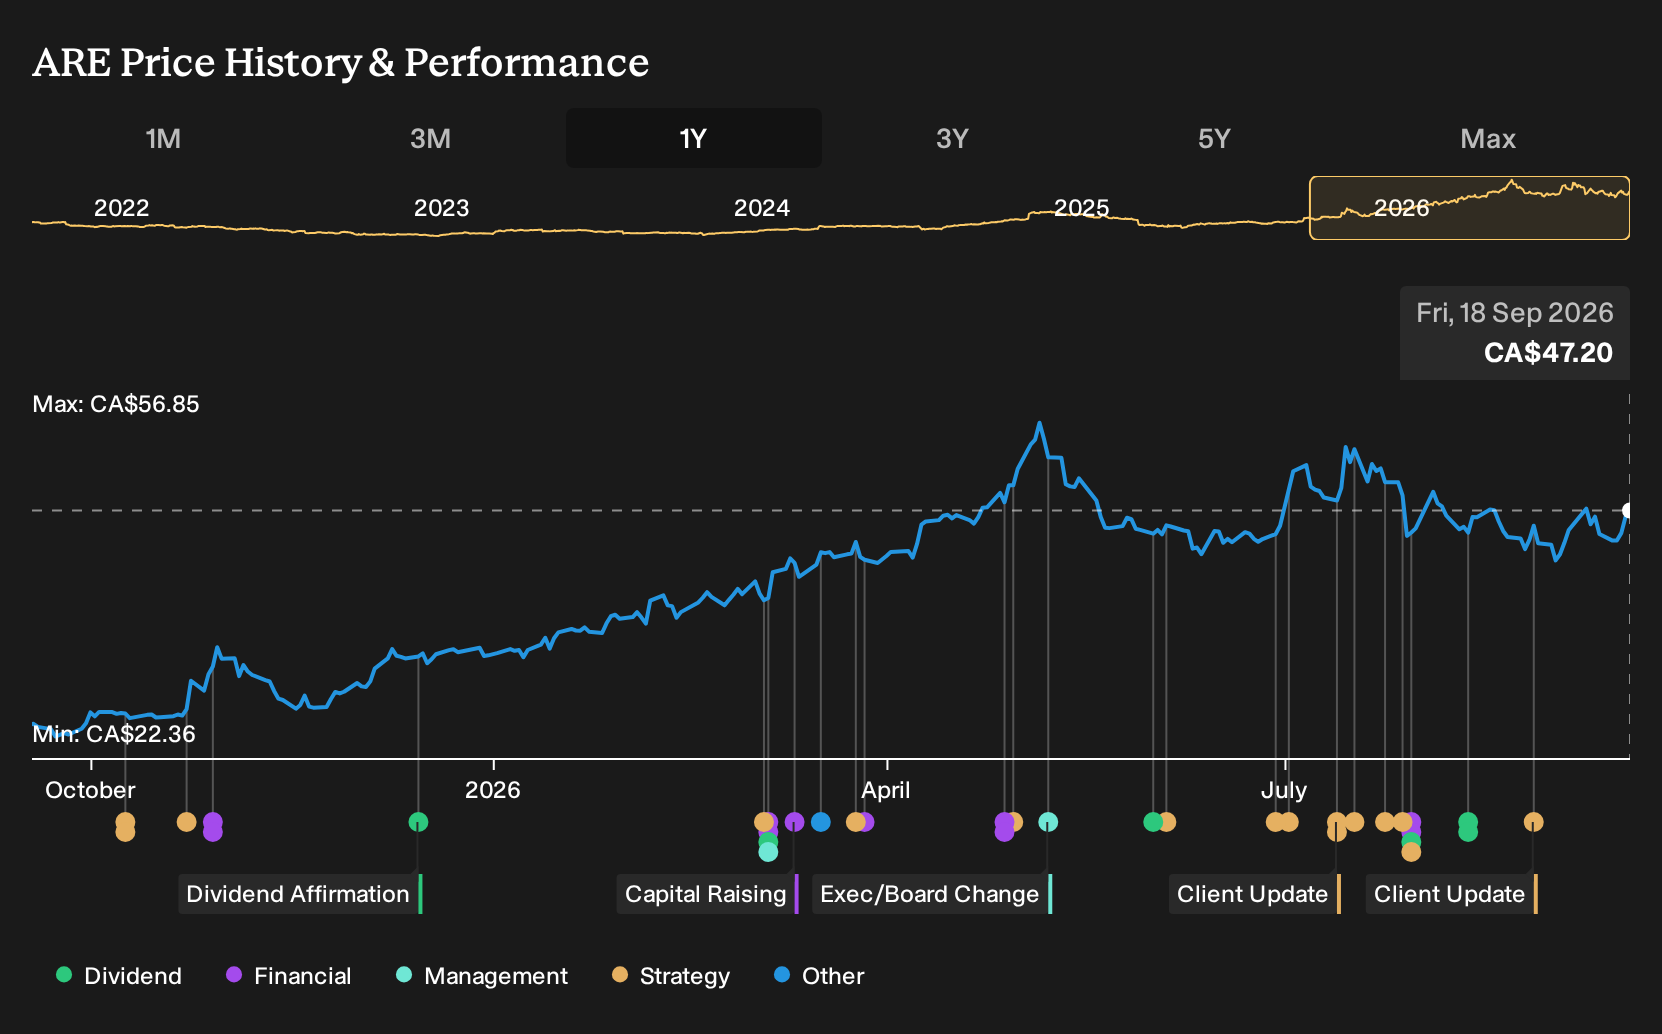
Exploring Other Perspectives
One bullish twist on Aecon Group focuses on earnings power rather than margin strain. The most optimistic analysts were already pencilling in CA$7.1b revenue and CA$183.4m earnings by 2029 before this C$1t investment push. You can treat those projections as one end of the spectrum and ask how the new policy might shift them.
Explore 3 other Aecon Group fair value estimates, including one that suggests as much as 31% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis and judgment.
- A great starting point for your Aecon Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Aecon Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Aecon Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Aecon Group?
If the Aecon Group story has you thinking about portfolio gaps, it can help to scan a wider field of potential opportunities that share similar quality traits or risk profiles. The Simply Wall St screener lets you filter by financial strength, valuation, dividends, and more, so you can build a watchlist that matches your own approach rather than relying only on headline stories.
- If capital preservation is your priority, start with companies that have lower risk profiles and resilient fundamentals using the 8 resilient stocks with low risk scores.
- For investors hunting for quality at a reasonable price, narrow your focus to businesses that combine solid cash flows with supportive valuations through the 4 high quality undervalued stocks.
- Income focused readers can zero in on shares with higher yields and robust payout support by scanning the 1 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com