
Columbia Banking System (COLB) Gets A Fresh Credit Backdrop As Valuation Stays In Focus
Columbia Banking System (COLB) is back in focus after KBRA assigned an A- rating with a Stable Outlook to Columbia Bank's new US$250 million subordinated notes due September 18, 2036.
Recent trading has been softer, with Columbia Banking System’s share price down 2.9% over the past 30 days and 3.0% over the last 90 days. However, the year-to-date share price return is 6.2% and the 1-year total shareholder return is 18.5%, suggesting longer term investors have seen stronger gains than short term traders.
Compare Columbia Banking System with a curated 30 resilient stocks with low risk scores that share similar balance sheet strength and could be relevant when credit quality and funding costs are in focus.
Bulls point to Columbia Banking System’s credit rating and long run returns, while bears focus on the softer recent share move and funding costs. Which side does the current valuation actually support next?
Most Popular Narrative: 13% Undervalued
At a last close of $29.93 against a narrative fair value of $34.36, Columbia Banking System screens as undervalued on this framework, with the key question being whether the business can deliver the cash flow path the narrative assumes.
The planned acquisition and integration of Pacific Premier is positioned to significantly expand Columbia's customer base and market reach in high-growth Western U.S. regions, increasing loan and deposit growth as both population and economic activity continue to rise in these areas, and this is likely to have a positive impact on revenue and long-term earnings.
See why 148 investors see Columbia Banking System as 13% undervalued.
Result: Fair Value of $34.36 (UNDERVALUED)
Still, the narrative frays quickly if regional concentration in Western U.S. markets becomes a problem or if ongoing integrations keep costs and credit risks higher than analysts expect.
Find out about the key risks to this Columbia Banking System narrative.
Another View On Columbia Banking System’s Valuation
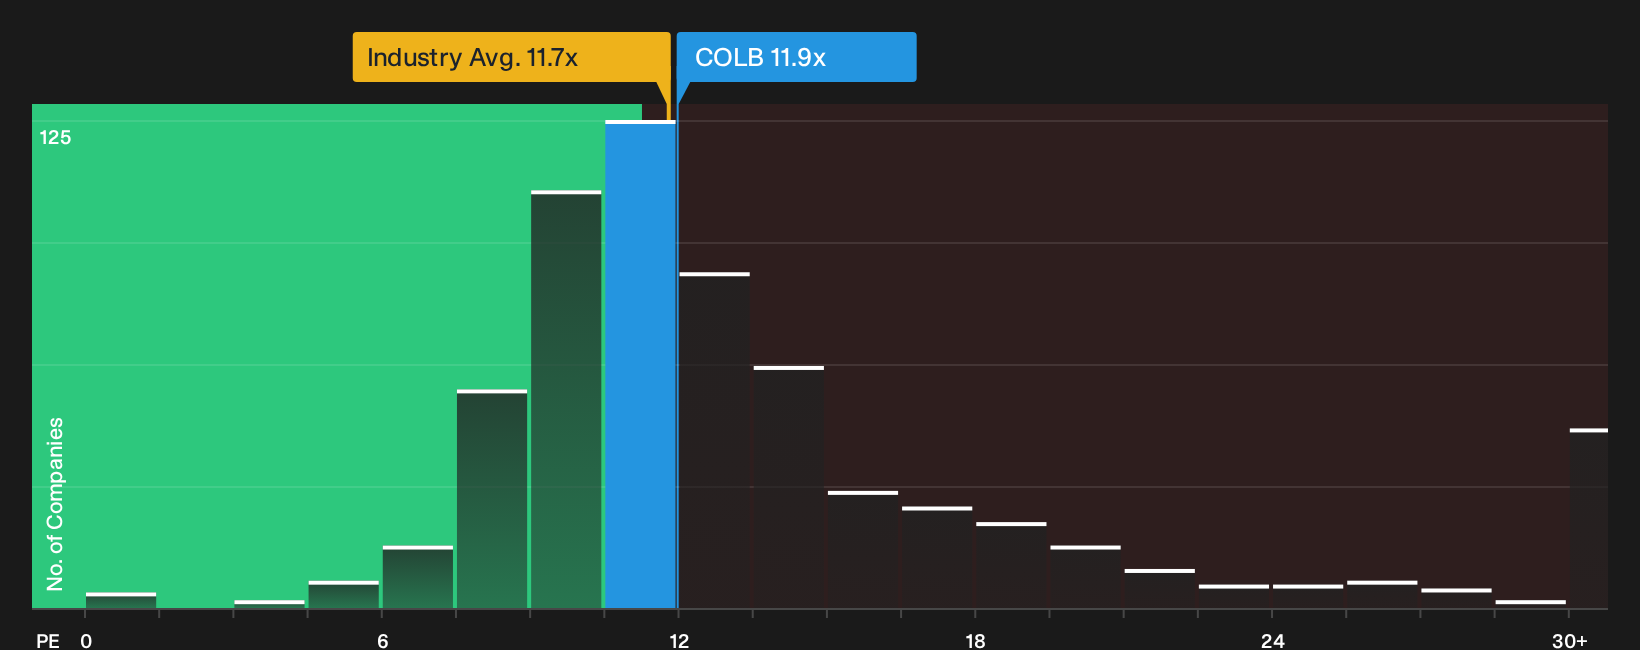
On the simple P/E math, Columbia Banking System does not look like a bargain. The shares trade on an 11.9x P/E, slightly above both the US Banks industry at 11.7x and peer average at 10.9x, even though the fair ratio is 13.1x. That gap points to limited downside on multiples, but also raises the question of how much upside investors can reasonably expect.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Still unsure where sentiment on Columbia Banking System really sits right now? Move quickly, review the full data set, and pressure test the bullish and cautious arguments against your own risk profile, then finish by weighing the 4 key rewards.
Looking for more investment ideas beyond Columbia Banking System?
If you are serious about sharpening your process, do not stop at Columbia Banking System. Use the screener to spot fresh opportunities that fit your playbook.
- Target potential value opportunities early by running through 16 high quality undiscovered gems that may not yet be crowded with attention.
- Strengthen your focus on downside protection by scanning a list of solid balance sheet and fundamentals (23 results) that can better handle funding stress and credit shocks.
- Prioritise resilience and capital preservation by reviewing a curated 30 resilient stocks with low risk scores that aims to keep surprises to a minimum.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com