
Safe Bulkers (SB) Looks Fairly Valued As It Prices €80.4 Million Share Offering
Follow on equity offering puts Safe Bulkers in focus
Safe Bulkers (SB) has completed a follow on equity offering of 12,000,000 common shares, raising €80.4 million at €6.7 per share through a subsequent direct listing.
This fresh capital event gives investors a new reference point for sentiment around the dry bulk shipowner. It arrives after an earlier filing for the same share issuance the previous day.
Safe Bulkers’ share price at US$9.18 caps a sharp run, with a 90.1% year to date share price return and a 110.2% total shareholder return over the past year that signals strong momentum building ahead of and around this follow on offering.
Compare this latest Safe Bulkers equity raise with a curated group of other shipping and asset heavy operators using our list of solid balance sheet and fundamentals (23 results)
Safe Bulkers has just priced fresh equity after a strong run in the stock, so the real fork in the road now is simple. Pay up today, or wait for a cleaner entry once the valuation work is done.
Most Popular Narrative: 3% Undervalued
Safe Bulkers is trading at $9.18 against a widely followed fair value view of $9.50, so the fresh equity raise lands with a market price already close to that assessment and leaves little room for sloppy assumptions about what drives the business.
Safe Bulkers' ongoing fleet renewal, with recent deliveries of technologically advanced and energy-efficient vessels (including dual-fuel and methanol-ready ships), enhances its positioning as global emissions standards tighten, which supports stronger charter rates and better net margins versus owners of older, less compliant ships.
The substantial portion of the global fleet now over 15 years old, combined with accelerated recycling and minimal dual-fuel newbuild deliveries, points to limited future vessel supply growth, which will likely support higher vessel utilization and revenue growth for operators like Safe Bulkers.
See why 13 investors see Safe Bulkers as 3% undervalued.
Result: Fair Value of $9.50 (UNDERVALUED)
Still, the Safe Bulkers narrative can be knocked off course if drybulk fleet capacity grows faster than demand, and if tighter decarbonization rules push operating costs higher.
Find out about the key risks to this Safe Bulkers narrative.
Another View on Safe Bulkers' Valuation
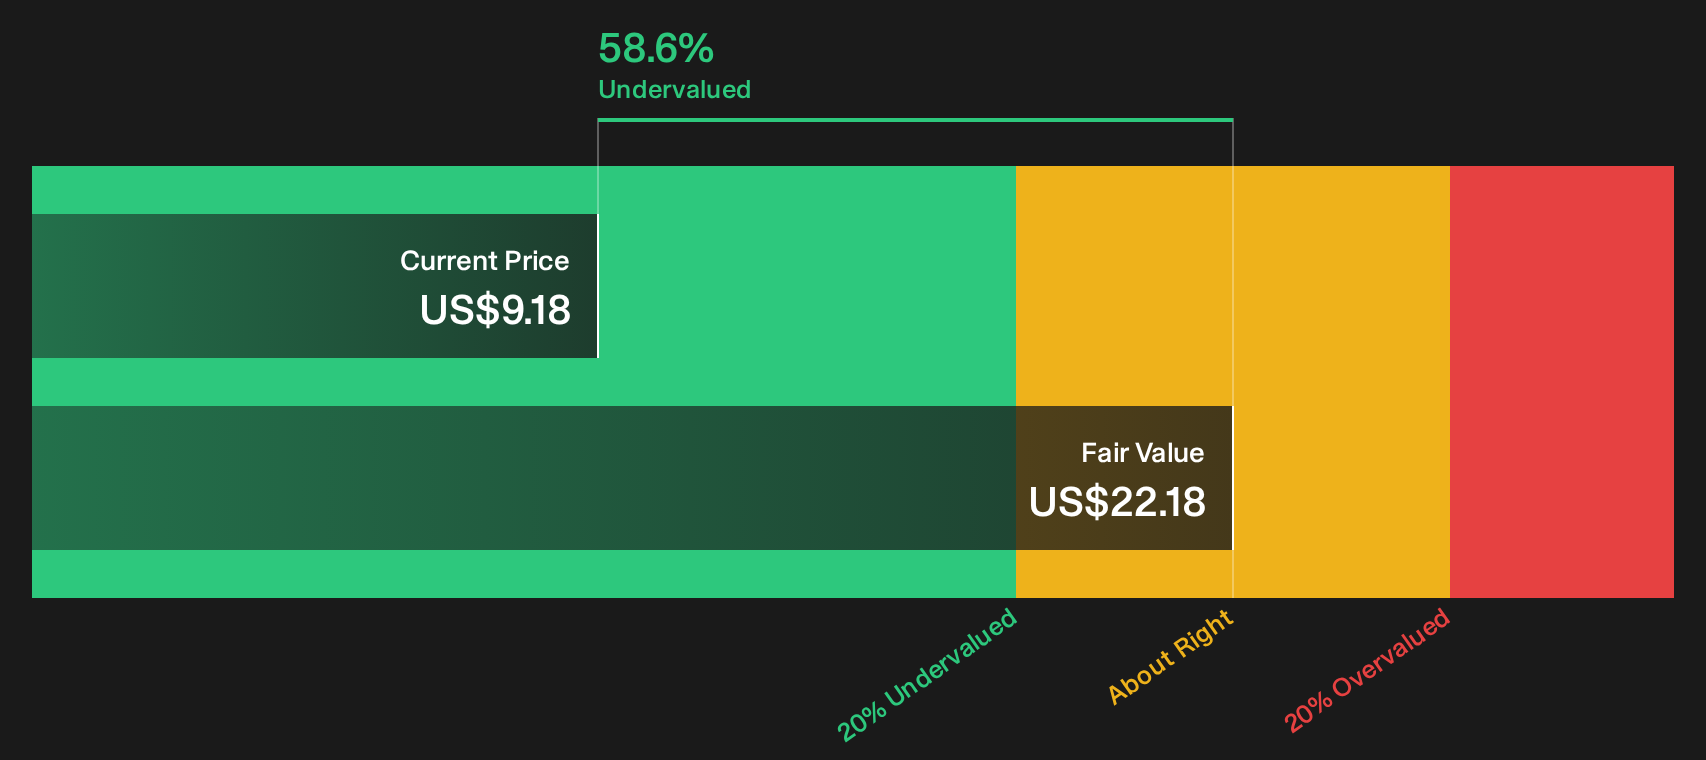
Safe Bulkers screens as cheap on cash flow, with our DCF model suggesting the $9.18 share price sits well below an estimated $22.18 future cash flow value. This flags the stock as undervalued rather than merely close to the $9.50 fair value narrative. Which signal do you treat as more convincing?
For a closer look at how this figure comes together, including the assumptions that push the gap so wide, Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages on Safe Bulkers so far, or a clear signal hiding in plain sight? Act while the data is fresh and pressure test the bullish and cautious arguments yourself by weighing the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Safe Bulkers?
If Safe Bulkers has your attention, do not stop there. Broaden your watchlist now so you are not chasing opportunities after the crowd has already moved.
- Target potential mispricings by scanning for companies that combine quality fundamentals with attractive valuations through the 35 high quality undervalued stocks.
- Strengthen your income stream by checking companies built around higher yields and resilient payouts using the 7 dividend fortresses.
- Dial down portfolio risk by filtering for businesses with sturdier finances and lower risk scores via the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com