
Learn Why The Bull Case For PROCEPT BioRobotics Stock Could Change Following Sales Inflation Lawsuits
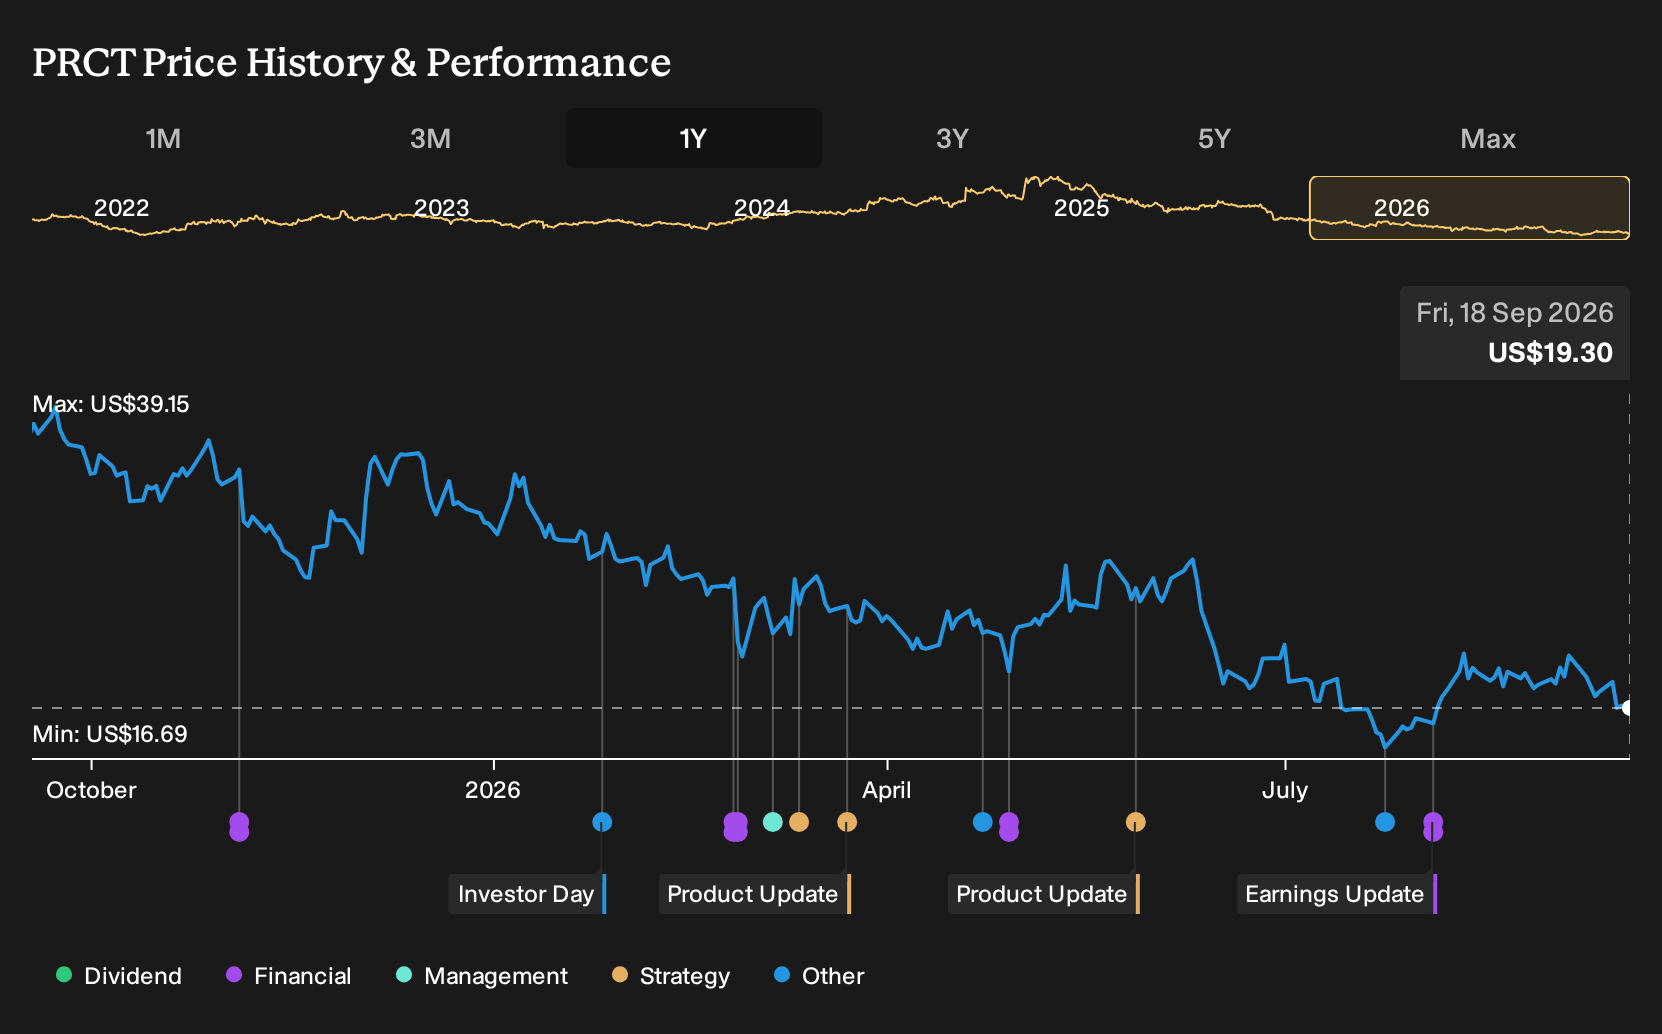
- Law firms Robbins Geller Rudman & Dowd and Kaplan Fox & Kilsheimer filed securities class actions against PROCEPT BioRobotics, alleging undisclosed discount programs inflated reported handpiece sales, revenue figures, and sales guidance, covering investors who bought shares between February 28, 2024 and February 25, 2026.
- The lawsuits focus squarely on PROCEPT BioRobotics' core Aquablation consumables engine, raising questions about how much reported handpiece demand reflects underlying procedure momentum versus sales tactics and inventory buildup.
- We will now examine how PROCEPT BioRobotics' investment narrative could shift in light of allegations that discounting practices exaggerated handpiece demand.
Broaden your options beyond PROCEPT BioRobotics by scanning 95 robotics and automation stocks, which could offer cleaner exposure to surgical robotics and automation without the current legal overhang.
PROCEPT BioRobotics Investment Narrative Recap
To own PROCEPT BioRobotics, you need to believe Aquablation can keep gaining traction in benign prostatic hyperplasia, with more HYDROS placements and rising procedure volumes supporting recurring consumable demand. The short term catalyst remains execution on that adoption curve and surgeon engagement, not courtroom outcomes. Current lawsuits focus more on how past demand was reported than on the underlying technology or clinical need.
The bigger operational risk sits in profitability and funding. The business is still loss making, with net income of US$109.8 million in the red and no profitability expected in the next three years. Any disruption to handpiece pull through or tighter reimbursement would make the path to scale and improved margins harder, especially with heavy R&D and a sole source component supplier.
The Robbins Geller and Kaplan Fox class actions go straight at reported handpiece and revenue figures between February 2024 and February 2026. That matters for you because Aquablation consumables are central to the PROCEPT BioRobotics model, and any restatement or revised guidance could affect how credible current volume trends and inventory levels look.
Operationally, the key question is whether underlying procedures are healthy once discounting and channel effects are stripped out. If reported growth reflects real surgeon usage, the existing reimbursement tailwinds, such as the permanent CPT Category I code and higher Medicare facility payments, still frame the main upside catalyst. If not, the lawsuits highlight an extra layer of execution and forecasting risk on top of the already challenging route to profitability.
PROCEPT BioRobotics' current analyst story points to revenues of US$607.5 million and earnings of US$69.6 million by 2029, based on an assumed 21.7% yearly revenue growth rate. That path implies a swing in profitability of about US$179.4 million from today, moving from a net loss of US$109.8 million to the projected profit figure.
Uncover why PROCEPT BioRobotics' fair value indicates an 18% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
For PROCEPT BioRobotics, the lowest analysts were already focused on reimbursement risk, which now feels sharper in light of the discounting claims. Before this news, that group was pencilling in about US$570.6 million of revenue and US$69.2 million of earnings by 2029, yet only a US$16.0 target. That is a meaningfully harsher story. Use it as a reminder to compare several viewpoints before deciding how this lawsuit fits your own thesis.
Explore 6 other PROCEPT BioRobotics fair value estimates, including one that suggests up to 17% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your PROCEPT BioRobotics research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for PROCEPT BioRobotics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PROCEPT BioRobotics' overall financial health at a glance.
Looking For More Investment Ideas Beyond PROCEPT BioRobotics?
If this PROCEPT BioRobotics story leaves you wanting a broader watchlist, you can use that curiosity as a prompt to widen your research universe with a few focused screens that match your own risk and income preferences.
- If capital preservation is high on your list, you might look at companies that score well on resilience and balance sheet strength through the 30 resilient stocks with low risk scores.
- If you are hunting for mispriced opportunities with solid underlying fundamentals, you could widen your search by running the 35 high quality undervalued stocks.
- If quality and financial discipline matter more to you than headline popularity, you can broaden your radar with the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com