
How Hyatt Loyalty Tie Up At Delta Air Lines Stock Has Changed Its Investment Story
- Hyatt Hotels announced a new long term loyalty collaboration with Delta Air Lines, allowing eligible World of Hyatt and SkyMiles elite members to earn both points and miles on qualifying flights and hotel stays, with further benefits and program details to be shared in the coming months.
- The tie up directly links Delta Air Lines premium air network with Hyatt’s hotel footprint, which could deepen high value customer engagement across both airfare and accommodation spending, an area that already matters for Delta’s focus on premium and loyalty driven revenue.
- We will now look at how Delta Air Lines investment narrative could be influenced by this dual earning loyalty partnership with Hyatt.
Delta Air Lines Investment Narrative Recap
To own Delta Air Lines, you need to believe the airline can keep turning its premium, loyalty and international focus into steadier cash generation while managing a high debt load and uneven demand in domestic and main cabin travel. The key near term catalyst is execution on margin protection through flat capacity and disciplined costs, which the Hyatt partnership supports only indirectly.
The biggest current operational risk is softer corporate travel and price pressure from low cost rivals, which can weigh on yields if demand cools. Upcoming quarterly results in October will give you the clearest read on whether profit margins, cash flow and debt metrics are moving in the right direction.
The new long term loyalty collaboration with Hyatt looks most relevant for the premium and loyalty thesis that underpins many views on Delta Air Lines. Dual earning on flights and hotel stays ties high value travelers more tightly to the ecosystem, which can support load factors and spending in premium cabins if customers respond well to the offer.
For catalysts, this partnership feeds directly into the focus on resilient revenue streams such as premium seats, loyalty contribution and international traffic. Execution risk sits in the program rollout and in how quickly any uplift in customer behavior shows up in operating metrics that investors track closely, such as unit revenue, loyalty contribution and free cash flow.
Delta Air Lines' narrative projects US$77.0b revenue and US$7.3b earnings by 2029. This rests on 4.1% yearly revenue growth and an earnings increase of about US$3.3b from the current US$4.0b level.
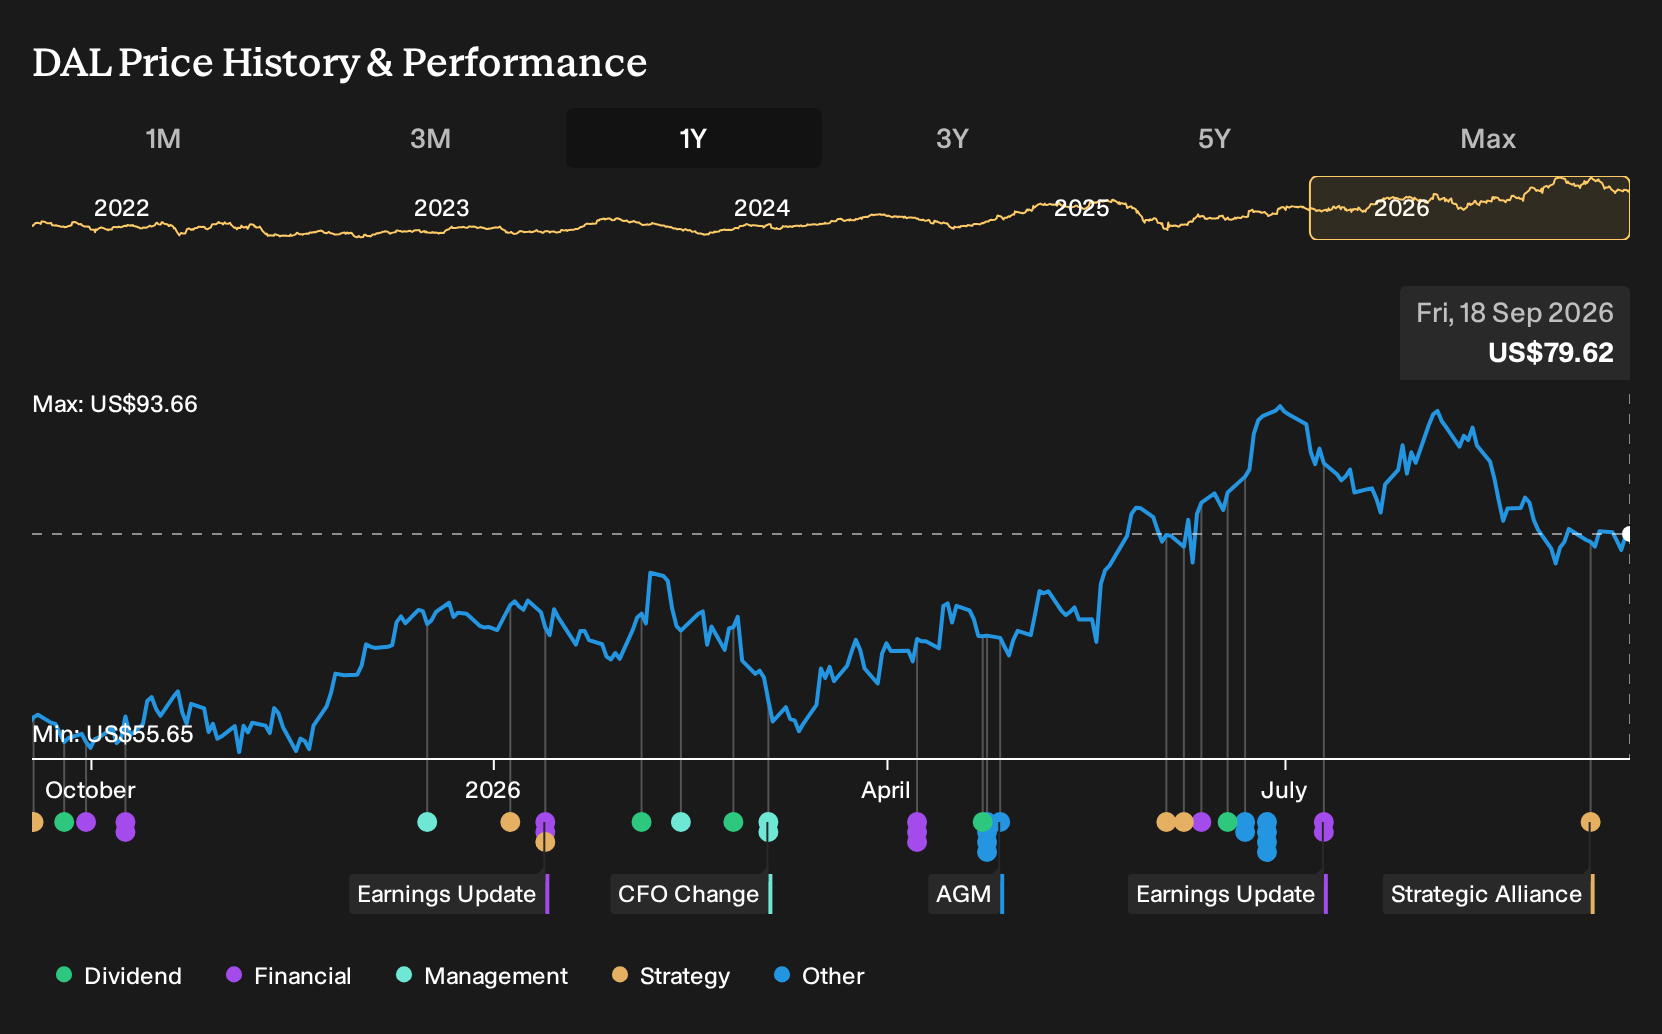
Uncover why Delta Air Lines' fair value indicates a 33% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts already expected Delta Air Lines to reach about US$83.7b of revenue and US$7.5b of earnings by 2029, largely on the back of premium and loyalty growth. You now have this Hyatt partnership in the mix, which those estimates did not factor in, so it could eventually reshape those upbeat narratives if the loyalty tie-in gains traction.
Explore 6 other Delta Air Lines fair value estimates, including one that suggests as much as 189% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Delta Air Lines research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Delta Air Lines. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Delta Air Lines' overall financial health at a glance.
Looking For More Investment Ideas Beyond Delta Air Lines?
If the Delta Air Lines and Hyatt loyalty story has your attention, it can help to widen the lens and compare it with other businesses that line up with your risk profile, income needs, or quality focus. The Simply Wall St Screener lets you filter for stocks that match your criteria so you can build a watchlist that fits how you actually invest.
- For investors who care most about balance sheet strength and solid fundamentals, start with a curated list of solid balance sheet and fundamentals (23 results). It can help you find companies built on sturdier financial footing.
- If value is your priority and you are hunting for quality at a reasonable price, scan a focused set of 35 high quality undervalued stocks. These may offer more compelling entry points than headline names.
- Income focused investors who want yield plus resilience can review a targeted group of 7 dividend fortresses. These aim to combine higher payouts with more durable business profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com