
Is Appian (APPN) Fully Valued After Gartner Named It A Workflow Automation Leader?
Appian (APPN) just picked up fresh validation from Gartner, which ranked the platform #1 in key workflow automation and consolidation use cases and again labeled the software provider a Leader in business orchestration.
Gartner’s recognition lands after an eventful stretch for Appian, with the shares now at US$37.52. The 90-day share price return of 88.83% points to strong recent momentum, while the 5-year total shareholder return, down 64.97%, shows how long term holders have faced a very different experience.
Spot 38 profitable AI stocks that aren't just burning cash that pair real AI automation credentials with financial discipline, if Appian’s Gartner win has you looking for other software platforms executing on this theme.Appian now trades above the average analyst target yet screens at a discount to some intrinsic estimates after a sharp 90 day rally. Is the market’s caution around this rebound still warranted?
Most Popular Narrative: 10.4% Overvalued
On Simply Wall St, the most followed narrative now pegs Appian’s fair value at $34, which sits below the latest $37.52 close and presents the current rally as slightly ahead of those long range assumptions.
Broad enterprise demand for application modernization and workflow automation is accelerating, with AI seen as a catalyst that dramatically lowers modernization costs and complexity, positioning Appian's platform for increased adoption, larger deal sizes, and improved revenue growth over the coming years.
See why 17 investors see Appian as 10% overvalued.
Result: Fair Value of $34 (OVERVALUED)
Still, the bullish Appian storyline could unravel if larger platform rivals squeeze pricing power, or if ongoing high R&D and sales spend delays sustained profitability.
Find out about the key risks to this Appian narrative.
Another View: Appian Through The DCF Lens
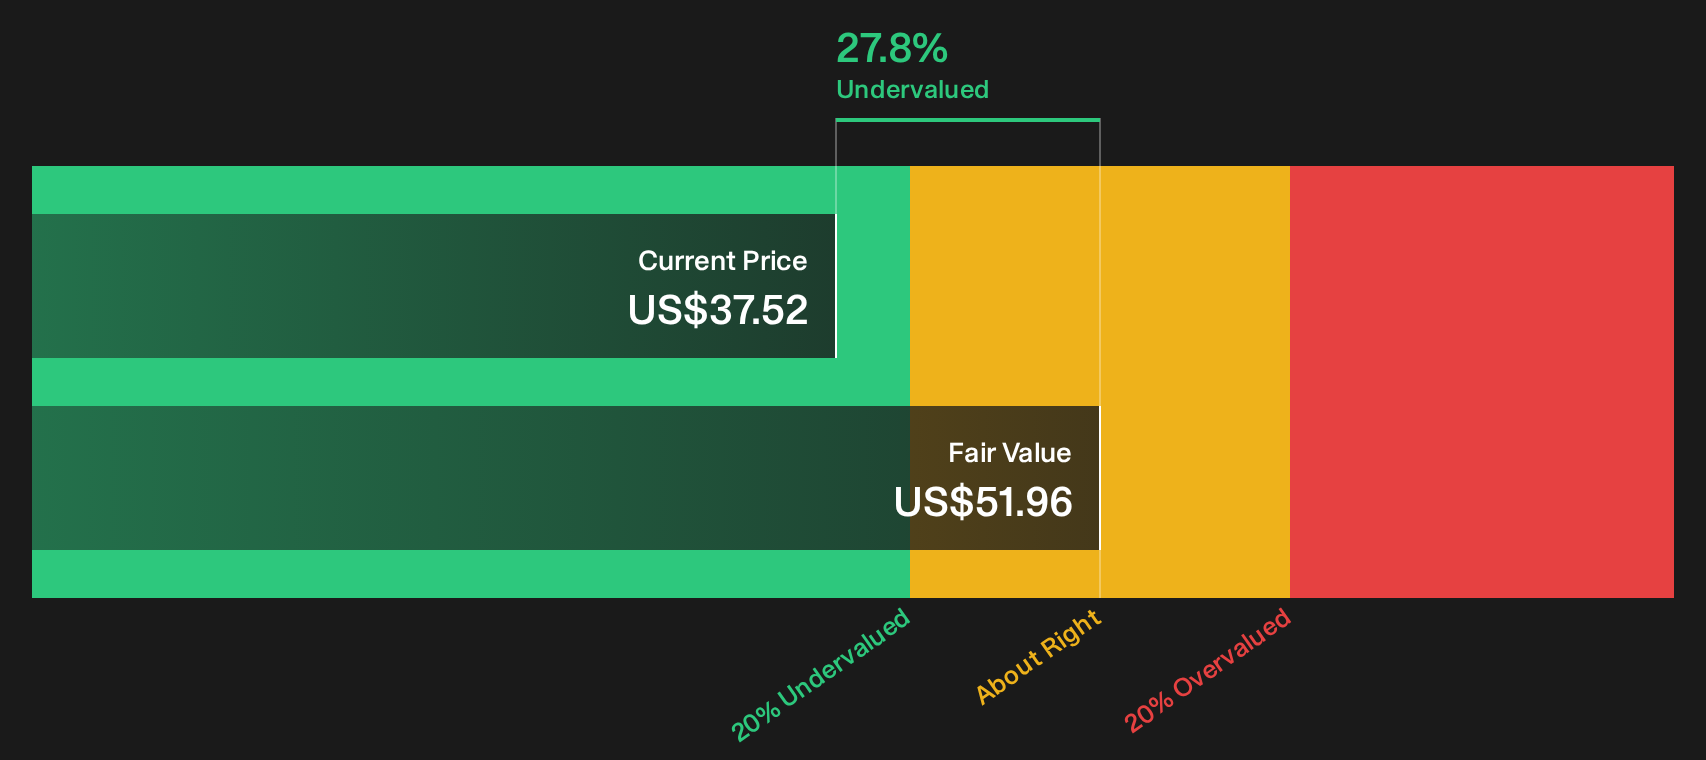
The analyst narrative frames Appian as 10.4% overvalued at $37.52 based on a $34 fair value, yet the Simply Wall St DCF model paints a very different picture. On that cash flow view, Appian screens as undervalued, with the shares trading below an estimated future cash flow value of $51.96. Which story do you think better fits how you see the next decade for this business?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around Appian’s value and risk profile make this a good moment to move quickly, review the full picture, and decide where you stand. To weigh the downside concerns against the upside potential in a single snapshot, start with 3 key rewards and 1 important warning sign.
Looking for more Appian sized ideas?
If Appian’s setup has your attention, do not stop here. Broaden your watchlist now so you are not chasing the next move after it happens.
- Target value with quality first and scan a curated universe of companies that combine solid fundamentals with attractive pricing using the 35 high quality undervalued stocks.
- Shift your focus toward resilience and stress test your portfolio against volatility by filtering for businesses with sturdier finances through the list of solid balance sheet and fundamentals (23 results).
- Hunt for early stage potential and widen your opportunity set by tracking high quality smaller players flagged in the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com