
Bunge Global (BG) Stock Dropped, So What Is Driving Attention Now?
Why Bunge Global Is Back on Investor Radars
Bunge Global (BG) has moved into focus after raising its full year 2026 adjusted EPS guidance and increasing its Viterra cost synergy target, following stronger results in key processing divisions.
Recent trading tells a mixed story. Bunge Global’s share price has slipped 3.1% over the last day and 5.6% across the past week, yet it still shows a 24.8% year to date share price return and a 49.7% one year total shareholder return. This suggests earlier momentum is now cooling as investors reassess the raised guidance, the Viterra integration progress and upcoming investor visibility events like the Morgan Stanley Laguna conference.
Compare Bunge Global’s guidance upgrade and integration story with other potential candidates by scanning the 35 high quality undervalued stocks that share resilient balance sheets and cash flow focused profiles.
Bunge Global now trades below its recent highs even after lifting guidance and raising Viterra synergy targets. Does that setup argue for stepping in today, or for holding out for a cheaper entry before the integration is further tested on cash flow?
Most Popular Narrative: 19% Undervalued
The most followed narrative on Bunge Global pegs fair value at $142.00 per share, compared with the recent close of $115.58, so the focus shifts to whether that valuation rests on realistic growth, margin and policy assumptions.
The completion and integration of the Viterra merger provides substantial cost and commercial synergies, expands Bunge's global origination, processing, and distribution footprint, and positions the company to capture greater market share in high-growth markets, which is set to drive higher topline growth and improved operating margins.
See why 54 investors see Bunge Global as 19% undervalued.
This widely followed view uses a 7.11% discount rate and assumes Bunge Global can compound revenue, expand profit margins and translate those gains into stronger earnings quality over time. It also assumes the enlarged agribusiness can manage regulatory shifts in biofuels, integration complexity around Viterra and ongoing capital spending demands without eroding that projected cash generation profile.
Result: Fair Value of $142.00 (UNDERVALUED)
Still, the narrative around Bunge Global could be knocked off course if Viterra integration synergies disappoint or if biofuel policy shifts hit refined and specialty oils harder.
Find out about the key risks to this Bunge Global narrative.
Another View on Bunge Global’s Valuation
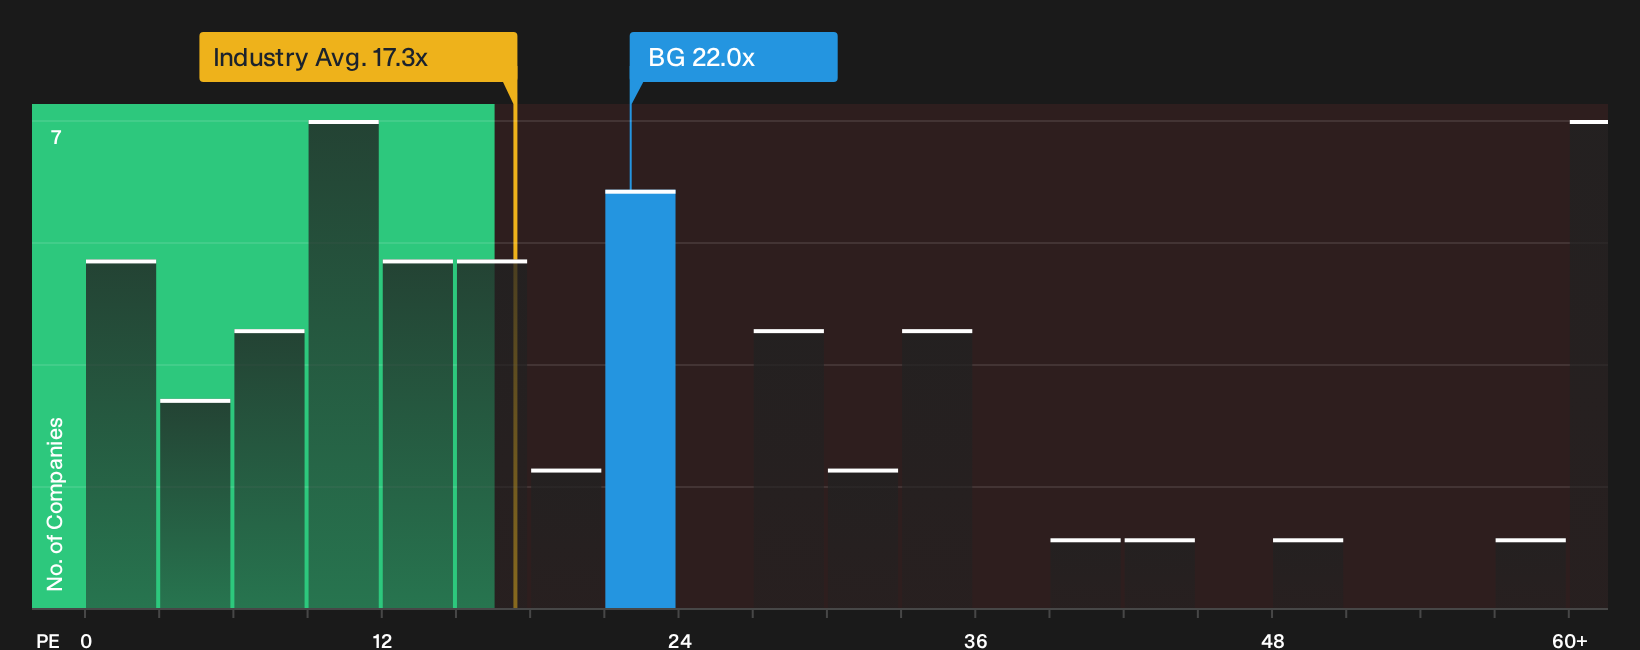
The first narrative leans on discounted cash flows and a $142.00 fair value for Bunge Global. A simpler cross check looks at P/E. BG trades on 22x earnings versus 17.3x for the US Food industry and 23.2x for peers, while its fair ratio is 36.4x. That gap hints at upside if sentiment shifts, but also raises the question of how much earnings risk you are willing to underwrite at this price.
If you want to see how that earnings based view stacks up against a full ratio breakdown and where the market could move the multiple, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in this Bunge Global story inspires confidence, and plenty still raises questions. Move quickly, test the numbers yourself, and weigh both sides by reviewing 3 key rewards and 3 important warning signs
Looking For More Bunge Global Investment Ideas?
If you like the Bunge Global story but want a broader watchlist, use the Simply Wall St screener to spot other opportunities before they move.
- Target resilient compounding potential by scanning a 35 high quality undervalued stocks universe that blends solid fundamentals with prices that lag underlying business quality.
- Build steadier income streams by reviewing a 7 dividend fortresses that focuses on higher yielding payouts supported by underlying financial strength.
- Dial down portfolio risk by checking a 30 resilient stocks with low risk scores curated for companies with sturdier balance sheets and more predictable financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com