
Debt Sale Could Be A Big Deal For Sysco Stock (SYY)
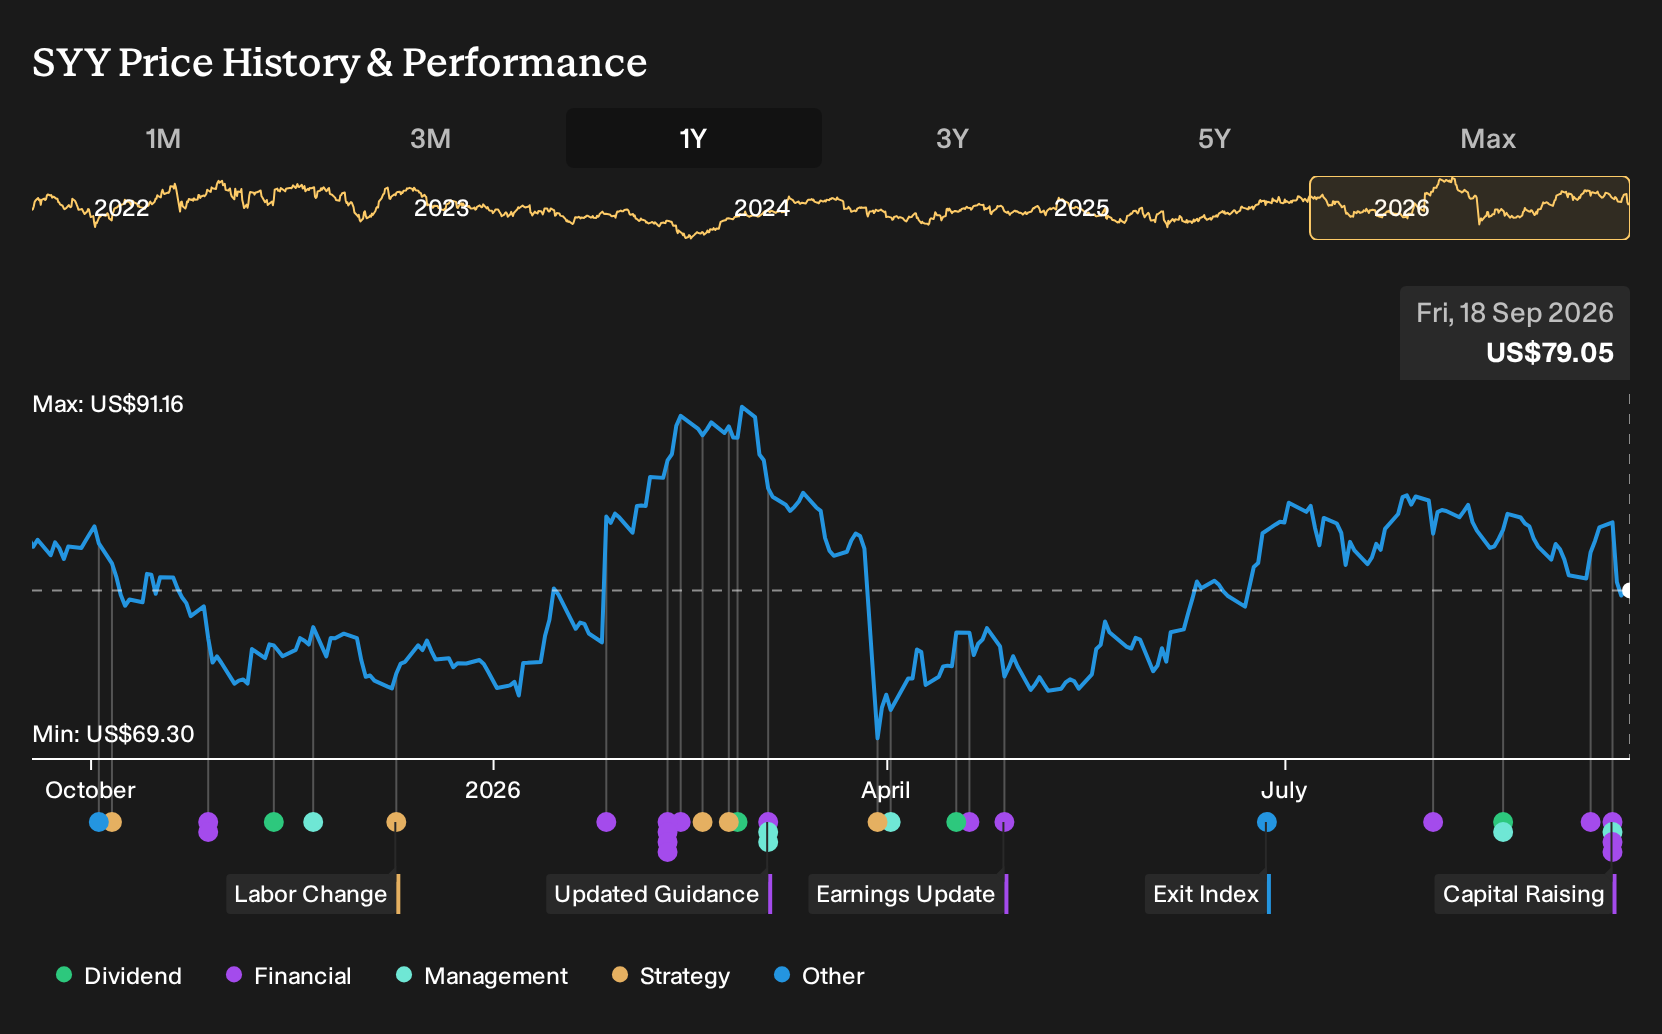
- Sysco has recently completed and filed follow on equity offerings of roughly US$1b and set up a universal shelf, then followed with a wide range of new fixed income securities across senior and subordinated tranches with maturities stretching from 2029 out to 2066.
- The mix of new common stock, long dated unsecured bonds and subordinated notes signals that Sysco is actively reshaping its capital structure to secure flexible funding for its foodservice distribution operations while managing different layers of balance sheet risk.
- We will now examine how Sysco's broader investment narrative aligns with this new wave of long dated debt issuance.
Review how Sysco is reshaping its balance sheet, then compare other companies with robust financing profiles using our curated list of list of solid balance sheet and fundamentals (23 results)
Sysco Investment Narrative Recap
To own Sysco, you need to believe its foodservice network can keep winning business even when restaurant traffic is choppy and consumer confidence is soft. The near term swing factor is execution on sales consultant productivity and pricing tools, which management expects to support revenue and earnings from fiscal 2026.
The biggest near term risk remains pressure on volumes if weak industry traffic, weather disruptions or low confidence persist, especially with debt not well covered by operating cash flow. The latest funding news does not change that operating backdrop in a material way. It mostly affects how the balance sheet is structured.
The most relevant recent announcement for this financing push is Sysco’s reaffirmed fiscal 2027 guidance for net sales of about US$90b, with expected top line growth of roughly 6% to 7%. That outlook frames why investors will watch whether today’s capital structure supports the build out of new fulfillment capacity and technology.
You can use that sales ambition as a reference point when judging the new mix of senior and subordinated fixed rate notes running from 2029 out to 2066. A long maturity ladder can help match funding to warehouse projects, pricing systems and the Sysco To Go pilot, but it also increases exposure if operating conditions worsen or consultant turnover problems reappear.
Sysco's current analyst narrative points to forecast revenue of about US$96.1b and projected earnings of roughly US$2.7b by 2029. These figures are built on an assumed 4.4% yearly increase in sales and an earnings increase of about US$0.9b from US$1.8b today.
Uncover why Sysco's fair value indicates a 13% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$89 to US$143 per share, so some retail investors see Sysco as deeply undervalued while others assume far richer pricing. That spread reflects real world risks around weak restaurant traffic, low consumer confidence and new long dated debt. You should weigh these factors by exploring multiple viewpoints.
Explore 2 other Sysco fair value estimates, including one that suggests it could be worth just $89.31.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Sysco research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sysco. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sysco's overall financial health at a glance.
Looking For More Investment Ideas Beyond Sysco?
If Sysco's balance sheet work has you thinking about portfolio construction more broadly, it can help to line it up against other businesses with different risk and return profiles. The Simply Wall St Screener lets you filter for traits that match your own priorities, whether that is potential mispricing, resilience, or income.
- If you are hunting for potential mispriced opportunities with solid fundamentals, take a look at 35 high quality undervalued stocks that might warrant a closer look.
- If capital preservation and a smoother ride matter most to you, scan through 30 resilient stocks with low risk scores that score well on financial strength and earnings stability.
- If reliable income streams are your focus, start comparing 7 dividend fortresses that combine higher yields with fundamental checks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com