
Did Store Expansion Just Shift BBB Foods (TBBB) Investment Narrative?
- BBB Foods reported strong Q2 2026 fundamentals, with total revenue up 39% year over year, same store sales growth of 20%, and 155 new store openings that lifted the network to 3,624 locations alongside an expanded distribution footprint.
- The combination of rapid physical expansion and ongoing investment in talent and technology suggests a business that is still in heavy build-out mode. This dynamic can reshape how investors evaluate its balance between growth opportunities and cost discipline.
- Next, the focus shifts to how BBB Foods' 39% revenue increase could reshape the existing investment narrative around scale, margins, and risk.
Scan beyond BBB Foods and see how other fast expanding retailers stack up on revenue momentum and footprint growth with our curated 16 high quality undiscovered gems.
BBB Foods Investment Narrative Recap
To own BBB Foods, you need to believe that heavy store rollout and investment in technology can eventually support healthier margins, not just bigger revenue. The latest quarter fits that story. Same store sales growth of 20% and a 39% revenue jump show demand is there. The near term swing factor is whether new locations scale efficiently.
The biggest risk right now is that rapid expansion plus upfront costs keeps profitability under pressure if newer stores take longer to mature. Q2 does not remove that concern. Strong top line numbers help, but they do not yet answer how quickly unit economics and margins can catch up with the speed of growth.
The most relevant update for this quarter is the opening of 155 new stores, taking BBB Foods to 3,624 locations, along with one additional distribution center. That kind of buildout can eventually support operating leverage and better use of logistics if store productivity and private label mix keep pace with the broader footprint.
For catalysts, the enlarged network gives management more room to push higher margin private label and improve route density in Mexico. The same expansion also amplifies existing risks such as lease costs, supplier concentration, and exposure to one country. Your view on BBB Foods likely comes down to confidence in execution on those operational trade offs.
BBB Foods Forecasts and Valuation Setup
Analysts sketch an aggressive roadmap for BBB Foods that leans heavily on revenue scale and a sharp swing in profitability. The projections assume the business keeps growing its top line at 28.2% a year over the next three years while margins move from a loss of 3.7% today to a slim profit of 0.9% by 2029. On that view, earnings are expected to shift from a loss of MX$3.4b today to MX$1.6b by 2029, although the spread between the most optimistic and most cautious forecasts is wide.
The same framework underpins how the stock is currently being valued. To line up with the analyst consensus, you would need to accept that by 2029 BBB Foods reaches MX$192.2b in revenue and MX$1.6b in earnings and that the shares trade on a P/E of 99.2x those future profits. That multiple sits well above the quoted 17.6x for the US Consumer Retailing group, so the story relies on investors continuing to pay a premium for growth, even as the business transitions from losses into modest profitability.
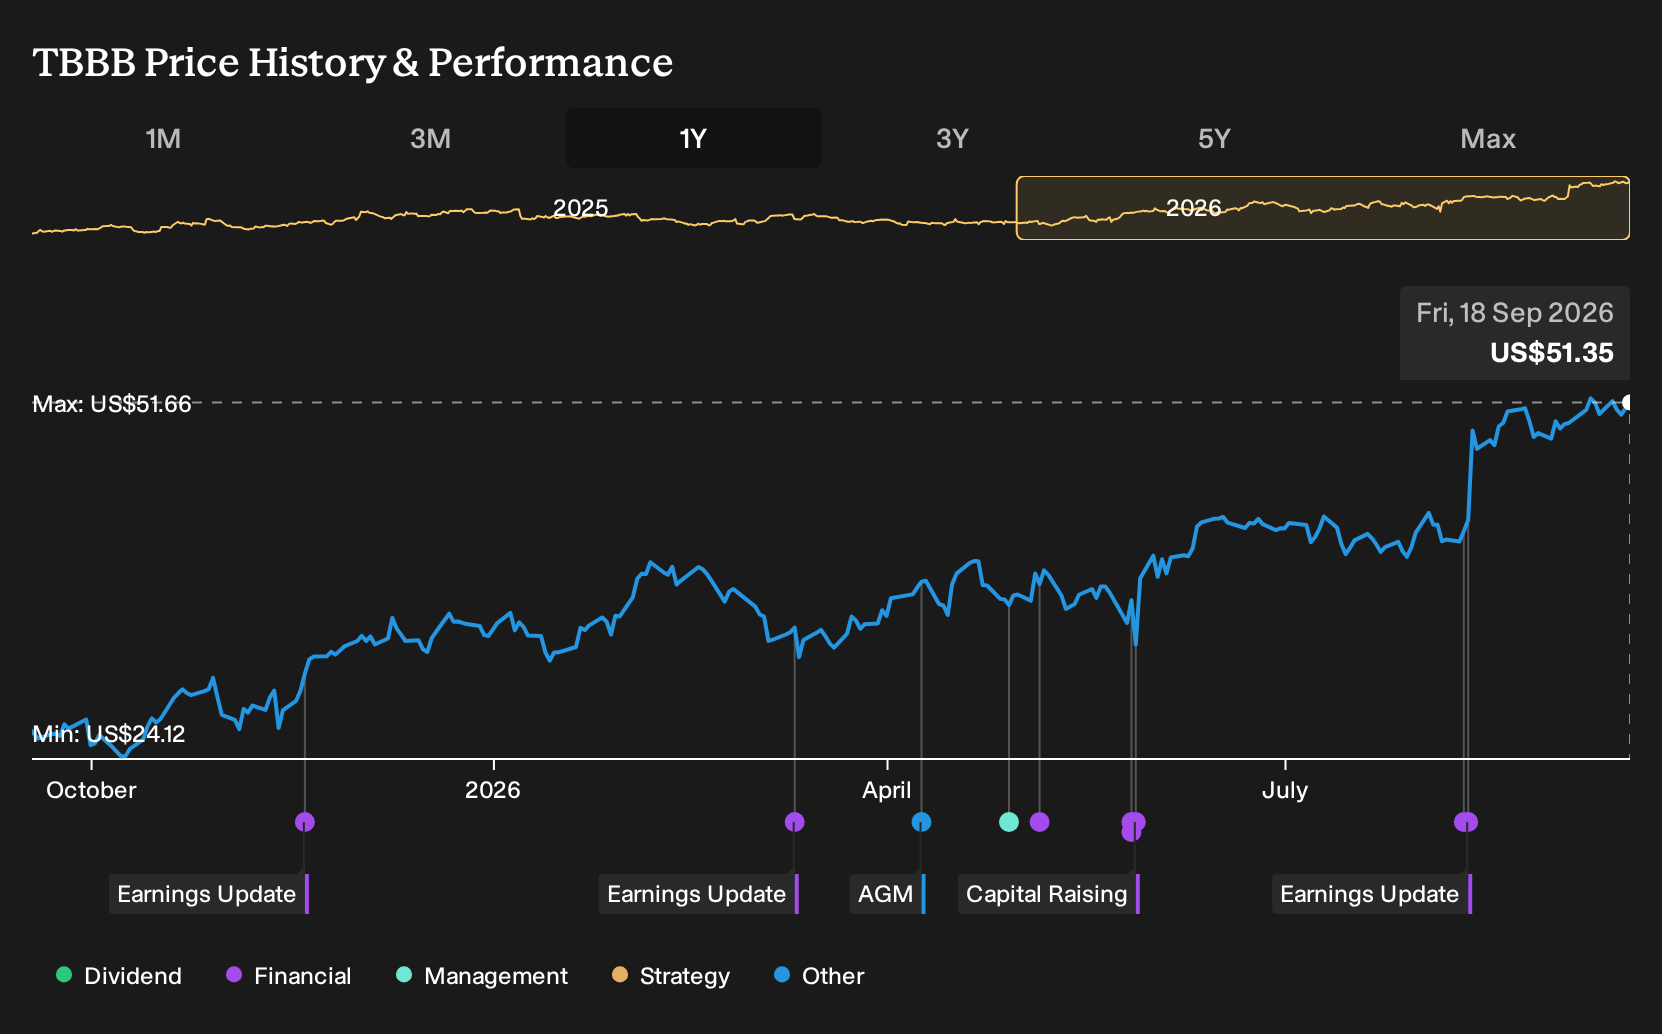
On price, the gap between where the stock trades and where analysts sit is extremely tight. The current share price of $51.66 is only 0.1% below the consensus target of $51.69, with individual views stretching from $40.13 up to $65.21. That narrow spread between price and target suggests the market already reflects a good chunk of the current forecast path, leaving your own conviction on execution and risk as the main swing factor.
BBB Foods' current loss of MX$3.4b and the forecast earnings of MX$1.6b by 2029 imply a sizeable shift in the income statement rather than a minor tweak. To get there, analysts are effectively baking in a move of about MX$5.0b from loss to profit, which would require both store cohorts and gross margin mix to look very different from today. Readers should weigh whether that profit bridge feels realistic given the cost of rapid expansion and the pressures that come with higher lease and logistics commitments.
BBB Foods' narrative projects MX$192.2b revenue and MX$1.6b earnings by 2029. This rests on 28.2% yearly revenue growth and an earnings swing of roughly MX$5.0b from a loss of MX$3.4b today.
Uncover why BBB Foods' fair value is in line with its current price.
Exploring Other Perspectives
One alternate angle around BBB Foods is saturation risk. The most bearish analysts worried that a faster buildout could eventually crimp store productivity, even before this Q2 update. They were pencilling in MX$180.7b revenue and MX$1.0b earnings by 2029, which sketches a much more cautious story you may want to compare with your own view.
Explore 2 other BBB Foods fair value estimates, including one that suggests up to 6% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your BBB Foods research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for BBB Foods. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BBB Foods' overall financial health at a glance.
Looking for more investment ideas beyond BBB Foods?
If the BBB Foods story has you thinking about position sizing, risk and upside across your whole portfolio, it can help to widen the lens and compare similar opportunities side by side using the Simply Wall St Screener.
- For investors who care most about price versus fundamentals, use our valuation filters to zero in on 35 high quality undervalued stocks that might suit a disciplined, value-conscious approach.
- If capital preservation is higher on your priority list, sort by risk metrics and financial strength to focus on 30 resilient stocks with low risk scores that aim to keep volatility in check.
- For those building a more income-focused portfolio, concentrate on cash returns by screening for 7 dividend fortresses that may help support a steady payout stream.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com