
Is Westinghouse Air Brake Technologies (WAB) Undervalued After Revenue Growth And Higher EPS Guidance?
Westinghouse Air Brake Technologies (WAB) is back on investor radars after reporting a 17.5% revenue increase, lifting full-year EPS guidance and sending the stock up 5.7% following its latest earnings release.
That one day jump sits against a softer near term picture, with a 30 day share price return down 5.8% even as the year to date share price gain sits at 29.6% and the 1 year total shareholder return reaches 49.2%. Momentum for Westinghouse Air Brake Technologies still leans positive over longer horizons despite recent volatility.
Scan Westinghouse Air Brake Technologies’ recent move, then expand your watchlist with handpicked industrial peers in the list of solid balance sheet and fundamentals (23 results).
After that sharp earnings pop and a strong longer term run, Westinghouse Air Brake Technologies now forces a choice: lean in at today’s price, or wait for a pullback that may not come on your timeline.
Most Popular Narrative: 13.6% Undervalued
On the most followed narrative, Westinghouse Air Brake Technologies screens modestly cheap, with a fair value of $324.17 against a last close of $280.23. That gap is being framed around rail modernization, decarbonization and digital rail spend rather than short term trading swings.
Growing integration of automation, digital solutions (such as Positive Train Control, Trip Optimizer, Inspection Technologies, and remote diagnostics), and Internet of Things across fleets is creating significant upsell and recurring subscription opportunities, translating into higher-margin digital revenue and improved long-term earnings potential.
See why 20 investors see Westinghouse Air Brake Technologies as 14% undervalued.
Result: Fair Value of $324.17 (UNDERVALUED)
Still, the story for Westinghouse Air Brake Technologies can change quickly if freight backlog softness persists or if acquisition related debt and integration issues start to bite.
Find out about the key risks to this Westinghouse Air Brake Technologies narrative.
Another View: Westinghouse Air Brake Technologies On Earnings Multiples
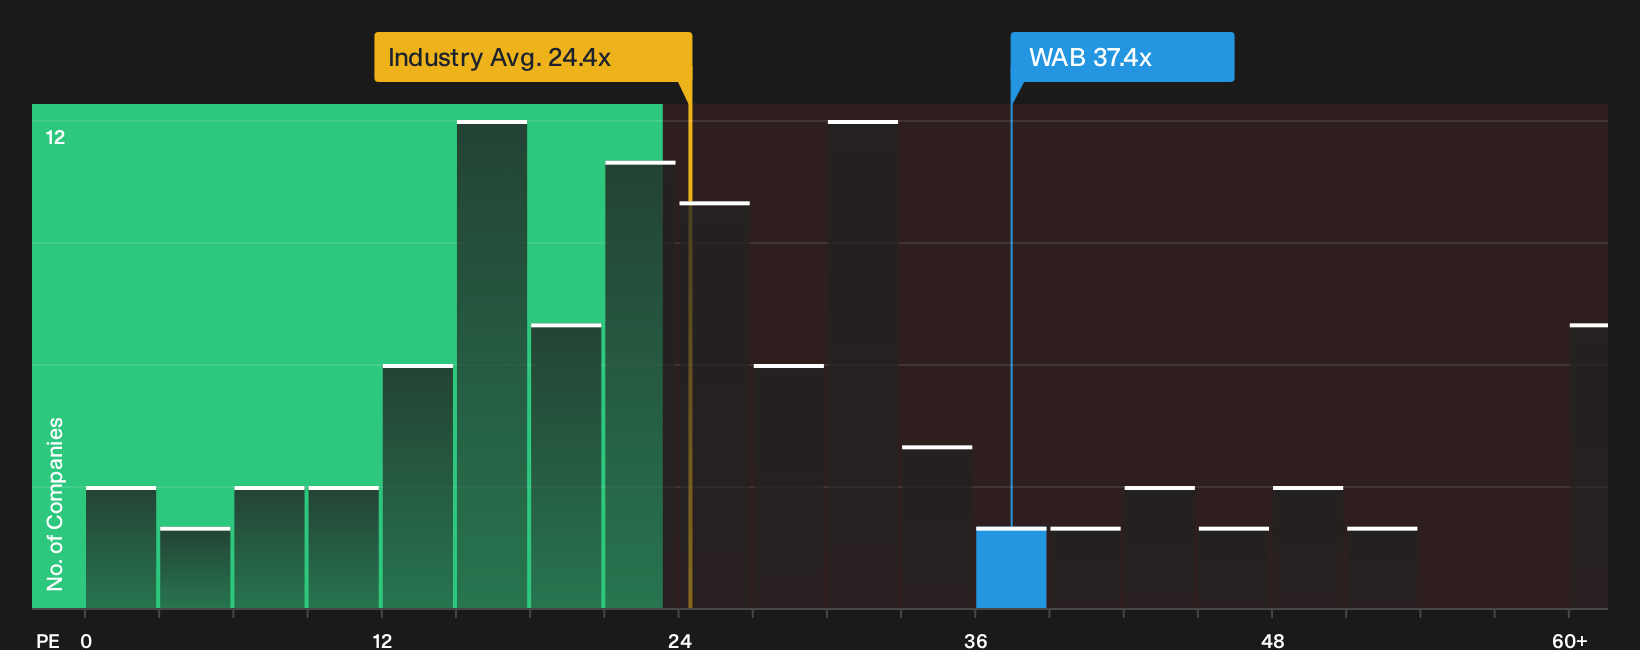
That 13.6% gap to fair value looks attractive on the SWS model, yet the earnings multiple tells a tougher story for Westinghouse Air Brake Technologies. The stock trades on a P/E of 37.4x versus a fair ratio of 31.4x and a Machinery industry average of 24.4x.
In plain terms, the market is already paying a premium to both the sector and the fair ratio, which raises the bar for future execution and leaves less room for disappointment. The question for you is whether that premium feels like justified confidence or unnecessary valuation risk.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Westinghouse Air Brake Technologies is mixed, with both upside and downside threads live in the story right now, so move quickly and pressure test the numbers for yourself by weighing up the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Westinghouse Air Brake Technologies?
If you stop with Westinghouse Air Brake Technologies, you risk missing other stocks that suit your style, risk tolerance and income needs across the market.
- Target stronger downside protection by reviewing 30 resilient stocks with low risk scores that may help steady your portfolio when sentiment turns.
- Hunt for mispriced potential with the 16 high quality undiscovered gems that combine solid fundamentals with limited current attention.
- Build a cash flow engine by checking the 7 dividend fortresses that focus on higher yields and durability of payments.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com