
What Hecla Mining Stock's New $500 Million Credit Line Means For Shareholders
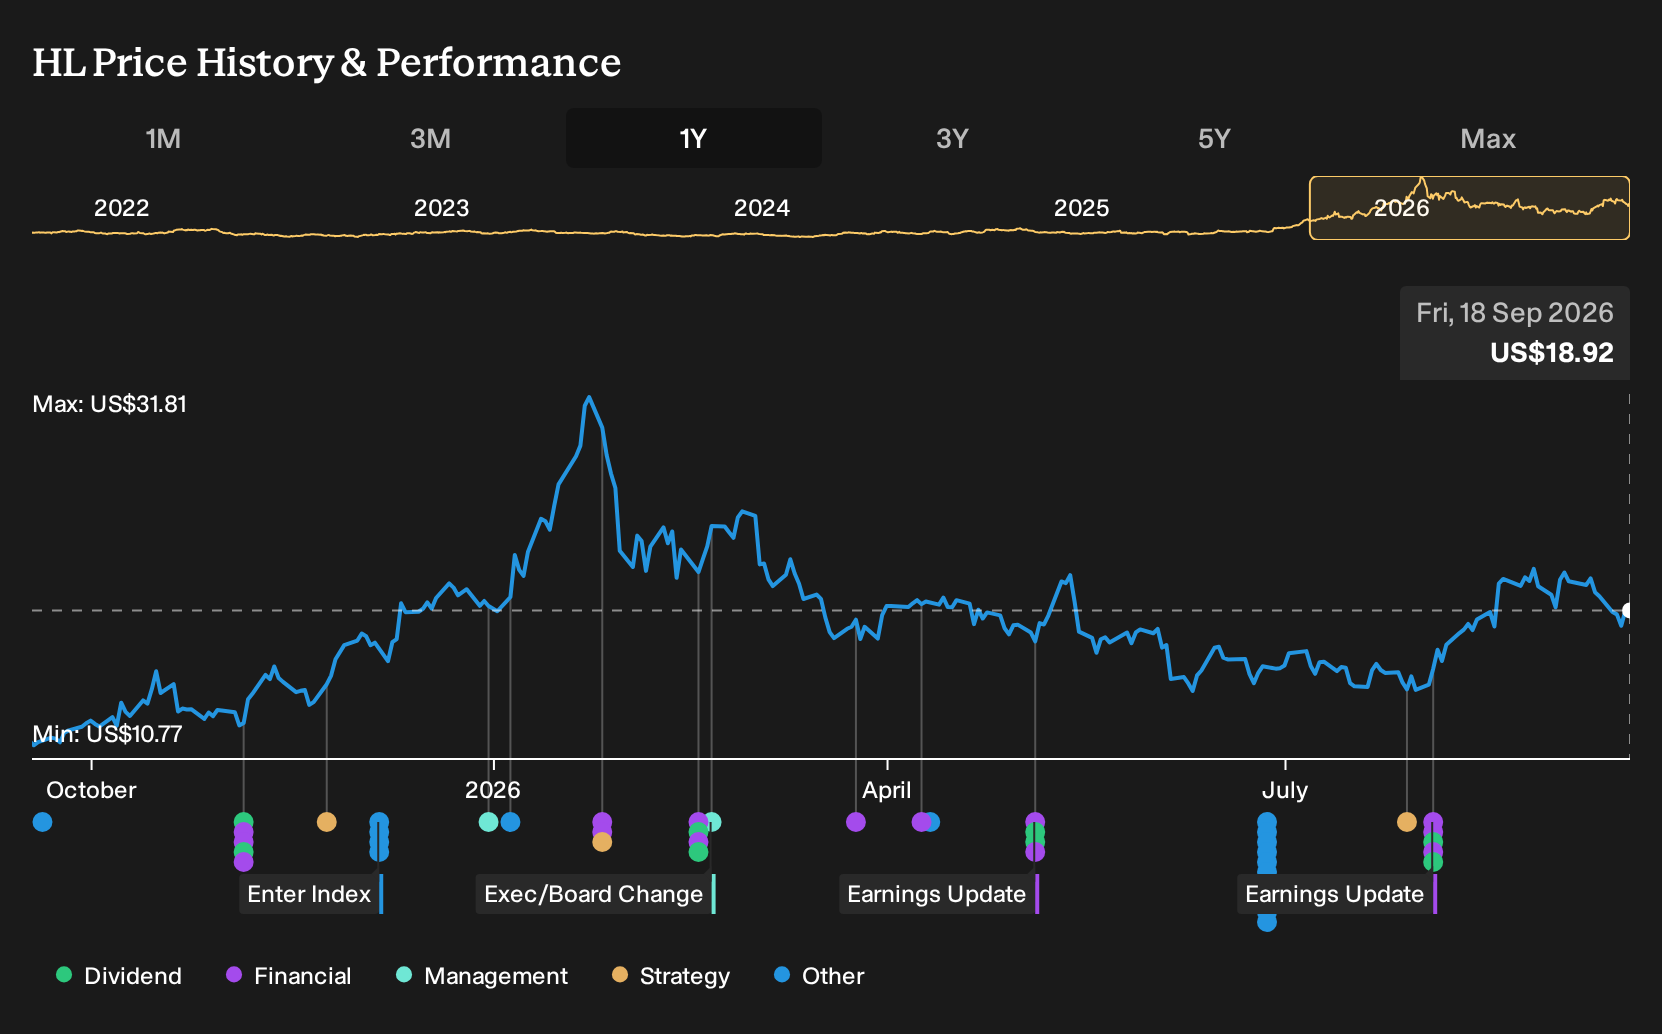
- Hecla Mining entered into a new Credit Agreement in September 2026, securing a US$500 million senior secured revolving credit facility, with an option to increase commitments by up to US$100 million and a maturity in 2030.
- The facility is secured mainly by equity pledges tied to Greens Creek subsidiaries rather than a mortgage over the mine itself. This reshapes how lenders are exposed to the asset while still supporting working capital, capital projects and debt refinancing.
- We will now look at how Hecla Mining's investment narrative could shift given this sizeable new revolving credit facility.
Hecla Mining Investment Narrative Recap
For Hecla Mining, you need to be comfortable with a pure play on precious and base metal production, where operational delivery at Greens Creek, Lucky Friday and Keno Hill does the heavy lifting. The new US$500 million revolving credit facility mainly affects flexibility rather than the core production story. The near term operational catalyst still sits in reliable throughput and cost control at those mines.
The biggest immediate risk remains capital intensity and timing around projects such as Keno Hill, plus any ore grade or permitting setbacks that drag on free cash flow. The fresh facility may soften liquidity pressure if spending runs hot, but it does not remove the possibility of higher costs, delays or future dilution if internal cash generation underperforms.
The credit agreement itself is the most relevant recent announcement. It reshapes Hecla Mining’s funding options by switching security from a full Greens Creek mortgage to equity pledges in subsidiaries, while keeping letters of credit in place. That keeps lenders tied to the Greens Creek complex but on different terms. This matters for how much room management has if conditions tighten.
For you, the lens is simple. This facility can support working capital, capex and potential refinancing while the business works through heavy investment at Keno Hill and ongoing spending on technology and mine development. It may help the company balance the push for efficiency and reserve life against risks such as regulatory costs, ore grade pressures and any need for future equity issuance.
Hecla Mining's analyst storyline points to revenues of US$1.5b and earnings of US$539.3 million by 2029, with revenues assumed to fall 4.6% per year and earnings declining by US$13.2 million from US$552.5 million today.
Uncover why Hecla Mining's fair value indicates a 21% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternative view focuses less on Keno Hill execution risk and more on tighter financing headroom. The most bearish analysts, who were working off an earnings path toward about US$487.2 million and US$1.3b of revenue by 2029 before this new credit facility, see leverage and covenant pressure as the bigger story. You can read their stance as a warning that balance sheet constraints may matter more than consensus expects, and you can use the fresh US$500 million credit line as a prompt to compare several different forecasts before deciding what feels realistic to you.
Explore 4 other Hecla Mining fair value estimates, including one that suggests up to 18% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns can come from taking a different view than the herd, so consider your own analysis carefully.
- A great starting point for your Hecla Mining research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Hecla Mining. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Hecla Mining's overall financial health at a glance.
Looking for more Hecla Mining style investment ideas?
Hecla Mining is only one way to express a view on metals, credit capacity and balance sheet flexibility. If you want to widen your watchlist and pressure test your thesis against other opportunities, the Simply Wall St Screener can help you quickly sort through companies with very different risk and reward profiles.
- If you want potential mispricings with strong fundamentals at the center, start with a curated set of 35 high quality undervalued stocks that might fit a value oriented playbook.
- For income focused portfolios where consistency matters, you can narrow your search to 7 dividend fortresses that could help anchor overall returns.
- When capital preservation ranks higher than chasing maximum upside, filter for 30 resilient stocks with low risk scores and see which businesses match your comfort level.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com