
NRG Energy (NRG) Stock Stays Reasonable After A 184% Run
NRG Energy has had a powerful three year run that now meets a steep pullback, and the gap between those moves is forcing a closer look at whether the current share price still lines up with the company’s earnings power. With the stock slipping in recent weeks after a strong multiyear climb, investors are increasingly focused on what the profit stream behind NRG Energy might reasonably support.
- NRG Energy has delivered a return of 183.6% over the past 3 years, which puts a lot of accumulated optimism on the line when you ask whether recent earnings can support today’s valuation.
- The 1.2 gigawatt gas generation project tied to Texas data center demand may support expectations for future cash generation, but it also concentrates more of the story on how reliably NRG Energy can convert that investment into earnings over time.
- Your read on NRG Energy is one view; the desks covering it have another. See what analysts think NRG Energy's shares could be worth.
The issue now is whether NRG Energy’s current share price is justified by what its earnings record and outlook imply when measured against a Fair Ratio benchmark.
If you want a second reference point while you weigh NRG Energy’s recent swings, a focused stock screen built around 39 power grid technology and infrastructure stocks can be a useful place to start your research.
Does NRG Energy Look Fairly Valued on Earnings?
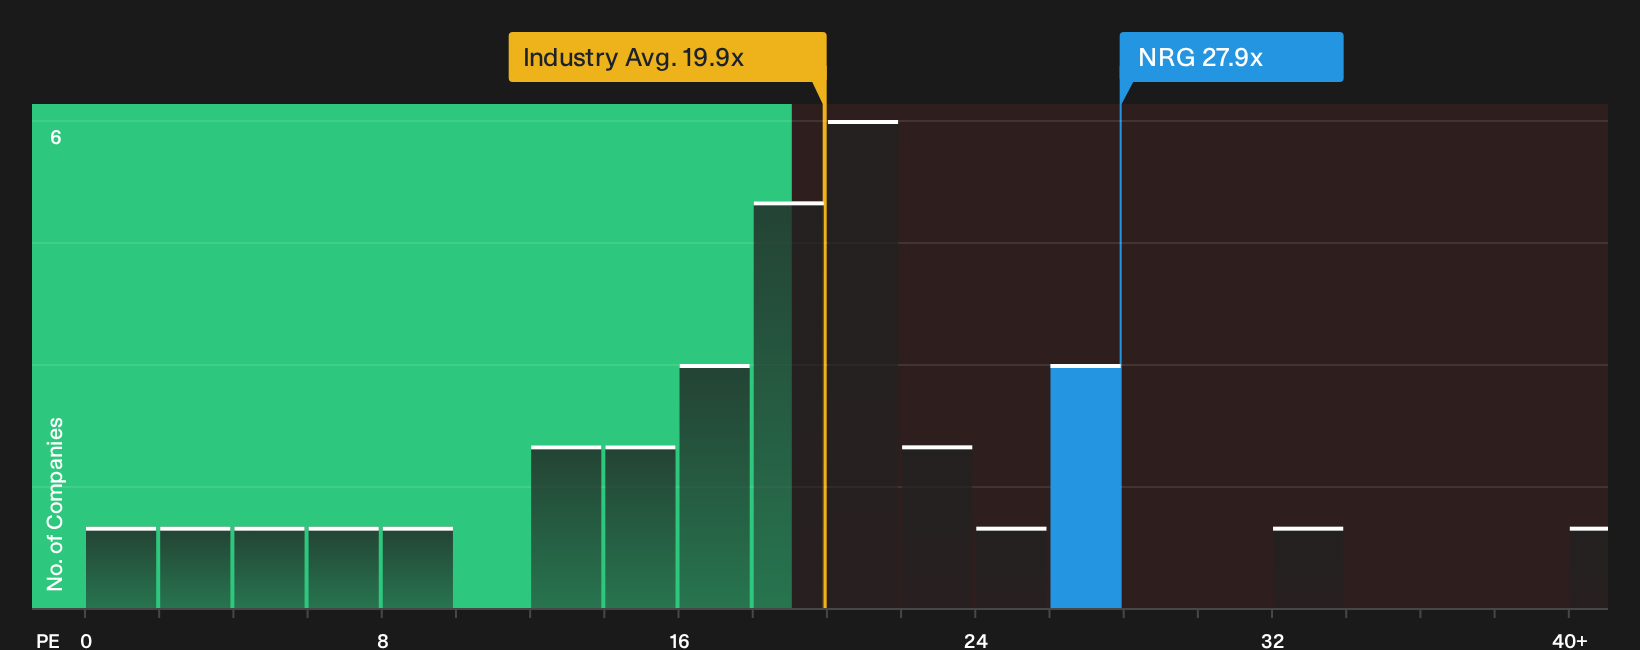
The P/E ratio is a useful way to think about what you are paying for each dollar of NRG Energy’s earnings power. At about 27.9x earnings, the stock is pricing its profit stream higher than the wider Electric Utilities group, where the average P/E is roughly 19.9x, and also above the peer set closer to 15.8x.
Despite the excitement around NRG Energy’s 1.2 gigawatt Texas gas project, which has sharpened attention on future cash flows, the current P/E sits a little below the level suggested by a tailored Fair Ratio that blends the company’s growth profile, margins, size and risk. That points to a valuation that is not stretched against what this project and the broader earnings base might justify. However, the stock still trades at a premium to many utilities, so you would need to be comfortable with execution risk and cyclicality in power markets at this price. Explore the numbers behind NRG Energy's P/E valuation.
The NRG Energy Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for NRG Energy pick up where the valuation puzzle leaves off by spelling out which paths for growth, margins and earnings would need to play out for the stock to end up worth meaningfully more or less than today’s price on the Community page. Each scenario links its number to a clear view on where NRG Energy's growth, profitability and risks might head next, so you can revisit those assumptions as fresh information comes in.
One of the top community narratives on NRG Energy: 45% undervalued
"Strong positioning for long-term recurring revenue growth through data center demand, electrification trends, and premium-margin power agreements..."
Discover why this Narrative puts NRG Energy at 45% undervalued.
For NRG Energy, the sticker price is only half the story
The real question is who is steering NRG Energy and what kind of rewards they collect for doing it, because that alignment can tilt the whole investment case. See who runs NRG Energy and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com