
Cheniere Energy (LNG) Wins Corpus Christi Technology Rollout, Is The Stock Still Cheap?
BASF Catalysts LLC reported that Cheniere Energy (LNG) has commissioned Durasorb LNG MAX technology across several liquefaction trains at its Corpus Christi facility, highlighting operational reliability as a new factor for evaluating the stock.
For context, Cheniere Energy’s share price is US$268.34, with the stock easing over the past week and month but still showing a 16.24% 90 day share price return and a 35.66% year to date share price return. Longer term total shareholder returns of 17.05% over one year and 197.93% over five years point to a story that investors have rewarded over time, even as recent quarterly losses and ongoing LNG price volatility have reminded the market that execution and risk management remain firmly in focus.
Scan for other LNG and energy infrastructure plays that may be tightening operations and cash flows in a similar way to Cheniere Energy by reviewing our hand picked list of solid balance sheet and fundamentals (23 results).
Cheniere Energy now trades near US$268 while analyst estimates cluster closer to US$310 and some intrinsic value models point lower instead. Where does a fair entry actually fall within that spread?
Most Popular Narrative: 12% Undervalued
On the most followed narrative, Cheniere Energy screens as undervalued, with a fair value of about $304 against the recent $268.34 share price. This view places more weight on long term contracts and expansion than the current quote appears to reflect.
Cheniere's ongoing expansion of LNG production capacity, including the final investment decision and construction of Corpus Christi Midscale Trains 8 & 9, along with advancing permitting for future trains, positions the company to capture increasing global demand for LNG. This directly supports upward revisions in long-term revenue and EBITDA as these projects come online. New long-term supply agreements, such as the recently announced 1 mtpa SPA with JERA (the first with a Japanese counterparty), reflect the growing appeal of U.S. LNG for energy security and diversification, particularly in Europe and Asia, and underpin highly visible, stable future cash flows and margin stability.
See why 66 investors see Cheniere Energy as 12% undervalued.
Result: Fair Value of $304.38 (UNDERVALUED)
Still, Cheniere Energy faces two clear pressure points: a potential LNG oversupply that weighs on contract economics and large expansion spending that could strain future cash generation.
Find out about the key risks to this Cheniere Energy narrative.
Another View: What Cheniere Energy’s P/E Is Really Telling You
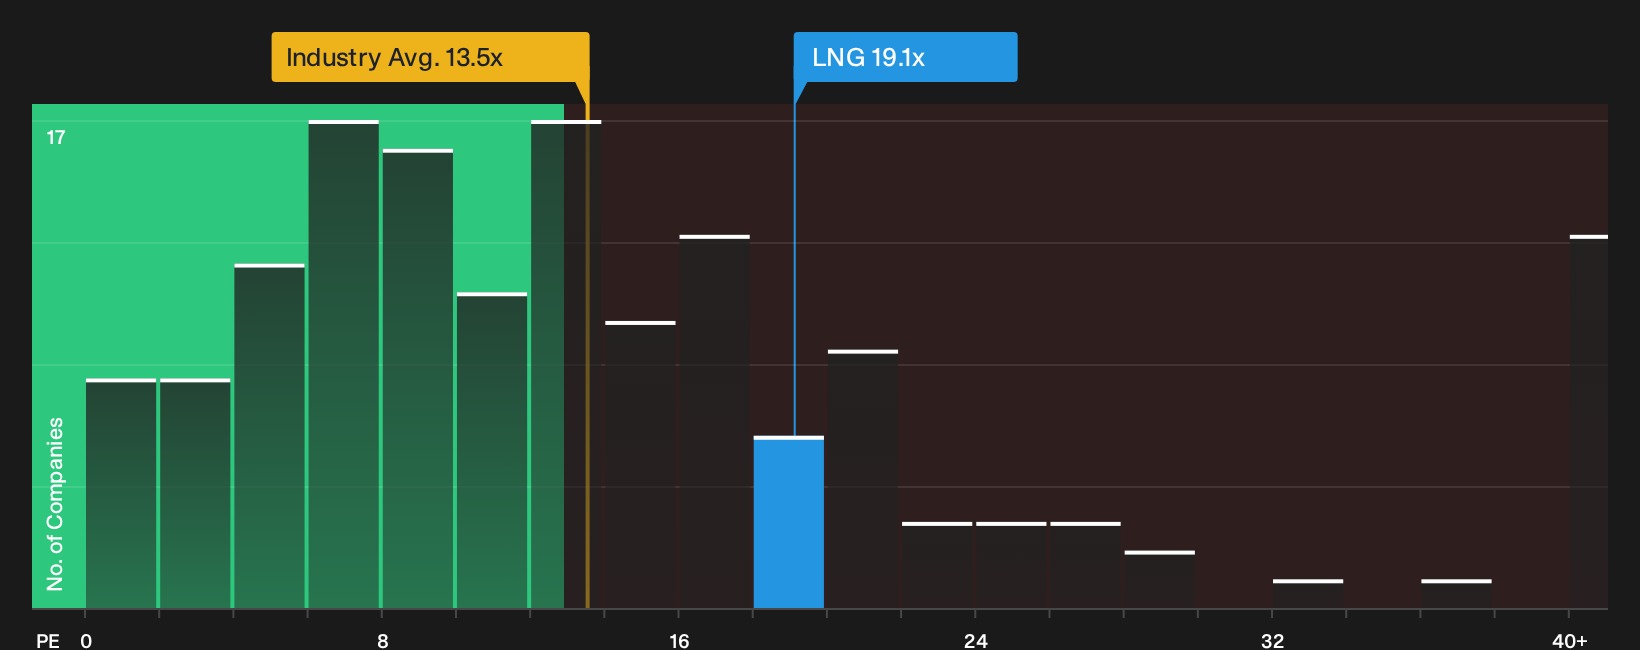
On the flip side of the narrative fair value of about $304 for Cheniere Energy, the current P/E of 19.1x looks less forgiving. It is higher than the US Oil and Gas industry at 13.5x and slightly above peers at 18.9x, yet below the fair ratio of 22.4x that the market could move toward. That mix of premium to the sector but discount to the fair ratio points to valuation risk if expectations cool, as well as potential upside if earnings keep tracking analyst forecasts. Which side of that trade you focus on most will depend on your portfolio and risk tolerance.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Cheniere Energy can feel confusing, so review the numbers yourself and move quickly to form your own judgment using 1 key reward and 2 important warning signs.
Looking for more Cheniere Energy style investment ideas?
Do not stop with Cheniere Energy. Broaden your watchlist now by scanning other opportunities that share similar financial discipline, income potential, or resilience traits.
- Chase upside in quality by reviewing our hand picked 35 high quality undervalued stocks with strong fundamentals that the market may not be fully pricing yet.
- Strengthen your income stream by focusing on companies in the 7 dividend fortresses that pair higher yields with robust underlying businesses.
- Dial down portfolio stress and target durable performance using the 30 resilient stocks with low risk scores that emphasizes resilient balance sheets and steadier risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com