
Is Aeon (TSE:8267) Cheap Or Pricey On Conflicting Fair Value Signals?
Aeon (TSE:8267) has attracted fresh attention after its recent share performance, with the price closing at ¥1,313.5 and short term returns under pressure over the past week and month.
For context, Aeon’s share price return is down 2.56% over the past day and 5.20% over the past month, while the year to date share price return has fallen 47.14%. However, the 5 year total shareholder return of 38.17% shows that long term holders have still seen a positive outcome despite the recent loss of momentum.
Scan beyond Aeon and stress test your watchlist against our curated 17 high quality undervalued stocks that combine share price pressure with stronger financial underpinnings.
Aeon now trades well below its year to date starting level after a steep 47.14% decline, yet long term holders still sit on gains. Does that reset invite an earlier entry, or argue for patience until the valuation picture is clearer?
Most Popular Narrative: 6% Undervalued
Aeon’s most followed valuation storyline puts fair value around ¥1,396, which sits modestly above the latest close at ¥1,313.5. That gap is small, yet the reasoning behind it leans heavily on how the retailer handles demographic strain, digital retail, and overseas risk.
Intensifying consumer price sensitivity in Japan, coupled with an aging and shrinking population, is expected to suppress long-term domestic consumption growth for Aeon. This demographic headwind will limit revenue growth potential and increase competitive pressures on both top-line and net margins.
See why 4 investors see Aeon as 6% undervalued.
Under this narrative, analysts link their fair value of about ¥1,395.56 to revenue growth assumptions of roughly 4.2% a year, a net profit margin near 1.0%, and a future P/E of 38.2x, all discounted back using a 6.27% rate. The framing implies Aeon needs to sustain earnings expansion and justify a premium valuation multiple relative to the broader JP Consumer Retailing sector for that target to hold.
For readers, the key question is whether those inputs feel reasonable given Aeon’s mix of mature domestic stores, higher risk ASEAN exposure, and ongoing investment in digital and private label initiatives. If the assumptions look demanding, the current discount to the narrative fair value may appear less generous than the 6% headline suggests.
Result: Fair Value of ¥1,395.56 (UNDERVALUED)
Still, if Aeon’s digital tools keep lifting productivity and its higher margin private label ranges continue to scale, the cautious fair value narrative could be challenged.
Find out about the key risks to this Aeon narrative.
Another View on Aeon’s Valuation
That 6% “undervalued” story sits awkwardly beside a tougher message from our DCF work. On a future cash flow basis, Aeon at ¥1,313.5 screens as expensive, with the share price well above an estimated cash flow value of about ¥331.19. That is a large gap. Does it point to over-optimism on earnings durability or a blind spot in the model assumptions?
For readers who want to see how that cash flow estimate is built line by line, the SWS DCF model breaks out each step in detail, from projected profits to the discount rate inputs. Look into how the SWS DCF model arrives at its fair value.
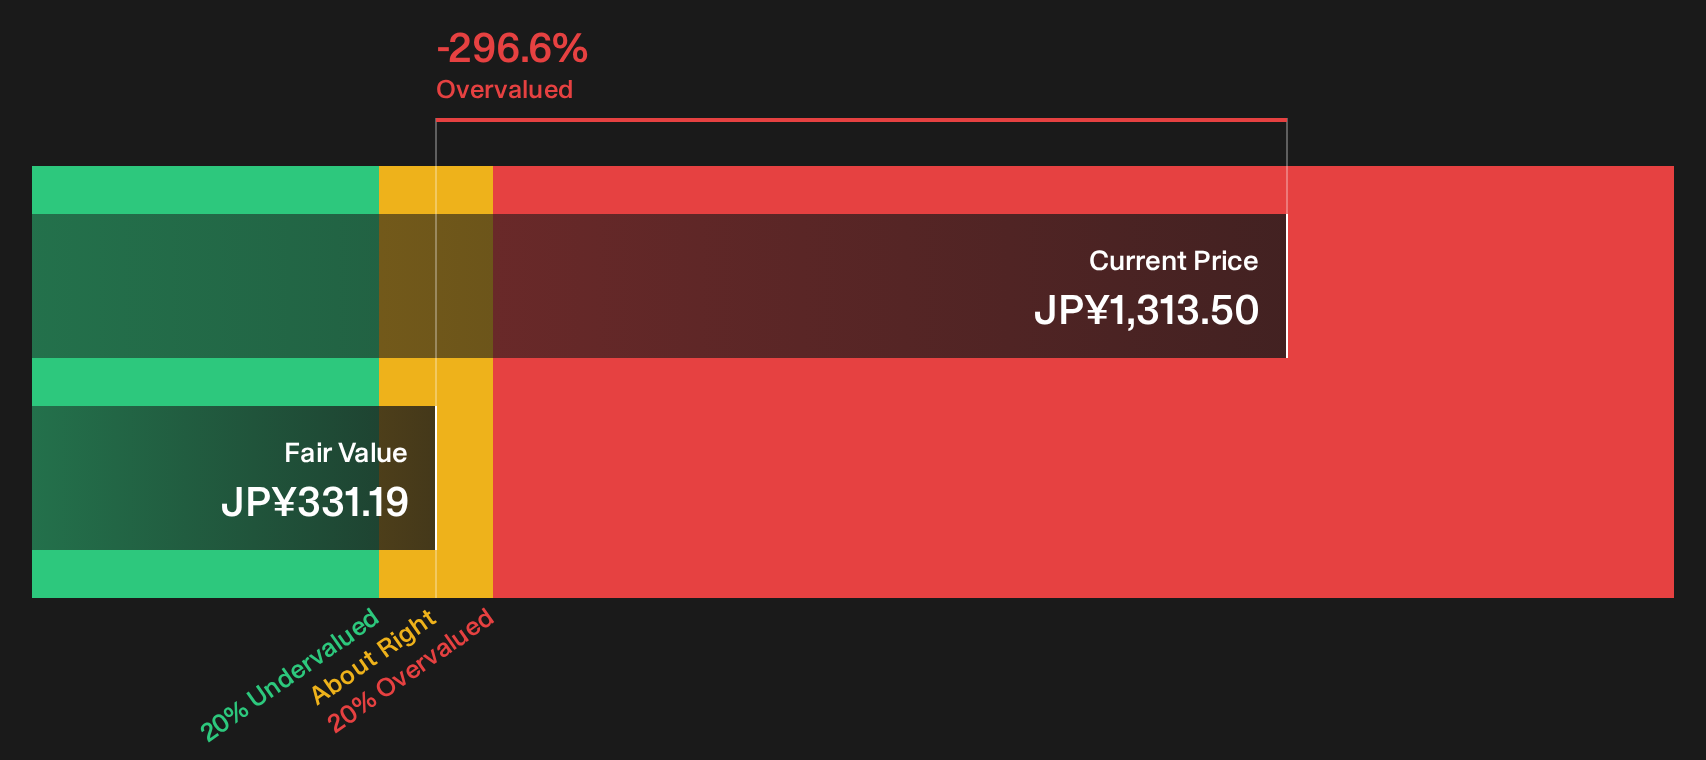
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Aeon for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around Aeon’s valuation and future cash flows can be confusing, so move quickly, review the underlying data, and weigh both the 2 key rewards and 1 important warning sign.
Looking for more ideas beyond Aeon?
If Aeon has sharpened your thinking, do not stop there. Broader context from other opportunities can often change how today’s price moves feel.
- Target potential high return opportunities at the aggressive end of your watchlist by reviewing the 1 elite penny stocks with strong financials.
- Strengthen the quality bar in your portfolio by focusing on companies with strong finances using the list of solid balance sheet and fundamentals (21 results).
- Hunt for future winners that the market has not fully focused on yet by scanning the 75 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com