
Envista Holdings (NVST) Heads To A Healthcare Conference, Is The Stock Still A Bargain?
Envista Holdings (NVST) is set to present at the 2026 Global Healthcare Conference in New York on September 15, drawing fresh attention to a stock that screens as both oversold and value oriented.
Recent trading has been rough for Envista Holdings, with the share price down 8.61% over the last week and 14.15% over 30 days, yet still showing a 7.65% year to date share price gain and an 11.56% total shareholder return over twelve months. This points to fading short term momentum after a stronger year and aligns with the recent oversold readings as investors reassess both growth potential and risk.
Scan other value driven setups around Envista Holdings with a curated list of 35 high quality undervalued stocks that share solid cash flows and balance sheet strength.
Envista Holdings now trades at a steep implied discount, with a roughly 50% gap to one intrinsic value estimate and about 30% to the analyst target. Is that a genuine bargain, or is the market pricing in real business risk?
Most Popular Narrative: 21% Undervalued
Envista Holdings last closed at $23.35, while the most widely followed narrative sets fair value closer to $29.69. This frames today’s discount through the lens of execution, margins, and buybacks over the next few years.
Ongoing cost reductions (notably 15% G&A reduction in the first half), coupled with operational optimization and unit cost reductions (especially within Spark), are catalysts for sustained margin improvement and future EPS growth, as scale and digital adoption continue.
See why 2 investors see Envista Holdings as 21% undervalued.
Result: Fair Value of $29.69 (UNDERVALUED)
Still, the Envista Holdings story can break if China’s volume based procurement continues to pressure pricing or if tariffs and FX swings continue to erode profitability.
Find out about the key risks to this Envista Holdings narrative.
Another View: Envista Holdings Through The P/E Lens
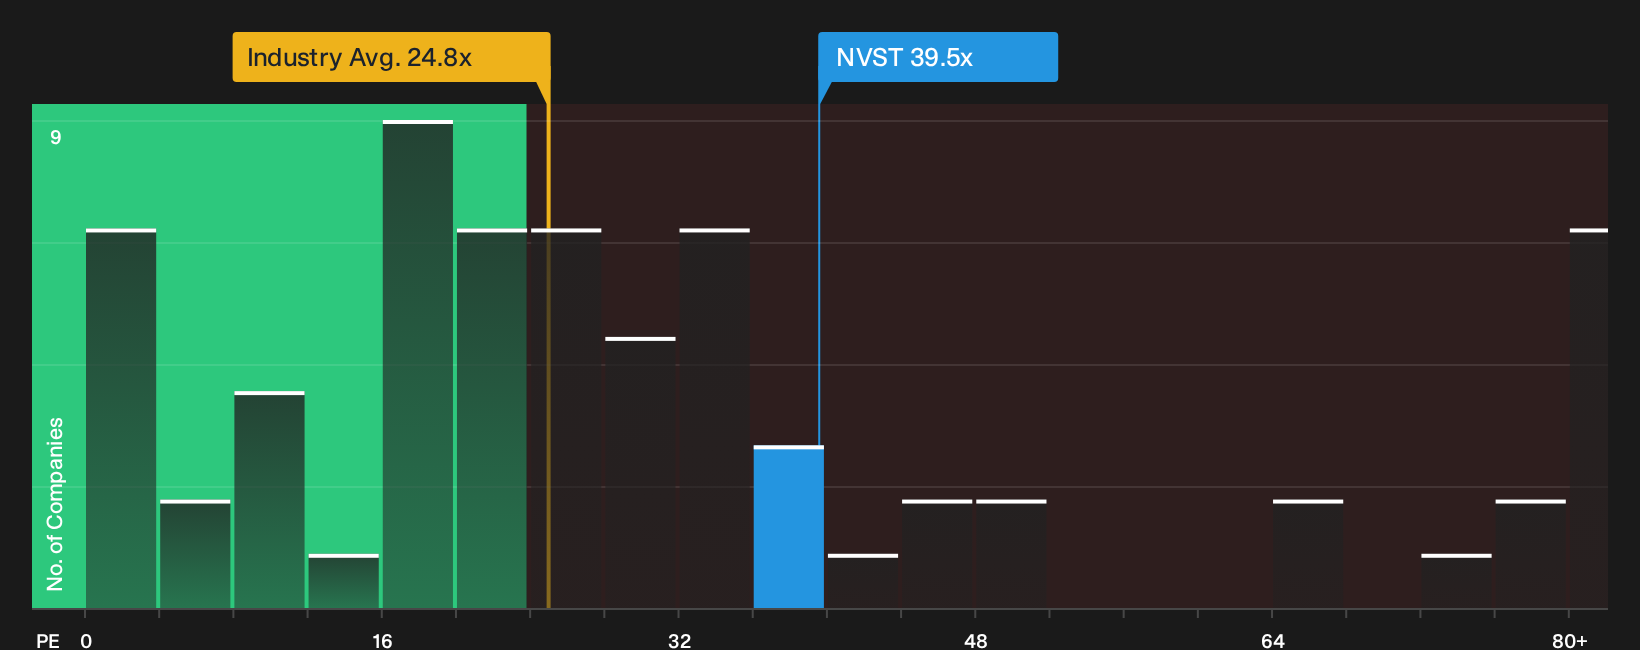
The SWS DCF model points to upside for Envista Holdings, yet the P/E picture looks far less forgiving. NVST trades on 39.5x earnings, which is richer than both the US Medical Equipment sector at 24.8x and peers at 25x. It is also above a 29x fair ratio that the market could move toward over time.
If that gap closes through a lower valuation multiple rather than stronger profits, investors face meaningful downside risk to today’s premium. The key question is whether earnings can grow fast enough to justify paying well above both the industry and the fair ratio, or whether patience is better spent elsewhere.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Seen enough mixed signals around Envista Holdings to feel torn on what to do next? Pressure test the numbers yourself and weigh them against the 4 key rewards
Looking for more investment ideas beyond Envista Holdings?
If Envista Holdings has you thinking more broadly about where to put fresh capital, widen your funnel and stress test your approach with a few targeted screeners.
- Target stability first by reviewing a list of solid balance sheet and fundamentals (23 results) that can help you focus on businesses with stronger fundamentals and less fragile finances.
- Hunt for value by scanning a 16 high quality undiscovered gems that may not be widely followed yet but still show robust underlying metrics.
- Dial down risk by filtering for a 30 resilient stocks with low risk scores designed to highlight companies with more resilient profiles when markets turn choppy.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com