
3 Financial Stocks Tied To The Hidden AI Data Center Funding Boom
The AI gold rush is no longer just about chips and cloud giants. It now runs through obscure credit guarantees and residual value promises that quietly fund those data centers. That shift creates a fresh set of winners and risks for anyone looking at financial stocks exposed to this news. This article unpacks the story and then highlights 3 stocks that appear to be connected to this AI financing wave.
The three stocks in focus below are just a sample from this theme, while the full screen surfaced 37 more listed financial players with equally strong stories that are not covered here. To go straight to the full Specialist Credit & Insurance Providers to Structured AI Infrastructure Finance universe, analyze the signals, and identify your highest conviction ideas, head into the Specialist Credit & Insurance Providers to Structured AI Infrastructure Finance screener.
eGuarantee (TSE:8771)
Overview: eGuarantee runs credit guarantee and securitization services in Japan, absorbing default risk on corporate and financial receivables for a fee.
Operations: eGuarantee generates all its ¥11,087 million in revenue from credit guarantee activities in Japan, tightly focused on domestic receivables risk.
Market Cap: ¥79.5 billion
eGuarantee connects to the AI financing theme because it packages and transfers credit risk, including structures similar to residual value guarantees used around data centre projects. The business offers high margins and a 4.7% yield but relies entirely on external borrowing, so the appeal of its guarantee model ultimately hinges on how that funding channel behaves if one unseen pressure tightens.
If that funding channel ever shifts, the eGuarantee financial health report shows how eGuarantee’s balance sheet might absorb pressure before it reaches shareholders.
Federal Home Loan Mortgage (FMCC)
Overview: Federal Home Loan Mortgage, or Freddie Mac, buys US home loans, bundles them into securities, and guarantees investor payments.
Operations: Freddie Mac generates about US$21.3b from Single-Family, including capital markets activity, and US$3.3b from Multifamily, all within the United States.
Market Cap: US$15.2b
Federal Home Loan Mortgage sits in this AI-adjacent screener because its securitization and guarantee machinery already runs at the kind of scale Big Tech is now chasing for data center financing, applied to housing credit instead of servers and chips.
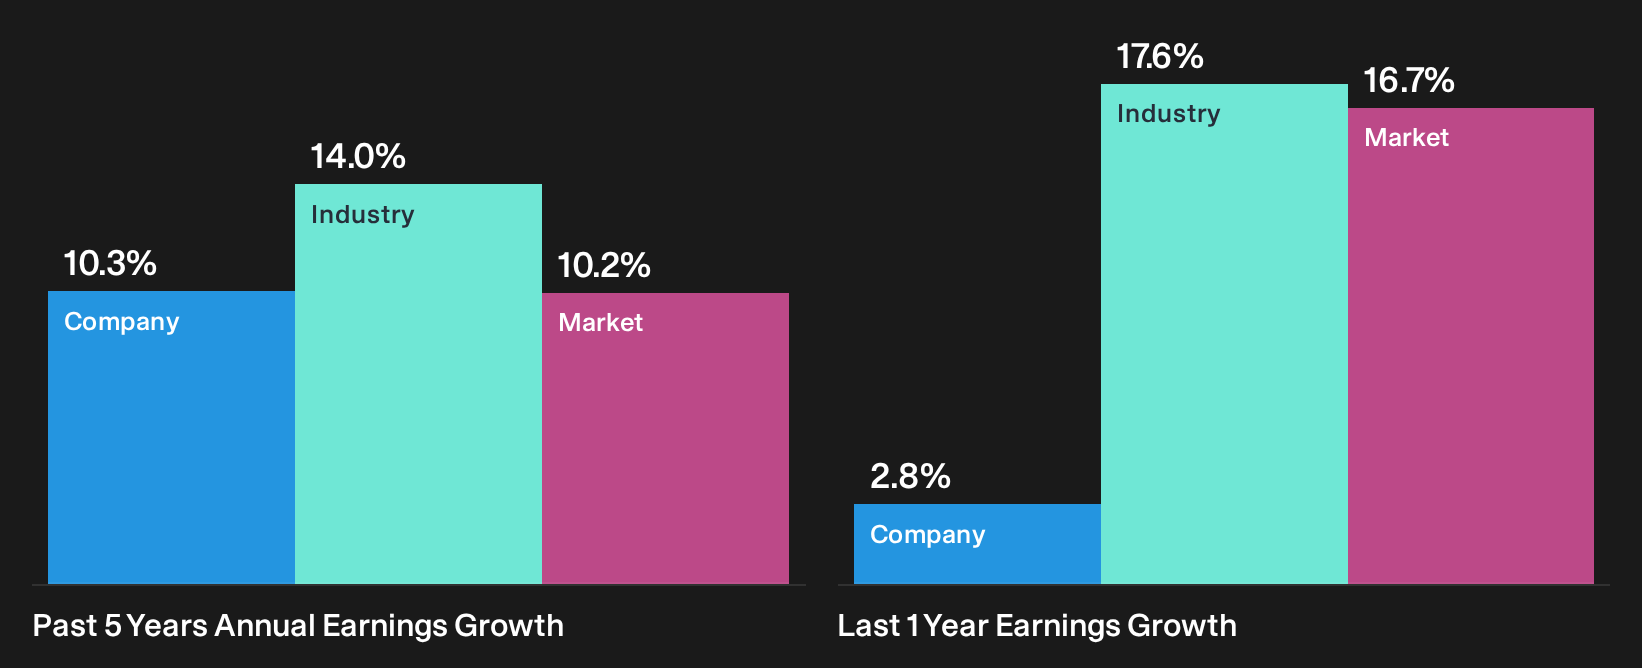
"The shift in multifamily toward fully guaranteed securitizations, with nearly all of the US$24b securitized in the quarter carrying guarantees and a higher average guarantee fee rate of 58 basis points, points to a business mix that can support net interest income and earnings quality.
What happens if one key assumption behind that guarantee-heavy mix shifts and pricing or volumes move faster than investors expect?
If that mix does start to shift faster than expected, the full narrative for Federal Home Loan Mortgage shows where pricing power, policy risk, and AI-adjacent financing could be quietly decoupling.

ICG (LSE:ICG)
Overview: ICG is a London based alternative asset manager that provides private credit, structured capital and real assets financing to mid sized companies worldwide.
Operations: ICG generates £897.7 million from Fund Management Company activities, £42.5 million from its Investment Company and £33.8 million from consolidated entities, mostly across Europe and North America.
Market Cap: £5.1 billion
ICG matters in this screener because it channels institutional money into complex private credit and securitised structures that can underpin large infrastructure financing, including AI related projects, without needing a traditional bank balance sheet.
"Although the tilt towards higher returning strategies in structured capital, secondaries and real assets has lifted the weighted average management fee rate to just under 1%, the move into more complex, higher barrier products increases execution risk. This could limit the pace at which new mandates convert into fee earning AUM and may cap future revenue growth."
What happens if one assumption about how quickly that higher fee, higher complexity pipeline turns into durable margins starts to break?
That is where the real story starts. Read the full narrative for ICG to see whether ICG’s fee engine is quietly accelerating or if complexity is masking fragility.

Seeking Alternatives Before The Crowd?
Fresh opportunities move first. Breakout stories gain momentum while they are still under the radar for now, and information edge drops fast, so act now.
- Target income ideas with yields that can anchor a portfolio by scanning the 14 dividend fortresses before payout momentum is fully reflected in market pricing.
- Look for balance sheets designed to handle shocks by reviewing the list of solid balance sheet and fundamentals (21 results) while it still feels overlooked.
- Follow the companies helping build tomorrow’s grid and serving data center demand using the 39 power grid technology and infrastructure stocks before infrastructure spending trends are widely recognized.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com