
How Investors Are Reacting To Cliffs Stock $1b Plant Upgrade
- Cleveland-Cliffs confirmed a US$1b modernization program for its Middletown Works plant in Ohio, backed by a US$500m U.S. Department of Energy grant and scheduled over four years while production continues.
- The Middletown upgrade focuses on addressing aging, carbon intensive assets and aims to improve efficiency, reliability, and the sustainability profile of a key U.S. steel facility.
- We will examine how Cleveland-Cliffs' investment story is influenced by this US$1b Middletown modernization and the accompanying federal funding support.
Cleveland-Cliffs Investment Narrative Recap
For Cleveland-Cliffs, the core belief is that a vertically integrated, tariff shielded flat-rolled producer can turn a loss making profile into consistent cash generation as domestic steel demand from autos and infrastructure holds up. The Middletown modernization fits that view by targeting an aging, carbon intensive asset, but the earnings impact will be gradual and spread over several years.
The near term swing factor still sits with operating leverage and balance sheet pressure. Debt is not well covered by operating cash flow, and the group remains unprofitable with a reported loss of US$866.0m. The largest risk is that free cash flow stays tight while capital needs for maintenance and decarbonization rise.
The US$1b Middletown Works plan, backed by a US$500m Department of Energy award, is the announcement that matters most for this story. It goes directly to the criticism that Cleveland-Cliffs relies on older blast furnace technology that could face higher regulatory and customer costs as steel buyers look for lower carbon supply.
Execution around this upgrade becomes a key operational catalyst. Investors will likely watch whether Cleveland-Cliffs can keep production online, avoid cost overruns, and translate the spend into better efficiency and reliability. With earnings per share for the upcoming quarter projected to rise sharply year over year, follow through in reported results will help show whether this capital program and broader footprint work are gaining traction.
Cleveland-Cliffs Forecasts Tied To Middletown Execution
Cleveland-Cliffs' modernization push at Middletown plugs into a bigger set of expectations that analysts have sketched out for the next few years. Revenue is modeled to rise by 6.6% a year, profit margins are projected to move from a current loss making 4.5% margin to a positive 4.9%, and earnings are forecast to shift from a reported loss of US$866.0m to US$1.1b by 2029. That swing in profitability, if it plays out, would need to be supported by smoother operations at key plants such as Middletown, not just by pricing or tariff support.
The earnings path implied here is sizable. Moving from a loss of US$866.0m to US$1.1b represents a US$1.966b improvement in absolute profit, which is a large jump even spread across several years. Analysts also assume that shares on issue climb by about 7.0% per year for the next three years, so per share progress would need to keep pace with both higher absolute earnings and some dilution.
Valuation work around Cleveland-Cliffs incorporates these inputs into a 2029 snapshot. Consensus implies that by that year, revenue reaches US$23.2b and earnings land at US$1.1b, paired with a P/E of 10.4x if those forecasts prove accurate. That multiple sits below the cited 21.1x for the wider US metals and mining group, so the story rests less on paying a premium and more on the idea that the profit pool itself grows meaningfully from today’s loss making base.
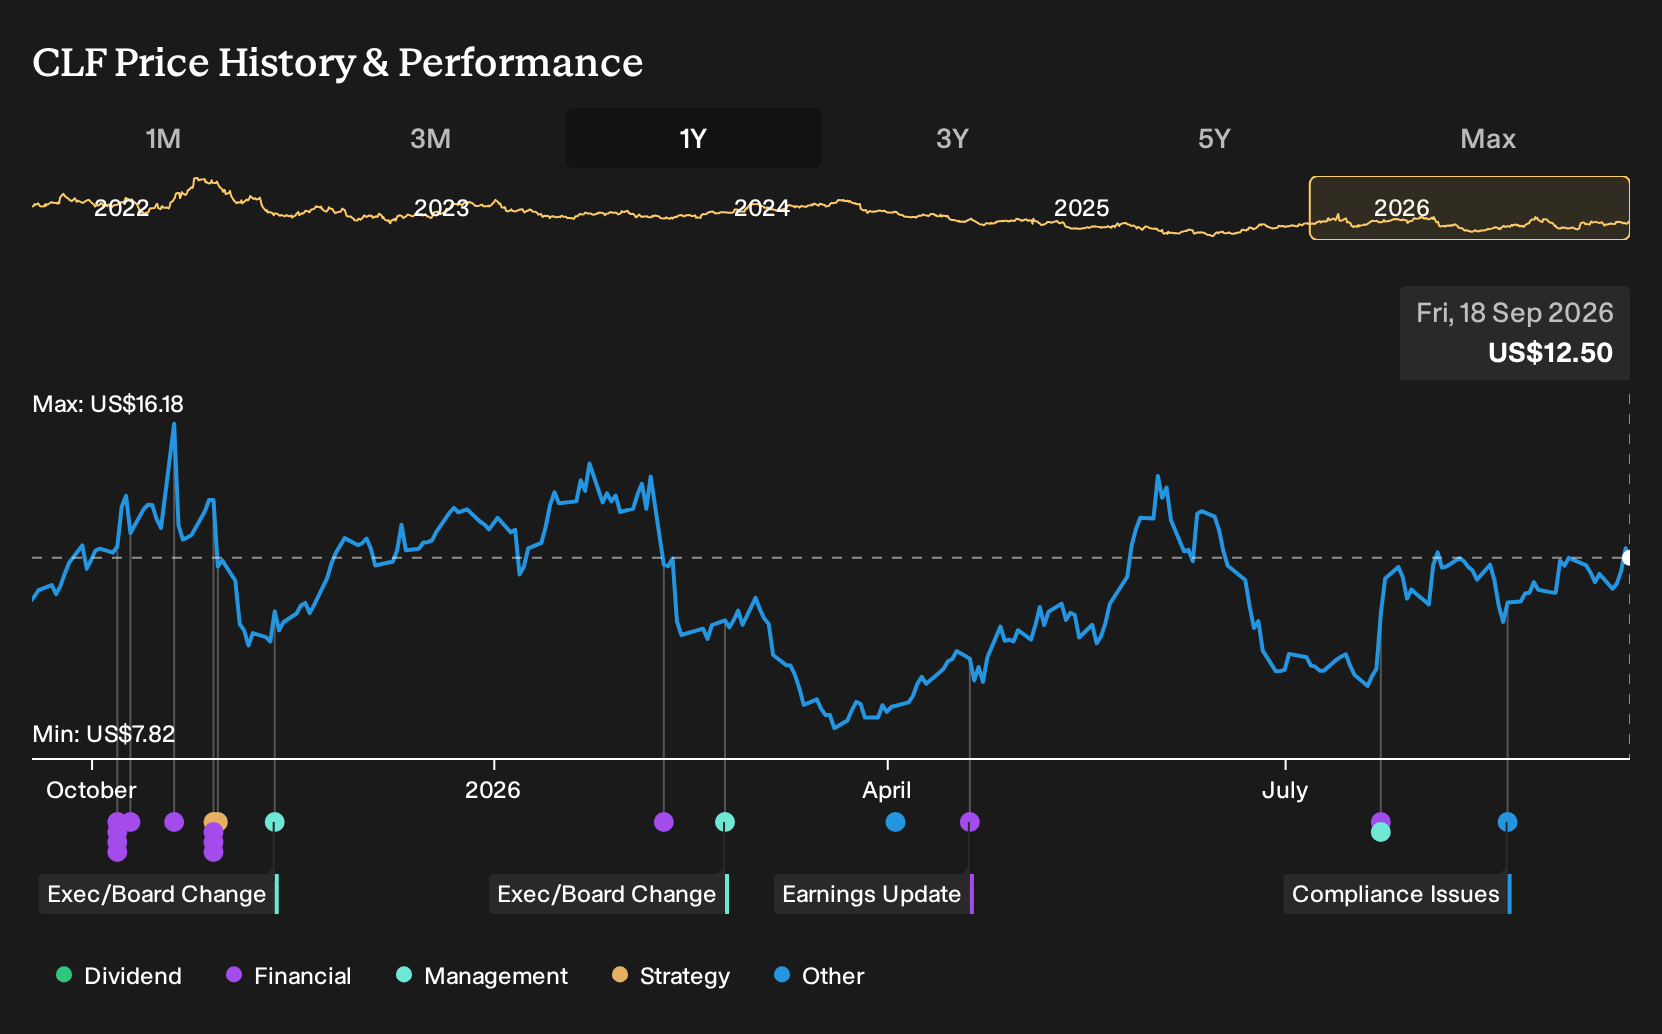
Price targets then sit on top of those operating assumptions. Analysts cluster around a US$12.0 target, with the highest at US$15.0 and the lowest at US$10.0, versus a current share price of US$12.5. With the consensus sitting about 4.2% under the market price, the message is that the stock is broadly viewed as fairly valued on these projections, not as a clear bargain or clear outlier.
The Middletown Works program becomes one of the practical tests of these forecasts. A US$1b upgrade, supported by a US$500m U.S. Department of Energy grant, has the potential to support that shift in margins if it cuts outages and trims unit costs. It also introduces execution variables such as timing, capital discipline, and any impact on production volumes while the work is carried out across four years.
Cleveland-Cliffs' narrative projects revenue of US$23.2b and earnings of US$1.1b by 2029. This rests on the assumption of 6.6% yearly revenue growth and an earnings improvement of about US$1.966b from current earnings of a reported loss of US$866.0m.
Uncover why Cleveland-Cliffs' fair value indicates a 4% potential downside to its current price, representing a valuation premium that may not hold.
Exploring Other Perspectives
You can also consider a more optimistic angle that focuses on Cleveland-Cliffs' earnings power rather than tariff risk. The most bullish analysts were already sketching out about US$22.8b of revenue and US$814.1m of earnings by 2029, before this Middletown news. That gap in expectations shows how widely views can differ, so explore several scenarios for yourself.
Explore 3 other Cleveland-Cliffs fair value estimates, including one that suggests as much as 123% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Cleveland-Cliffs research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Cleveland-Cliffs. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cleveland-Cliffs' overall financial health at a glance.
Looking For More Ideas Beyond Cleveland-Cliffs?
If you like the Cleveland-Cliffs story but want a broader watchlist, the Simply Wall St Screener can help you focus on other opportunities that fit different risk and return profiles.
- For investors hunting for quality at a discount, scan a curated set of 35 high quality undervalued stocks that pair strong fundamentals with more modest pricing.
- If capital preservation and steadier profiles matter most to you, filter for 30 resilient stocks with low risk scores that score well on resilience metrics and business stability.
- Income focused readers can build a shortlist of cash generators by reviewing 7 dividend fortresses that combine higher yields with durable payout histories.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com