
Why NIQ Global Intelligence (NIQ) Is Back In The Spotlight
NIQ Global Intelligence (NIQ) just rolled out its Digital Purchase GeoAudiences tool across five major European markets, giving advertisers fresh purchase based signals tied to real digital shopping behavior.
NIQ Global Intelligence has been on a sharp run recently, with a 90 day share price return of 126.81% and a year to date gain of 15.27%. However, the 1 year total shareholder return is a more modest 6.62%, suggesting the recent momentum reflects shifting expectations around its new product rollouts and data capabilities rather than a longer track record of strong overall investor returns.
Capitalize on NIQ Global Intelligence’s surge in data driven advertising by scanning a curated set of 88 AI infrastructure stocks that could benefit from similar AI and analytics tailwinds.After a 126.81% ninety day surge and with NIQ Global Intelligence trading below both analyst targets and intrinsic estimates, is the current share price a bargain on revised expectations, or already crowding fair value?
Most Popular Narrative: 7.6% Undervalued
NIQ Global Intelligence last closed at $18.19, while the most followed narrative anchors fair value at $19.69. This frames the recent rally as a catch up move rather than pure euphoria.
Growing adoption of AI agents in commerce, with external research pointing to very large agent mediated revenue pools and NIQ already positioning its Commerce Intelligence and product content as the data layer those agents rely on, can create new usage based revenue streams and support subscription growth.
See why 2 investors see NIQ Global Intelligence as 8% undervalued.
This storyline rests on a discount rate of 11.58%, which is used to pull those projected earnings and cash flows back into today’s dollars and arrive at that $19.69 mark. The gap between that figure and the current $18.19 share price is not huge, so the market is already pricing in a meaningful part of the AI and automation thesis.
The same narrative also flags real risk. NIQ Global Intelligence is still loss making today with a reported net loss of $351.4 million on $4.39b of revenue, and its 1 year total shareholder return of 6.62% trails the broader US market while beating the US Media sector. That mix of improving expectations, but uneven recent returns, helps explain why the most widely followed view treats the stock as modestly undervalued rather than deeply mispriced.
Result: Fair Value of $19.69 (UNDERVALUED)
Still, the AI centric thesis around NIQ Global Intelligence can unravel if large platforms rely on alternative data sources or if clients increasingly build in house commerce intelligence instead.
Find out about the key risks to this NIQ Global Intelligence narrative.
Another View On NIQ Global Intelligence’s Valuation
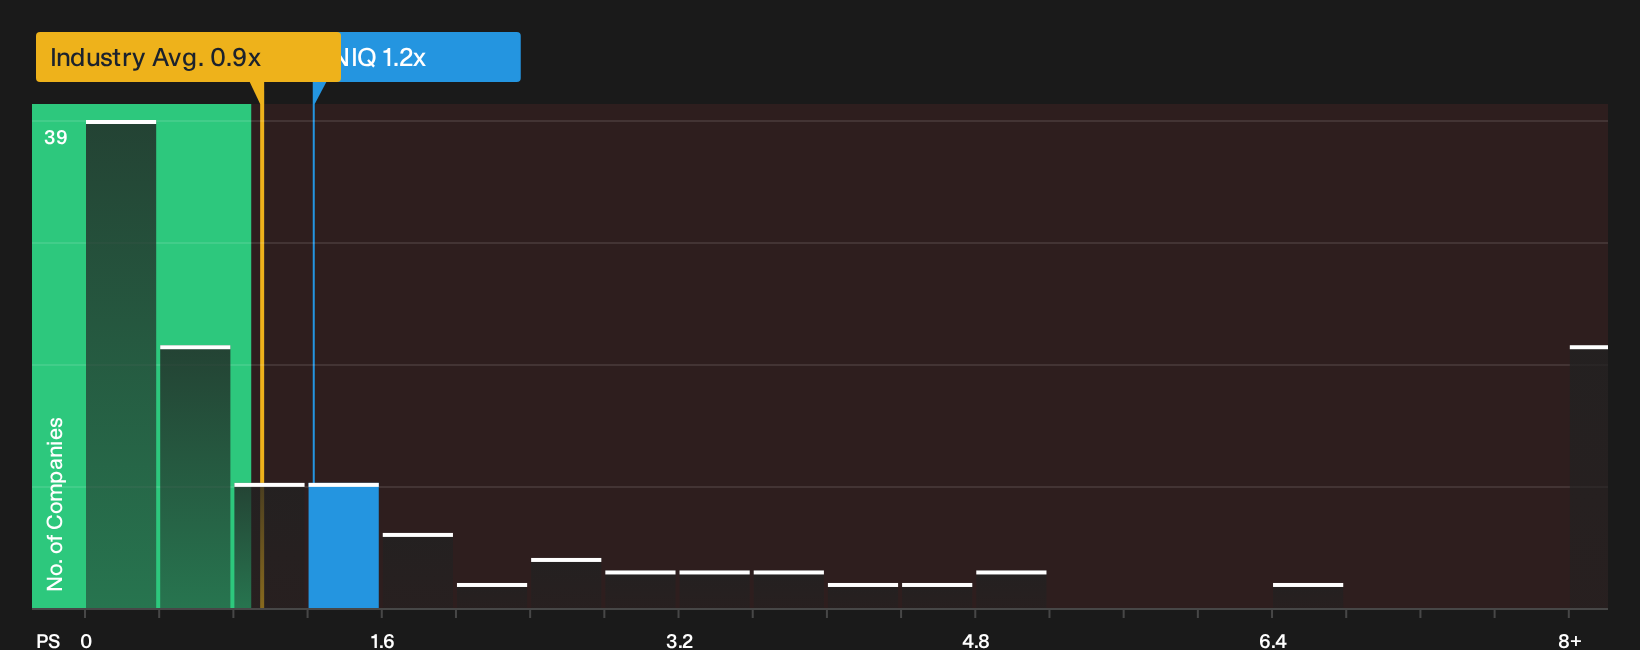
The earlier narrative leans on discounted future cash flows and analyst targets to argue NIQ Global Intelligence is modestly undervalued. A simple P/S check tells a different story. NIQ trades at 1.2x sales, richer than the US Media sector at 0.9x, even if it sits below peers at 3.3x and a fair ratio of 1.6x. That mix points to some valuation support, but leaves an obvious question for investors: Is the market more likely to move NIQ toward sector pricing or toward the higher fair ratio?
See what the numbers say about this price in the valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on NIQ Global Intelligence after all this. Use the data, move quickly, and pressure test both sides by reviewing the 3 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond NIQ Global Intelligence?
You have already done the work on NIQ Global Intelligence, so now put that momentum to use and hunt for other opportunities before the crowd catches up.
- Target potential mispricings by scanning a curated pool of 35 high quality undervalued stocks that pair solid fundamentals with more forgiving entry prices.
- Strengthen the defensive side of your portfolio by focusing on companies in the list of solid balance sheet and fundamentals (23 results) that can better handle financial stress.
- Get ahead of the herd by reviewing 16 high quality undiscovered gems that combine strong metrics with limited market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com