
Is Mitsui Kinzoku Company (TSE:5706) A Bargain On Its Factorial Battery Partnership?
Mitsui Kinzoku alliance with Factorial puts battery materials in focus
Mitsui Kinzoku Company (TSE:5706) is back on investor radar after Factorial Energy Inc. announced a partnership to industrialize its Solstice all solid state battery platform using Mitsui Kinzoku’s sulfide electrolyte technology.
Recent trading shows how quickly sentiment around Mitsui Kinzoku can swing. The share price jumped 7.35% in the last day but is still down 20.21% over 30 days and 53.31% over 90 days. Total shareholder return over five years is very large at about 7x the original investment, which suggests that investors are weighing the long run battery materials story against near term volatility around deals such as the Factorial alliance.
Scan other battery and materials players riding similar catalysts with our curated list of 36 best rare earth metal stocks while you assess what this Factorial deal could mean for Mitsui Kinzoku over time.
Bulls point to Mitsui Kinzoku’s battery materials footprint and the Factorial deal, while bears focus on the sharp recent share price fall. Which side do the current numbers lean toward as you think about valuation next?
Price-to-Earnings of 11.4x for Mitsui Kinzoku: Is it justified?
Mitsui Kinzoku Company closed at ¥22,795, while its current P/E of 11.4x screens as relatively low compared to both the broader JP market and its own fair value estimate. This suggests the stock may be pricing in a discount to its recent earnings strength.
The P/E ratio compares the share price to earnings per share, so for Mitsui Kinzoku an 11.4x multiple reflects what investors are currently willing to pay for each yen of profit. For a materials and metals group with segments across functional materials, metals and automotive parts, this metric often serves as a quick read on how the market treats the durability and quality of its earnings base.
Recent profit trends give that number more context. Earnings grew by 211.7% over the past year and by 13.7% per year over the past 5 years, and management currently produces a 27% Return on Equity that is classified as high. Those figures, together with high quality earnings and net profit margins sitting at 14.4% versus 5.1% a year ago, point to a business where the market could be underpricing the current level of profitability even if future growth forecasts are much lower at 4.2% per year.
Relative to peers, the picture sharpens. Mitsui Kinzoku is judged to be good value on a P/E of 11.4x against the estimated fair P/E of 19x, which is a very large gap that the market could eventually close if earnings remain resilient. The stock also trades on a lower P/E than the wider JP market at 14.1x, yet is described as slightly expensive versus the JP Metals and Mining sector average of 11.2x. This suggests investors are already paying a small premium compared to direct industry rivals while still leaving room based on the fair ratio model.
Explore the SWS fair ratio for Mitsui Kinzoku Company.
Result: Price-to-Earnings of 11.4x (UNDERVALUED)
Still, the recent 53.31% share price fall over 90 days and any disappointment around the Factorial alliance could quickly challenge today's Mitsui Kinzoku valuation story.
Find out about the key risks to this Mitsui Kinzoku Company narrative.
Another view on Mitsui Kinzoku valuation
The P/E arguments around Mitsui Kinzoku look attractive, yet the SWS DCF model paints a cooler picture. On this view, the share price of ¥22,795 sits above an estimated future cash flow value of ¥18,977, so the stock screens as overvalued on this method. Which signal carries more weight for you?
For readers who want to unpack the moving parts behind that cash flow output, take a closer look at how the SWS DCF model treats Mitsui Kinzoku’s earnings power, reinvestment needs and risk assumptions here Look into how the SWS DCF model arrives at its fair value.
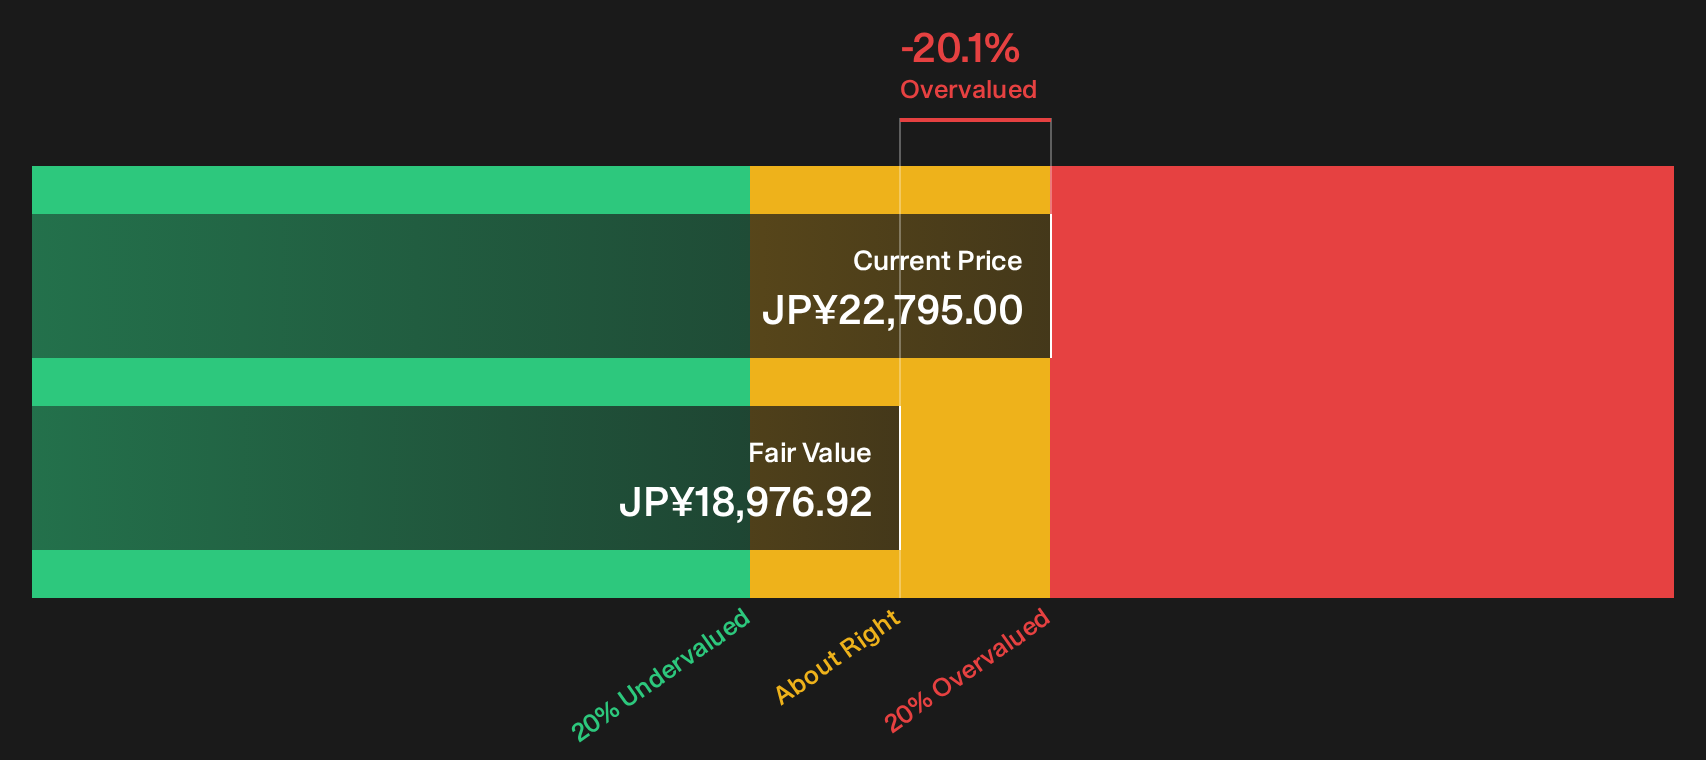
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Mitsui Kinzoku Company for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Mitsui Kinzoku can be hard to read, so move quickly and dig into the figures yourself, starting with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Mitsui Kinzoku?
If the Mitsui Kinzoku story has you thinking harder about where to deploy capital next, do not stop with just one ticker on your watchlist.
- Target income first and review 14 dividend fortresses that can help support a portfolio focused on steady cash payouts.
- Hunt for value by scanning 75 high quality undiscovered gems that pair strong fundamentals with relatively low market attention.
- Prioritise resilience and stress test your holdings against 21 resilient stocks with low risk scores before the next bout of volatility hits.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com