
Harley Davidson (HOG) Could Be 8% Below Fair Value As Realtree Returns
Harley-Davidson (HOG) is back in the headlines after reuniting with Realtree for a second limited-edition apparel collection, a merchandising move that arrives shortly after a softer week for the stock.
That Realtree drop lands at a time when Harley-Davidson’s share price has cooled in the short term, with a 7-day share price return down 6.96% and a 30-day share price return down 8.05%, even after a 25.63% year-to-date gain and a weaker 1-year total shareholder return that has declined 5.37%. This hints that recent news is bumping up against longer running concerns about motorcycle demand, LiveWire progress, and how much risk investors are willing to take on the stock right now.
Look beyond Harley-Davidson's recent pullback and see how it compares with 35 high quality undervalued stocks, where stronger balance sheets and cash flows may be working in their favor.
Harley-Davidson now trades below the average analyst target after a sharp short term pullback. Is that a simple discount on sentiment, or a warning label on the valuation story that follows?
Most Popular Narrative: 8% Undervalued
Harley-Davidson last closed at $25.93, while the most followed valuation story anchors on a fair value around $28.18. This frames the latest slide as a potential gap between sentiment and modeled cash flows rather than a simple momentum pause.
Ongoing cost rationalization and new efficiency programs, including the use of AI technology, together with an asset-light HDFS model and supply chain initiatives, are expected to yield substantial long-term improvements in operating margins and net earnings, as evidenced by ongoing productivity gains and targeted savings commitments.
See why 13 investors see Harley-Davidson as 8% undervalued.
Result: Fair Value of $28.18 (UNDERVALUED)
Still, the story around Harley-Davidson can change quickly if global motorcycle retail sales keep falling, or if LiveWire volumes stay weak and EV uptake disappoints.
Find out about the key risks to this Harley-Davidson narrative.
Another View: Harley-Davidson Through The Cash Flow Lens
The earlier discussion leans on analyst targets and earnings based metrics to argue Harley-Davidson looks about 8% below a fair value of $28.18. A very different picture appears when the Simply Wall St DCF model is applied, with that approach indicating the stock trades well above an estimated future cash flow value of $4.35. That kind of gap raises a simple question for investors: which story feels more reliable, the earnings line or the cash flows underneath it?
Look into how the SWS DCF model arrives at its fair value.
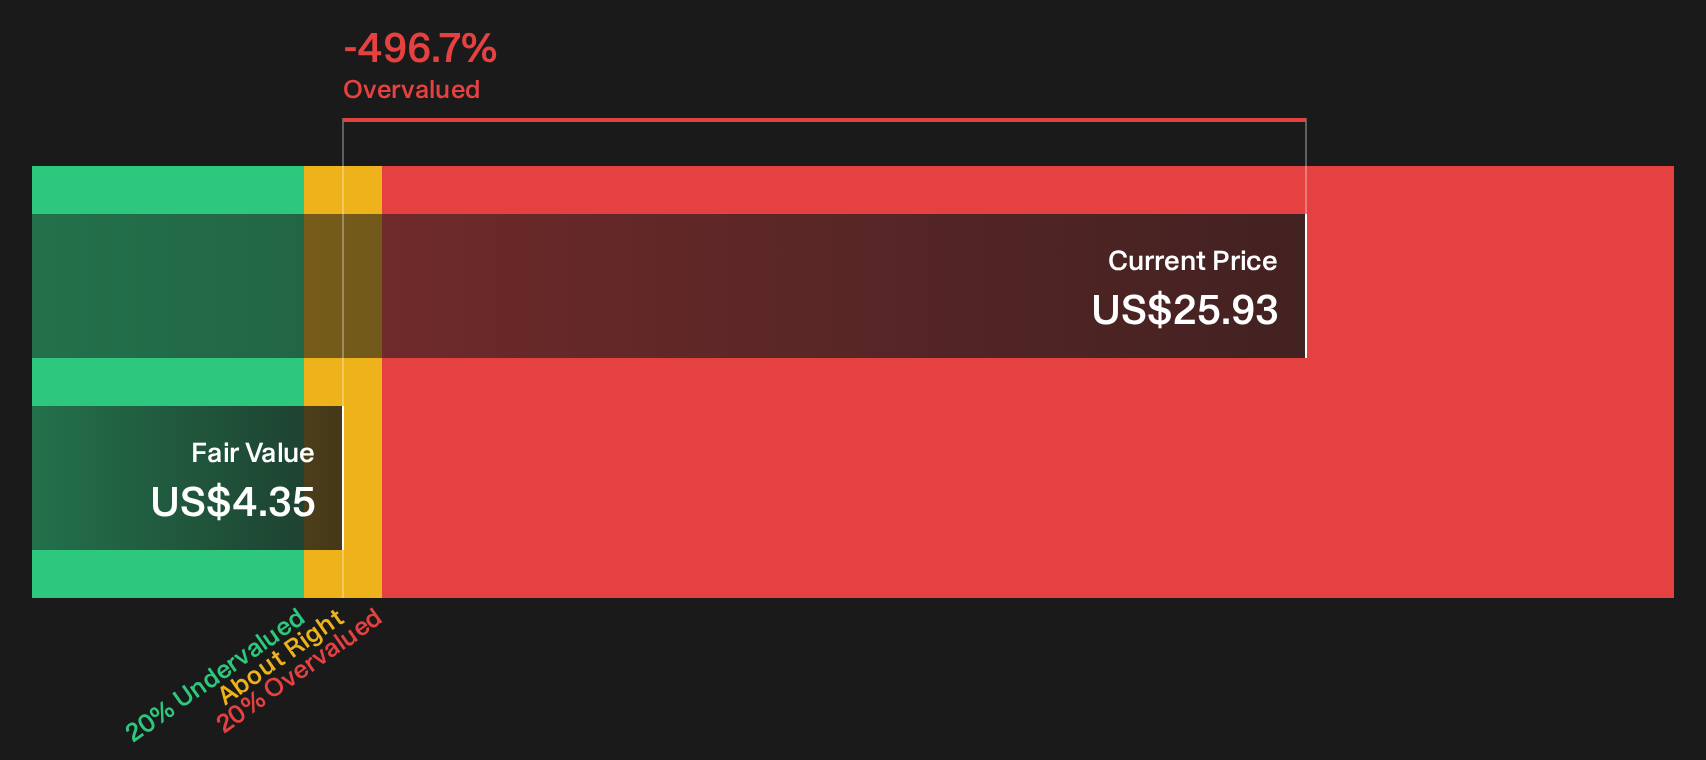
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Harley-Davidson for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around Harley-Davidson are clear, with recent price weakness sitting alongside both flagged risks and reasons for optimism. Act quickly, review the underlying metrics, and weigh the 2 key rewards and 1 important warning sign
Looking for more Harley-Davidson investment ideas?
Do not stop at Harley-Davidson. Use the Simply Wall St screener to uncover other shares that fit your risk, income, and value preferences before the crowd notices.
- Target resilient income by reviewing companies that show up in our list of 7 dividend fortresses and see which yields line up with your goals.
- Hunt for potential bargains by scanning the 35 high quality undervalued stocks and compare how their valuations stack up against the assumptions baked into Harley-Davidson.
- Prioritize capital preservation by filtering for 30 resilient stocks with low risk scores. Then check which balance sheets and risk scores feel more comfortable than HOG right now.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com