
Nebius Group And 2 High Conviction Growth Stocks
Big Tech’s push to keep an estimated US$300b of AI exposure off balance sheets has created a huge buildout of data centres and chips, but also fresh questions about how sustainable that spending really is. That mix of ambition and scrutiny puts more focus on fast expanding businesses where insiders have meaningful skin in the game. This article breaks down three such high conviction growth stocks from our screener.
The stocks covered below are only a small sample, and the full screen surfaced 176 more companies where growth expectations and insider ownership create equally compelling narratives that this article does not touch on.
If you want to go straight to the source and identify high conviction opportunities, head into the Fast Growing Stocks With High Insider Ownership screener to filter, compare, and analyze the full list on your own terms.
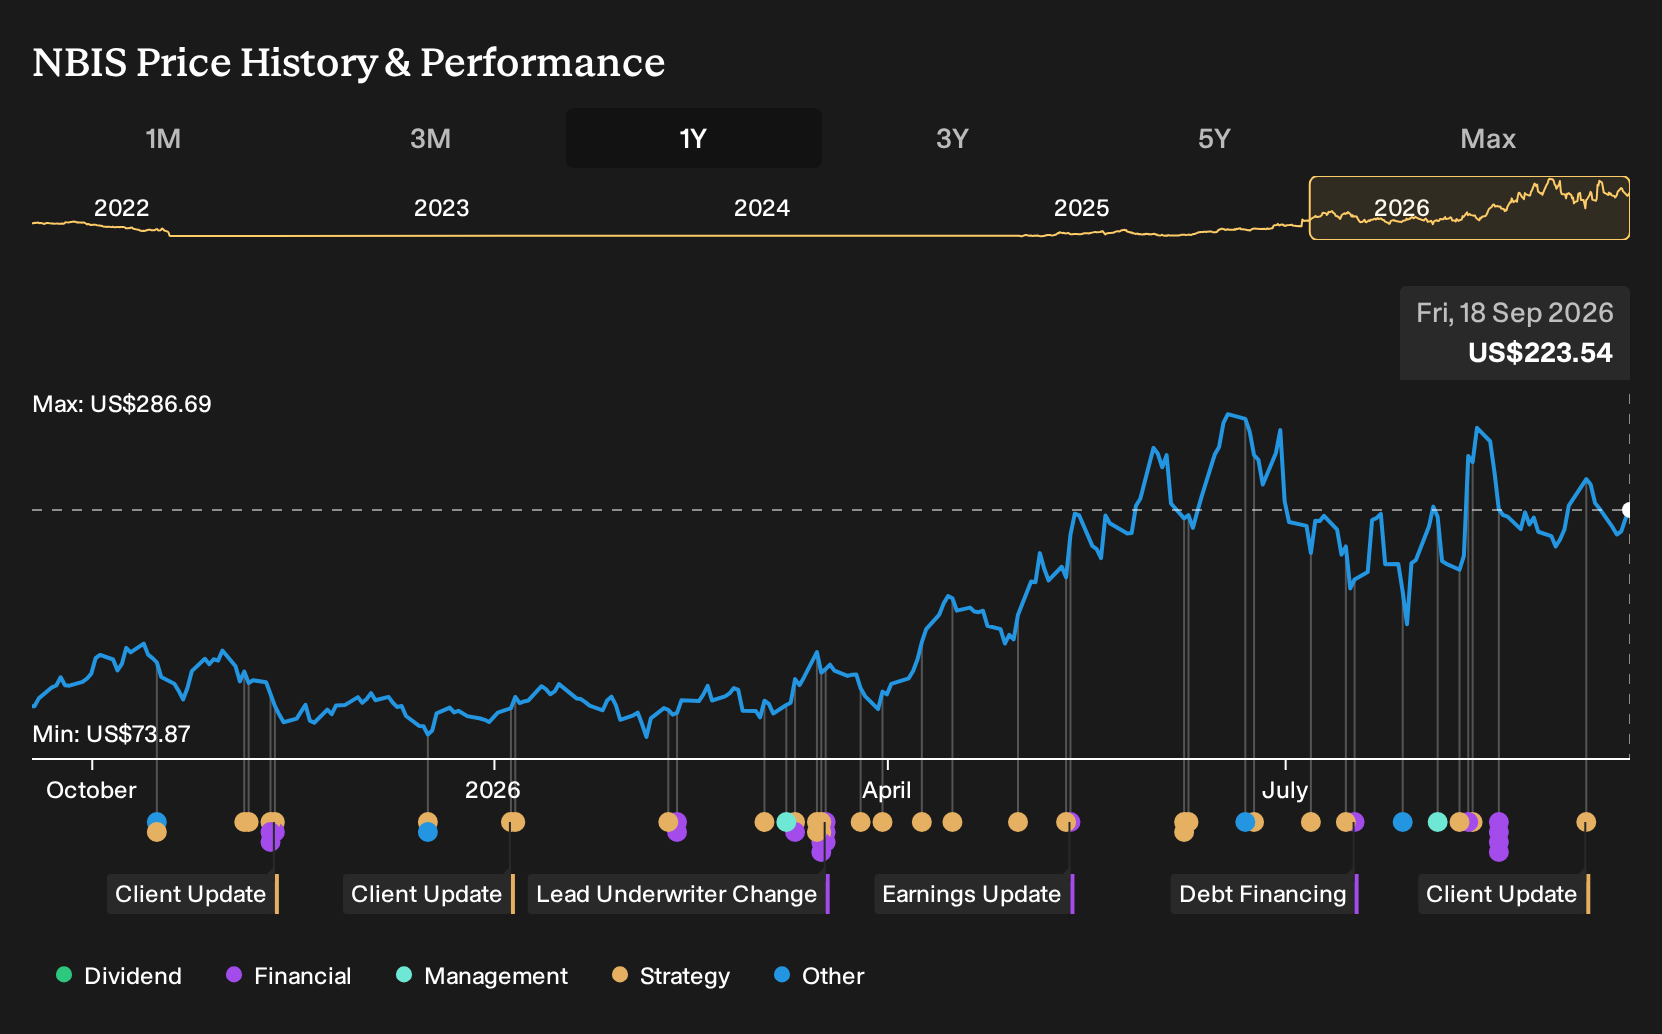
Nebius Group (NBIS)
Nebius Group is built around full stack AI infrastructure, supplying GPU rich cloud platforms for generative AI workloads, which is exactly what this screener is trying to surface for investors.
Nebius Group runs large scale AI cloud infrastructure, supported by a tie up with NVIDIA, alongside smaller TripleTen edtech and Avride autonomous driving units. Nebius AI Cloud generates about US$1.31b in revenue, with TripleTen at roughly US$53 million, and Avride still tiny. The group’s market value is about US$61.3b.
"As Nebius Group aggressively expands data center capacity and pursues greenfield builds to support future growth, heightened regulatory scrutiny regarding data sovereignty and localization, particularly in core markets such as the U.S., Europe, and Israel, may significantly increase compliance costs and limit expansion potential."
Where things get really interesting for Nebius is how one unresolved pressure could reshape both its pricing power and long term margin profile.
That pricing pressure is only half the story, and the full narrative for Nebius Group explains how Nebius Group’s expansion plans, contracts, and capital intensity could be decoupling from headline AI enthusiasm.
Oracle (ORCL)
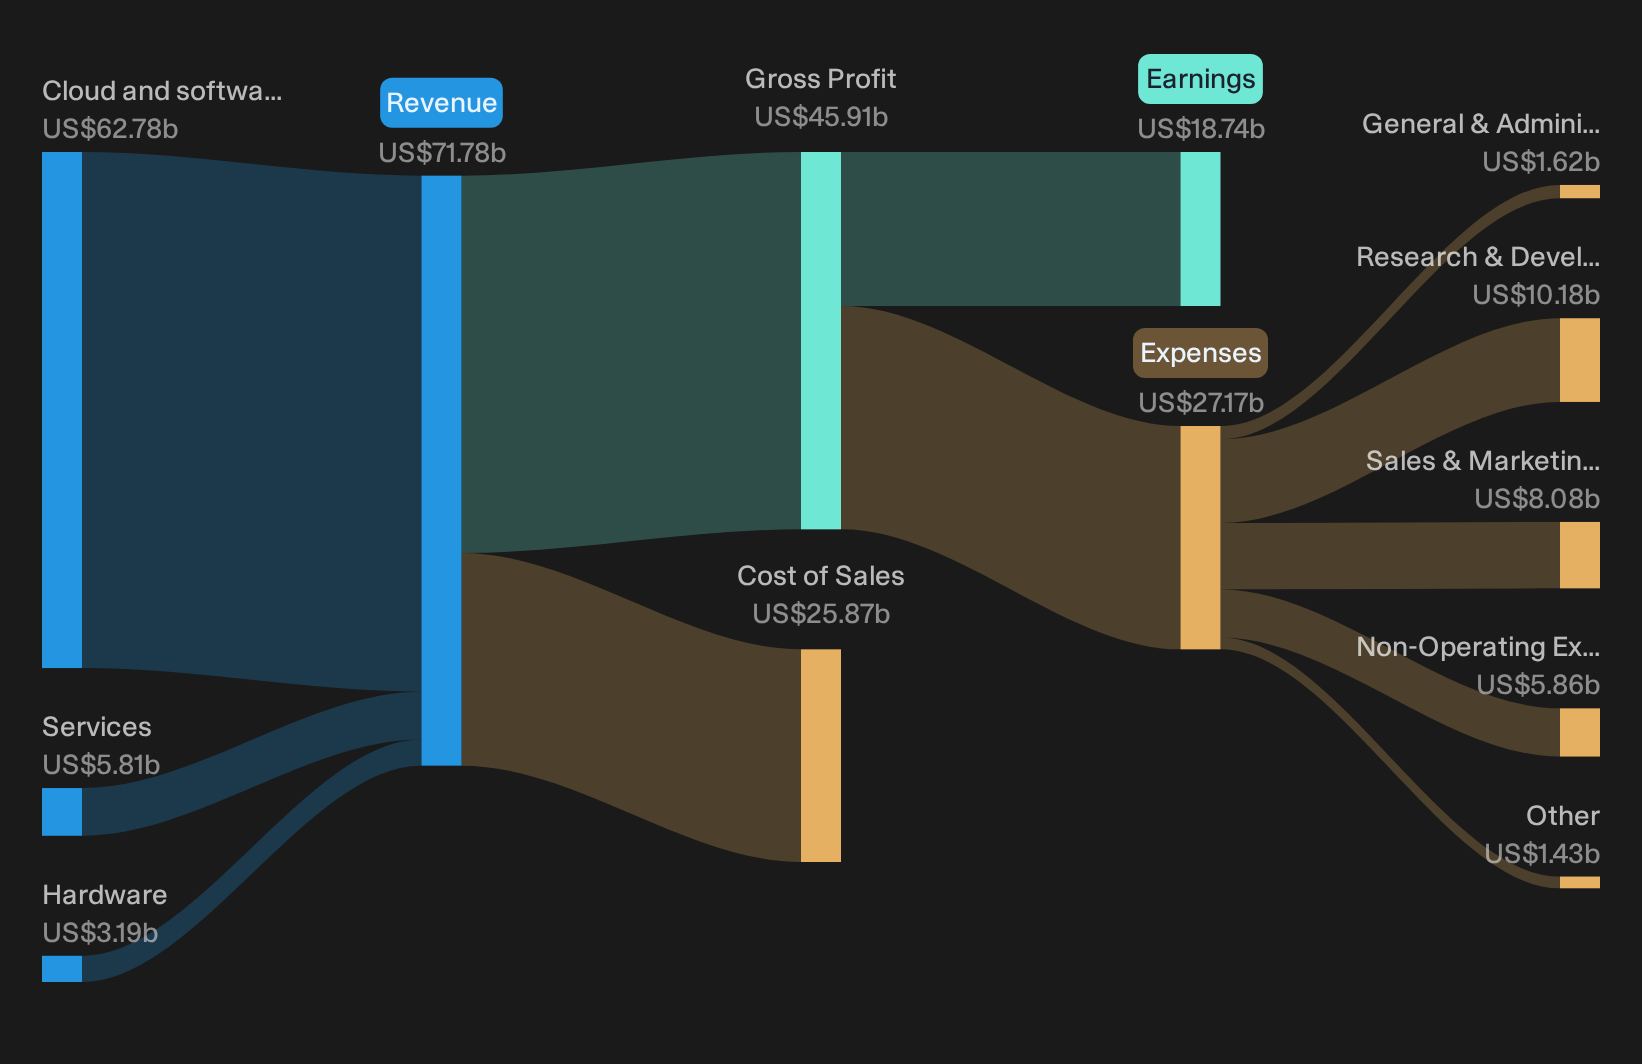
Oracle plugs into this screener through its cloud subscriptions, especially Fusion applications and the Autonomous Database. Management highlights these as the main engine for future growth within a broader software and hardware portfolio.
Oracle runs a wide software and infrastructure platform, from Fusion ERP and HCM suites to the Autonomous Database that anchors its higher growth cloud and SaaS push. Most revenue comes from cloud and software at about US$62.8b, with hardware at roughly US$3.2b and services near US$5.8b. The business is valued around US$446.3b.
For investors looking at fast growing companies where leadership is visibly backing an ambitious plan, Oracle brings a clear example of how a legacy enterprise vendor can lean on cloud subscriptions and AI infrastructure to reshape its growth profile.
"In 2024, OpenAI made headlines by expanding its cloud footprint to include Oracle Cloud Infrastructure (OCI). This move was described as strategic, reflecting the growing demand for massive compute power and the need for multi-cloud resilience. The physical manifestation of this ambition is staggering, with Oracle building gigawatt-scale data centers such as a 1,100-acre campus in Abilene, Texas, dedicated initially to OpenAI workloads."
What really matters now is how one massive, long dated AI contract backlog ultimately flows through to Oracle’s margins and free cash generation.
Those margin questions are only the start, and the full narrative for Oracle shows how Oracle’s AI cloud backlog could reshape the story once current investment intensity eases.
AppLovin (APP)
AppLovin leans straight into the screener theme through its AI powered ad tech, giving app publishers and advertisers tools that can ramp user acquisition and in-app monetization quickly. The Advertising segment generates about US$6.8b in revenue, and the stock is valued near US$103.1b.
For this screener, AppLovin matters because its AXON driven ad stack offers a direct way to tie AI into faster revenue growth, and management is clearly leaning into that opportunity with products built to scale across more advertisers.
"Expanded rollout of the self-service AXON ads manager and Shopify integration is expected to open AppLovin's platform to a massive new base of small and mid-sized advertisers globally, dramatically increasing advertiser count and driving sustained uplift in topline revenue."
The real test for AppLovin is how one shift in where that new advertiser spend lands ultimately shapes long term margins and cash generation.
That shift in spend is exactly the hinge for the full narrative for AppLovin, which explains how AppLovin’s AXON push could accelerate or limit the next stage of its story.

Seeking Fresh Alternatives Before They Fly
Fresh ideas do not stay quiet for long. Breakout stories gather momentum fast, and slow movers get caught chasing. Scan these curated lists while it matters and act now.
- Spot sturdier balance sheets before the crowd by running your filters through this curated list of solid balance sheet and fundamentals (23 results). Focus on businesses built to handle tougher conditions.
- Ride early momentum in AI infrastructure by scanning the hand picked 88 AI infrastructure stocks. This ties into the same compute and data center themes driving Nebius Group and Oracle.
- Track real cash generators in AI by scanning the focused 38 profitable AI stocks that aren't just burning cash, where the emphasis is on companies already converting hype into earnings and free cash flow.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com