
Cadence Design Systems (CDNS) Could Be 30% Undervalued After Analog Devices Win
Cadence Design Systems (CDNS) is back in focus after its Tensilica IP Group helped Analog Devices develop new SHARC automotive audio processors, and demand for advanced packaging supports its System Design and Analysis business.
Despite these product wins, Cadence Design Systems’ share price has been under pressure, with a 30 day share price return down 11.32% and a 90 day share price return down 27.28%, while the 1 year total shareholder return has declined 24.23%. The 3 and 5 year total shareholder returns of 22.65% and 72.97% keep a longer term gain in place, suggesting recent momentum has faded as investors reassess growth expectations and risk around AI exposed software names at a US$282.9 price point.
Capitalize on the same AI and chip design momentum driving Cadence Design Systems by scanning our hand-picked 88 AI infrastructure stocks that could be setting up their next big move.Cadence Design Systems now sits at a very different entry point after the pullback. The key issue is whether recent weakness has already reset expectations, or if most of the upside is still behind the stock at US$282.9.
Most Popular Narrative: 30% Undervalued
The most followed narrative on Cadence Design Systems places fair value at about $403.67 per share, well above the last close at $282.90. That gap hinges on how much weight you give to AI driven design tools, digital twins, and long term earnings forecasts.
Cadence's strategic investments in AI driven design and verification tools are expected to drive future revenue growth, as the company reports increasing adoption of its AI enabled offerings, such as the Cadence Cerebrus AI solution and SimAI, which have shown significant performance improvements for customers.
The expanding partnership with major industry players like NVIDIA and Intel, including initiatives such as 3D IC and data center digital twins, positions Cadence for future competitive advantages and new revenue streams.
See why 93 investors see Cadence Design Systems as 30% undervalued.
Analysts in this widely followed narrative are using a discount rate of 8.6% and project revenue growth of 12.6% a year with profit margins around 23.7%. On those assumptions, they reach a fair value of about $403.67 for Cadence Design Systems, which sits roughly 30% above the current market price in this framework.
These projections rely on earnings reaching about $2.0b by around 2029, compared with $1.4b today, with the stock trading on a future P/E of 74.4x. That multiple is materially higher than both the US Software industry at 31.8x and an estimated fair P/E of 35x, so the narrative leans on the idea that Cadence Design Systems can sustain a premium based on earnings quality and return on equity that is forecast at 29.3% in three years.
Investors weighing this story have a few moving parts to test for themselves. Revenue and earnings have grown in recent years, margins have improved from 19.9% to 23.6%, and the business reports high quality earnings. At the same time, the stock currently trades above an internal future cash flow estimate of $197.63 and carries a value score of 1, which flags a rich entry point if the narrative growth path does not fully play out.
Result: Fair Value of $403.67 (UNDERVALUED)
Still, the story can break if AI monetization arrives slower than analysts assume, or if geopolitical setbacks in China disrupt Cadence Design Systems’ customer base.
Find out about the key risks to this Cadence Design Systems narrative.
Another View on Cadence Design Systems’ Valuation
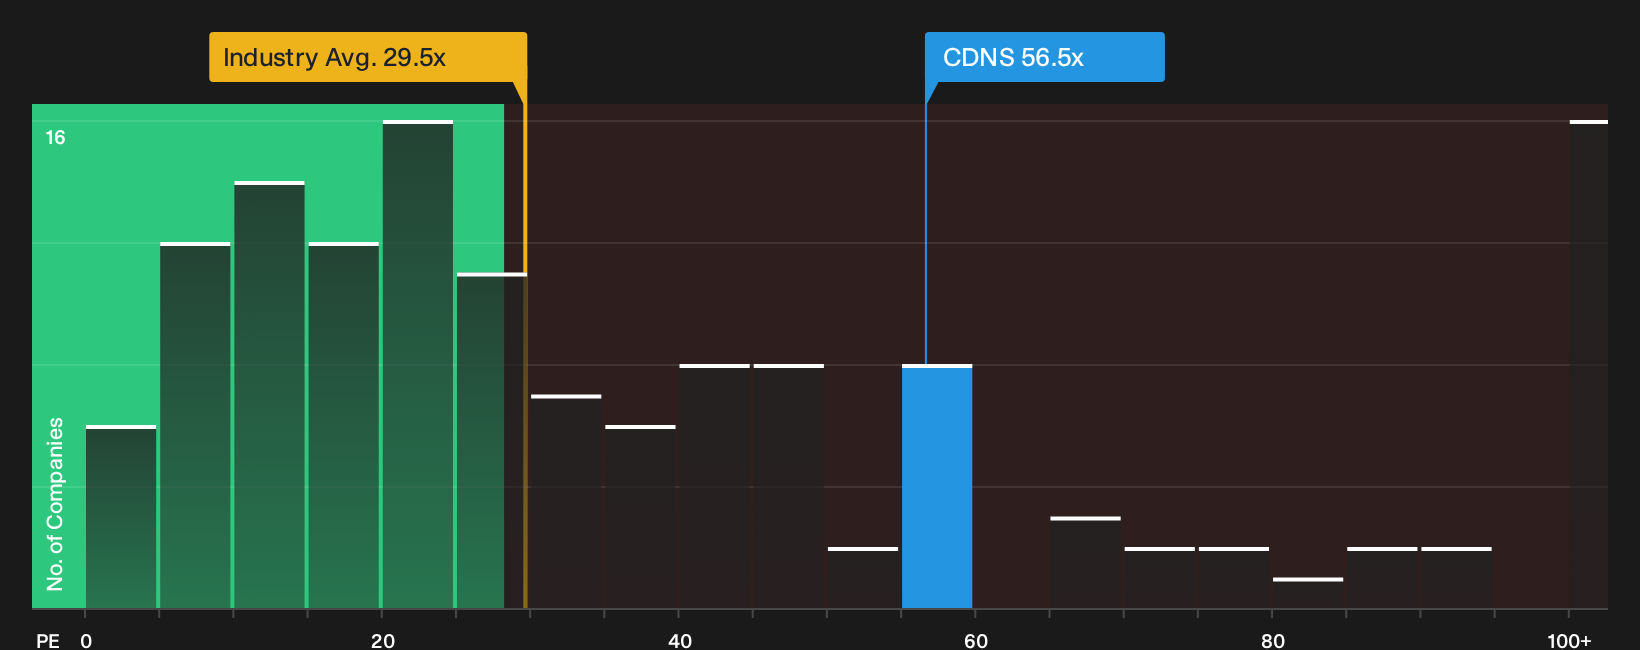
The first story paints Cadence Design Systems as roughly 30% undervalued based on long range earnings forecasts. A simpler comparison using the current P/E ratio tells a very different story. CDNS trades at 56.5x earnings, while the US Software group averages 29.5x and close peers sit near 34.3x. The fair ratio estimate is 35x. That kind of premium raises a practical question for investors: Is this a quality premium that can be maintained, or valuation risk if growth assumptions soften?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Cadence Design Systems has clearly split, with valuation signals and narratives pulling in different directions. Use the tools available, stress test the assumptions yourself, and then pressure test the upside and downside by reviewing the 3 key rewards.
Looking for more investment ideas beyond Cadence Design Systems?
If Cadence Design Systems has you rethinking your watchlist, this is the moment to broaden your radar and line up the next potential opportunities.
- Target resilience first by scanning a 30 resilient stocks with low risk scores that puts stability and risk control at the center of your research.
- Focus on quality at a reasonable entry point by reviewing a 16 high quality undiscovered gems with strong fundamentals that the market may be ignoring.
- Anchor your portfolio with balance sheet strength by filtering through a list of solid balance sheet and fundamentals (23 results) that can better withstand shocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com