
Shelf Registration Filing Could Be A Material Update For First Busey Stock (BUSE)
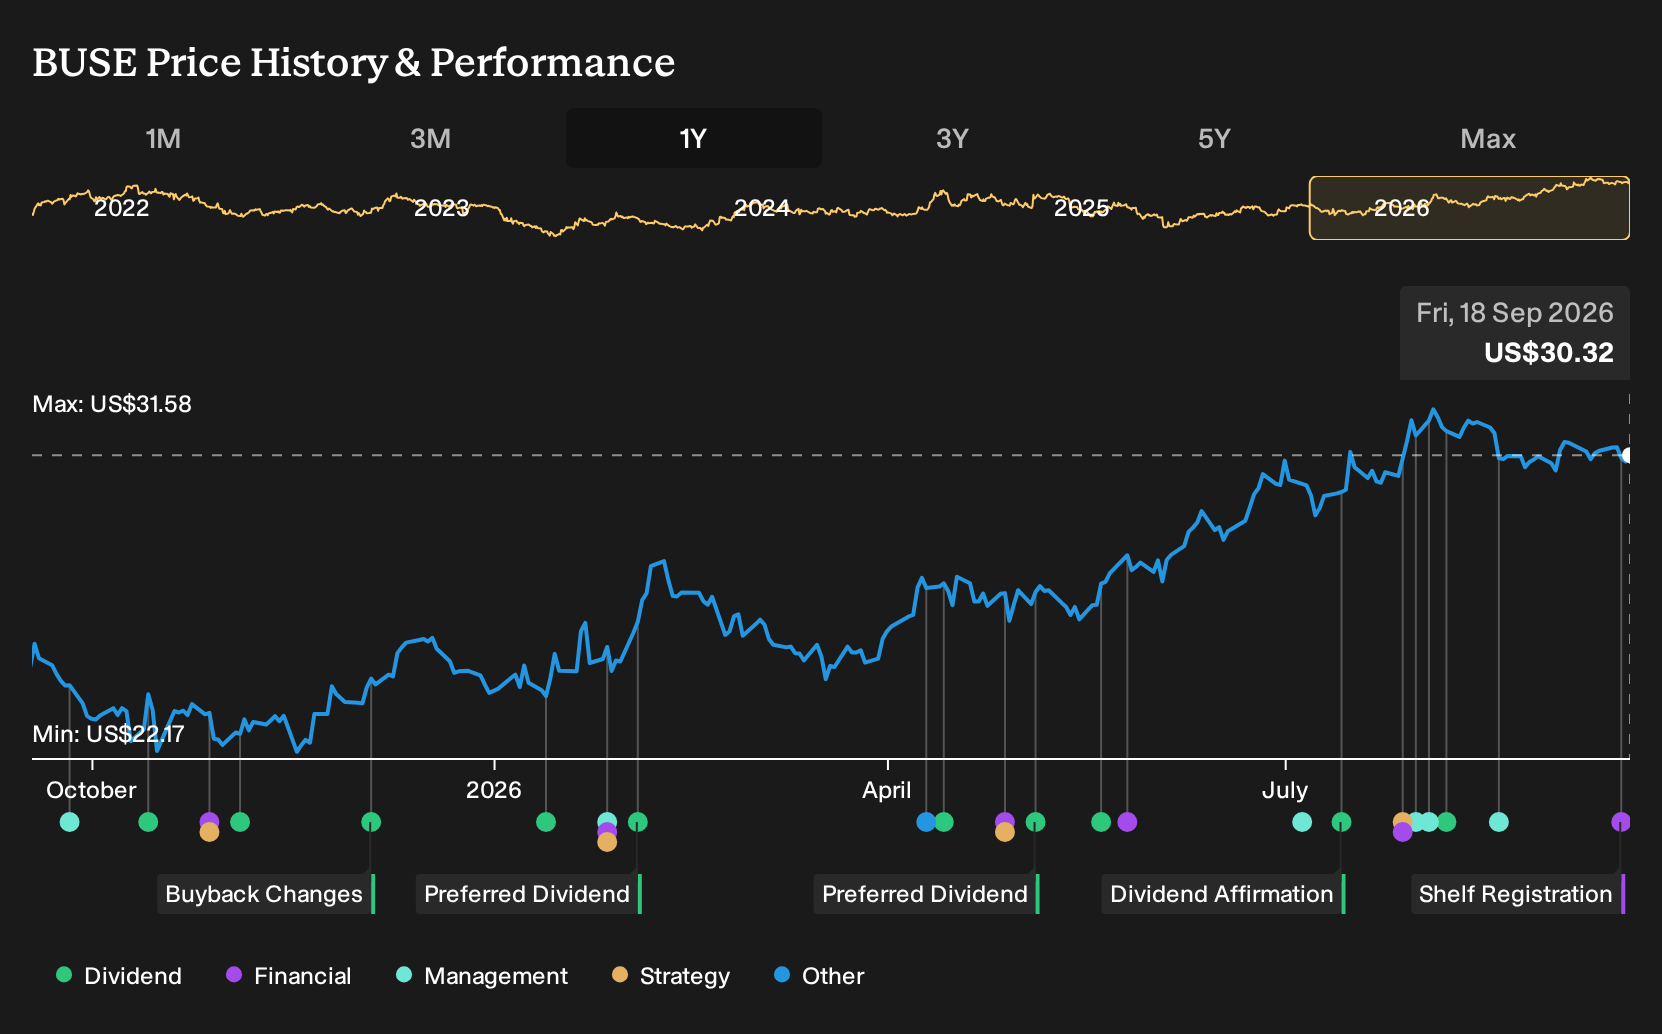
- First Busey Corporation filed an omnibus shelf registration in September 2026 that covers common and preferred stock, debt securities, warrants, depositary shares, subscription rights, stock purchase contracts, stock purchase units, and other units.
- This broad shelf registration framework gives First Busey flexibility to access different funding tools as business conditions, capital needs, and regulatory requirements change over time.
- We will now examine how First Busey’s new universal shelf capacity could influence its investment narrative and future capital decisions.
What Is First Busey's Investment Narrative?
For a shareholder, the core belief in First Busey is about a steady regional banking franchise with three legs that work together: traditional lending and deposits, fee income from wealth management, and the FirsTech payments arm. The business runs with meaningful capital needs, so how it funds growth and cushions credit cycles is key. The new universal shelf fits that story. It gives management optionality to tap equity, debt, or hybrids if loan demand, acquisition opportunities, or regulatory capital requirements shift.
In the near term, that flexibility is more of a toolkit than a catalyst. The filing by itself does not change loan growth, funding costs, or pricing power. It does potentially reshape the trade off between funding growth and protecting existing holders from dilution if it is used. Investors are still weighing a stock that screens as good value on some measures, with high quality earnings and a long operating history, against slower forecast revenue and profit growth than the broader US market.
Even so, tucked inside that seemingly balanced setup is a single pressure point that could matter a lot if the shelf is ever used at scale...
There's only one way to know the right time to buy, sell or hold First Busey. Head to Simply Wall St's company report for the latest analysis of First Busey's Fair Value.
Exploring Other Perspectives
Fair value estimates for First Busey from the Simply Wall St Community cluster between about US$33.29 and US$50.38 across 2 individual assessments, which already shows how far opinions can stretch. Those views were formed before the September 2026 universal shelf filing, so you may want to reassess how fresh funding options could affect future outcomes.
Explore another First Busey fair value estimate, including one that suggests it could be worth just $33.29.
Decide For Yourself
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your First Busey research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for First Busey. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate First Busey's overall financial health at a glance.
Looking For More Ideas Beyond First Busey?
If you want to put First Busey in context, it can help to compare it with other businesses that share similar strengths or offer a very different risk and reward profile. The Simply Wall St Screener lets you scan the market quickly using fundamentals rather than headlines.
- For investors who care most about balance sheet strength and underlying fundamentals, start with a list of solid balance sheet and fundamentals (23 results) that already clear some demanding quality filters.
- If you are hunting for companies that the market may not be fully focused on yet, use a 16 high quality undiscovered gems to see which smaller players still line up well on cash flows and financial health.
- Income focused readers who prefer cash returns right now can run a 7 dividend fortresses to find businesses offering higher yields with an eye on stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com