
Learn Why The Bull Case For Unum Group (UNM) Could Change Following $1b Buyback Plan
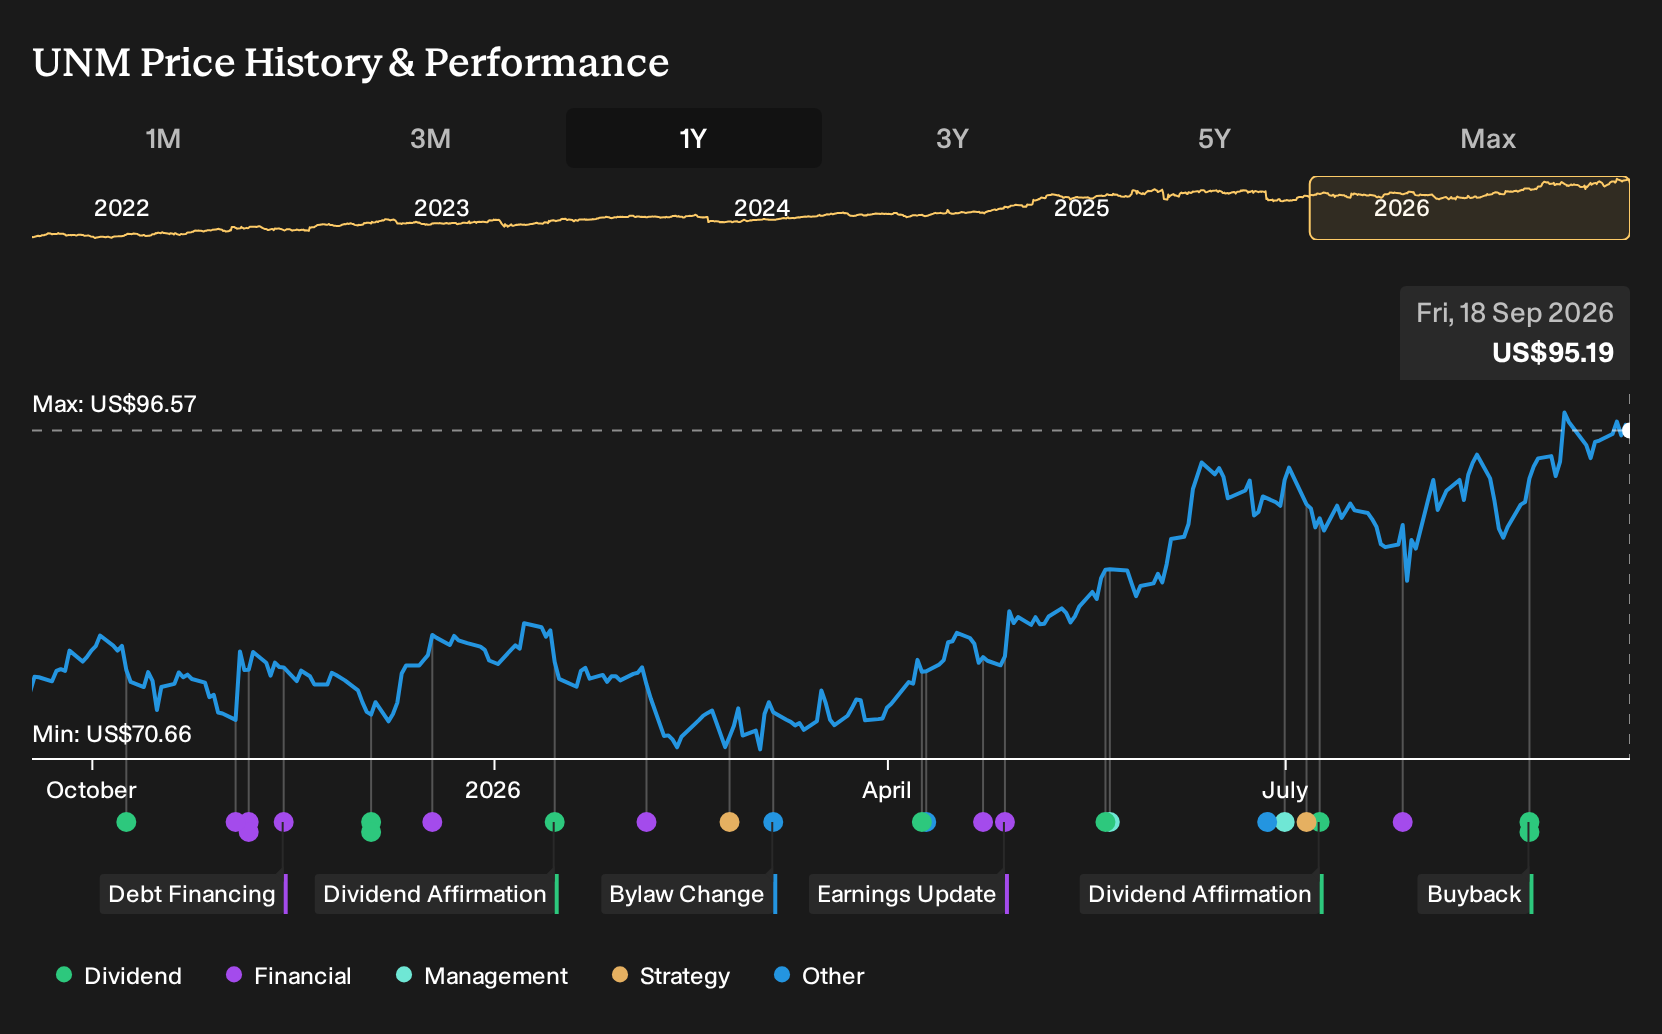
- Unum Group recently approved a new US$1.0b share repurchase authorization and received reaffirmed A level financial strength ratings with a stable outlook from AM Best for its core U.S. subsidiaries.
- The combination of a sizable buyback and unchanged A rating reflects management’s focus on disciplined capital returns, while maintaining balance sheet resilience and risk controls in line with insurer standards.
- We will now look at how Unum Group's new US$1.0b repurchase authorization could influence the existing investment narrative around capital returns.
Unum Group Investment Narrative Recap
To own Unum Group, you need to be comfortable with a fairly mature benefits insurer that leans on steady in force premiums, cost control, and investment income while working through issues like lower profit margins than last year and earnings volatility in its Closed Block of long term care. The key near term swing factor is how claim trends and benefit ratios behave in group disability and life, because sustained pressure here could weigh on earnings even if demand for employer benefits remains solid.
The largest current risk still sits in elevated benefit ratios and long term care variability, which can affect both earnings and statutory capital. The new US$1.0b repurchase capacity does not change those operational questions. However, it may influence how excess capital gets allocated if claim experience or investment yields move against Unum Group. For you, the thesis hinges more on execution in underwriting and pricing discipline than on the buyback headline.
The US$1.0b share repurchase authorization is the most relevant new development for this story. It sits on top of existing dividends and past capital return. Your focus should be on whether Unum Group can keep generating enough cash from underwriting and investments to comfortably fund both shareholder payouts and any needed reserve actions in the long term care book.
Rating reaffirmation from AM Best at the A level with a stable outlook matters here because it speaks to balance sheet resilience and risk controls while Unum Group leans into buybacks. That external view interacts directly with the main catalysts analysts highlight such as ongoing derisking of long term care through reinsurance, investment in digital platforms that support retention, and the aim to keep strong capital generation available for future capital returns.
Unum Group's current analyst narrative points to US$13.3b in revenue and US$1.5b in earnings by 2029. This is based on fairly flat top line expectations and a shift from US$781.4m in earnings today to that 2029 consensus figure, which implies an earnings increase of about US$718.6m from the current base.
Discover how Unum Group's fair value indicates a 7% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
The Simply Wall St Community currently includes just 2 fair value views on Unum Group, ranging from US$102.23 up to US$158.08, which is a wide gap for the same insurer. Those private investors have not yet factored in the fresh US$1.0b buyback or rating reaffirmation. Use that spread as a prompt to compare multiple viewpoints before deciding how you see Unum Group’s risk and reward profile.
Explore another Unum Group fair value estimate, including one that suggests it could be worth just $102.23.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Unum Group research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Unum Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Unum Group's overall financial health at a glance.
Looking for more investment ideas beyond Unum Group?
Once you have a view on Unum Group, it can help to widen the lens and compare it with other opportunities that match your own risk and income preferences. The Simply Wall St Screener lets you quickly filter the market down to a focused watchlist that fits how you like to invest.
- If you want to focus on stability and capital preservation, narrow your search to companies flagged as relatively resilient by starting with 30 resilient stocks with low risk scores.
- For investors hunting for potentially mispriced opportunities, scan companies that combine stronger fundamentals with what may look like a discounted entry point through 35 high quality undervalued stocks.
- If portfolio income is a key goal, you can zero in on higher yielding payers that still clear basic quality checks by reviewing 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com