
Is Ormat Technologies (ORA) Undervalued As Tax Credits And Storage Growth Support Its Story?
Ormat Technologies (ORA) came back into focus after recent trading left the share price at US$97.34, with the stock down about 10% over the past month and roughly 25% over the past 3 months.
Recent trading paints a mixed picture for Ormat Technologies, with the share price down about 10% over the past month and roughly 25% over the past quarter. Over the longer term, however, the 5 year total shareholder return of 47.13% points to momentum that has built over time rather than completely faded in the latest pullback.
Scan how Ormat Technologies compares with other potential rebound stories by reviewing the hand picked 35 high quality undervalued stocks that currently combine compressed prices with solid fundamentals.
After a pullback that left Ormat Technologies trading at US$97.34 against analyst targets of US$133.50 and an intrinsic value estimate that sits above the market, where does fair value actually land within that range?
Most Popular Narrative: 28.1% Undervalued
Relative to the latest close at $97.34, the most followed narrative pegs Ormat Technologies at a fair value of $135.45. This points to a wide gap that rests on policy support, project economics, and storage growth all holding together.
Extension of production and investment tax credits (PTC/ITC) for geothermal and energy storage projects through at least 2033 reduces capital costs, de-risks new project development, and boosts net margins and earnings over the next decade.
Elevated demand for reliable, carbon-free baseload power, driven by electrification trends (including data centers and industrial customers), is translating into premium power purchase agreement (PPA) pricing, supporting improved revenue visibility and margin expansion.
See why 10 investors see Ormat Technologies as 28% undervalued.
Result: Fair Value of $135.45 (UNDERVALUED)
Still, the bullish Ormat Technologies story relies on tight conditions, with heavy spend and higher leverage, and potential U.S. rules on Chinese batteries are both capable of knocking that script off course.
Find out about the key risks to this Ormat Technologies narrative.
Another View: Ormat Technologies Through Market Multiples
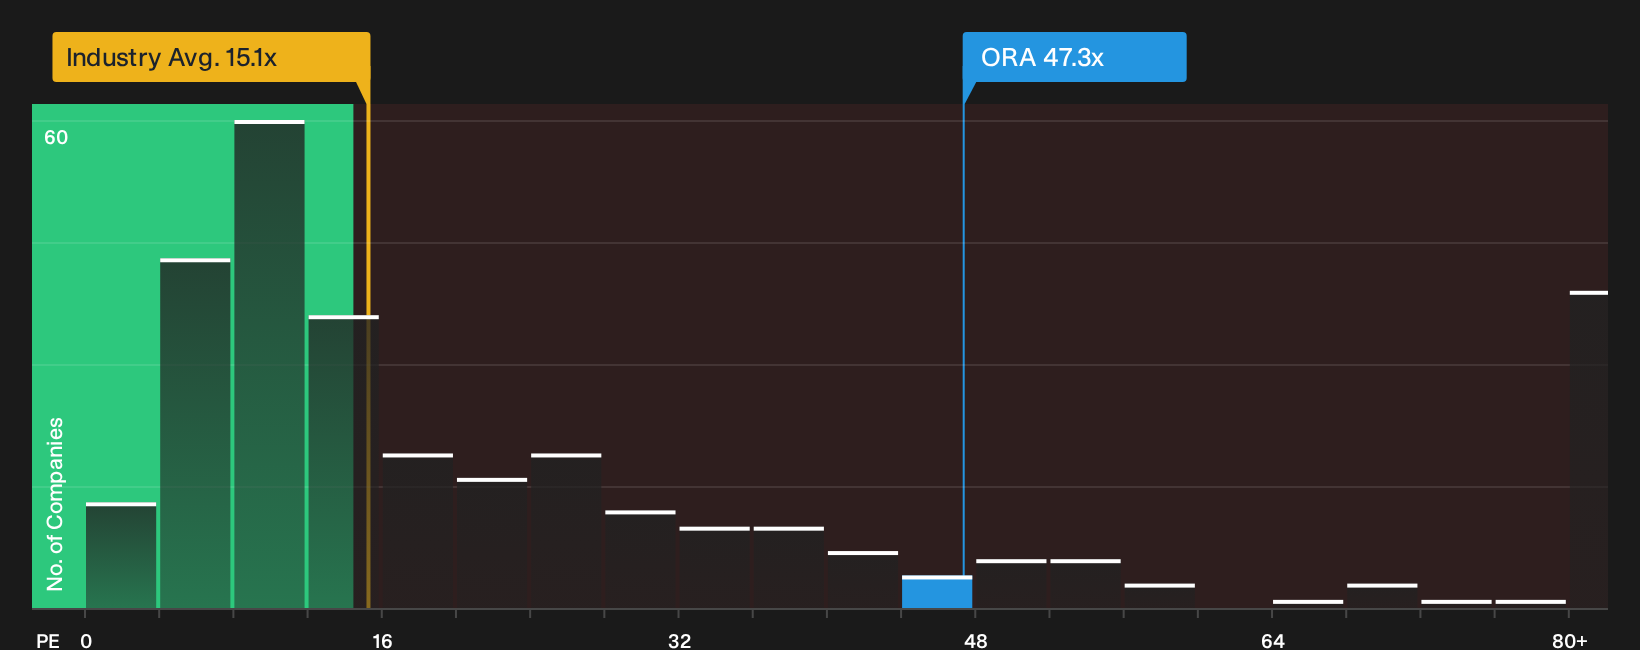
The story looks very different when Ormat Technologies is viewed through simple market ratios. At a P/E of 47.3x, the stock trades at more than 3x the Global Renewable Energy industry average of 15.1x, and well above its own fair ratio of 25.5x.
Such a wide premium suggests investors are already paying up heavily for future earnings, which raises the question of how much upside is really left if expectations slip.
For a closer look at what this gap between current P/E, peers, and the fair ratio might mean in practice, review the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Ormat Technologies so far. For a clearer view, consider both the downside and upside signals for yourself by starting with 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Ormat Technologies?
Do not stop with Ormat Technologies. Use the broader toolset to scan fresh opportunities and pressure test your thinking before the next move reshapes your portfolio.
- Target dependable income streams by reviewing companies in the 7 dividend fortresses that may suit a portfolio built around regular cash returns.
- Spot overlooked potential by running through the 16 high quality undiscovered gems that pair solid fundamentals with thinner analyst coverage.
- Prioritize resilience first by focusing on the 30 resilient stocks with low risk scores that score well on financial strength and lower risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com