
Is Home Depot (HD) A Bargain Following Its Tapo Camera Partnership?
TP-Link’s new partnership with Home Depot (HD) puts four exclusive Tapo smart home camera bundles into 500 stores and online, giving the retailer another connected security offering closely aligned with its core home improvement base.
The Home Depot share price has slipped to US$299.98, with the 30-day share price return down 10.62% and the year-to-date share price return down 13.26%. The 1-year total shareholder return has declined 25.79%, suggesting fading momentum, even though the 3-year total shareholder return stands at 5.97% and the 5-year total shareholder return at 0.89%.
Scan for other home improvement and retail players that are showing stronger price momentum or more resilient sentiment than Home Depot in our curated list of 35 high quality undervalued stocks.
Home Depot’s slide has already reset expectations, yet some investors will want a wider margin of safety while others see a rare entry point forming. Which side does the current valuation support?
Most Popular Narrative: 22% Undervalued
On the most followed valuation storyline, Home Depot screens as undervalued, with a fair value of $385 against the last close at $299.98, which puts a clear gap between what the narrative framework suggests and where the market is currently pricing the stock.
Home Depot is evolving from a traditional big-box home improvement retailer into a comprehensive supplier ecosystem for professional contractors ("Pros"), while continuing to serve DIY customers through stores, digital tools, and faster fulfillment. Recent acquisitions (including SRS Distribution and GMS) expand its reach into specialty distribution for roofing, drywall, HVAC, and other complex project categories, enlarging the addressable market toward roughly $1.2 trillion and the Pro segment opportunity near $700 billion.
See why 0 investors see Home Depot as 22% undervalued.
Result: Fair Value of $385 (UNDERVALUED)
Still, the Home Depot narrative can crack if housing activity stays muted for longer, or if recent acquisitions weigh on margins and Pro adoption stalls.
Find out about the key risks to this Home Depot narrative.
Another View: DCF Flips The Story
The popular Home Depot narrative leans on a fair value of $385, yet the SWS DCF model paints a cooler picture. On that cash flow view, Home Depot at $299.98 screens above an estimated value of $276.97, which tilts the signal toward overvalued instead of discounted. Which story feels more convincing to you right now?
For investors who want to see how that cash flow result is built line by line, the detailed SWS DCF model can help you judge whether the inputs feel realistic or too generous Look into how the SWS DCF model arrives at its fair value.
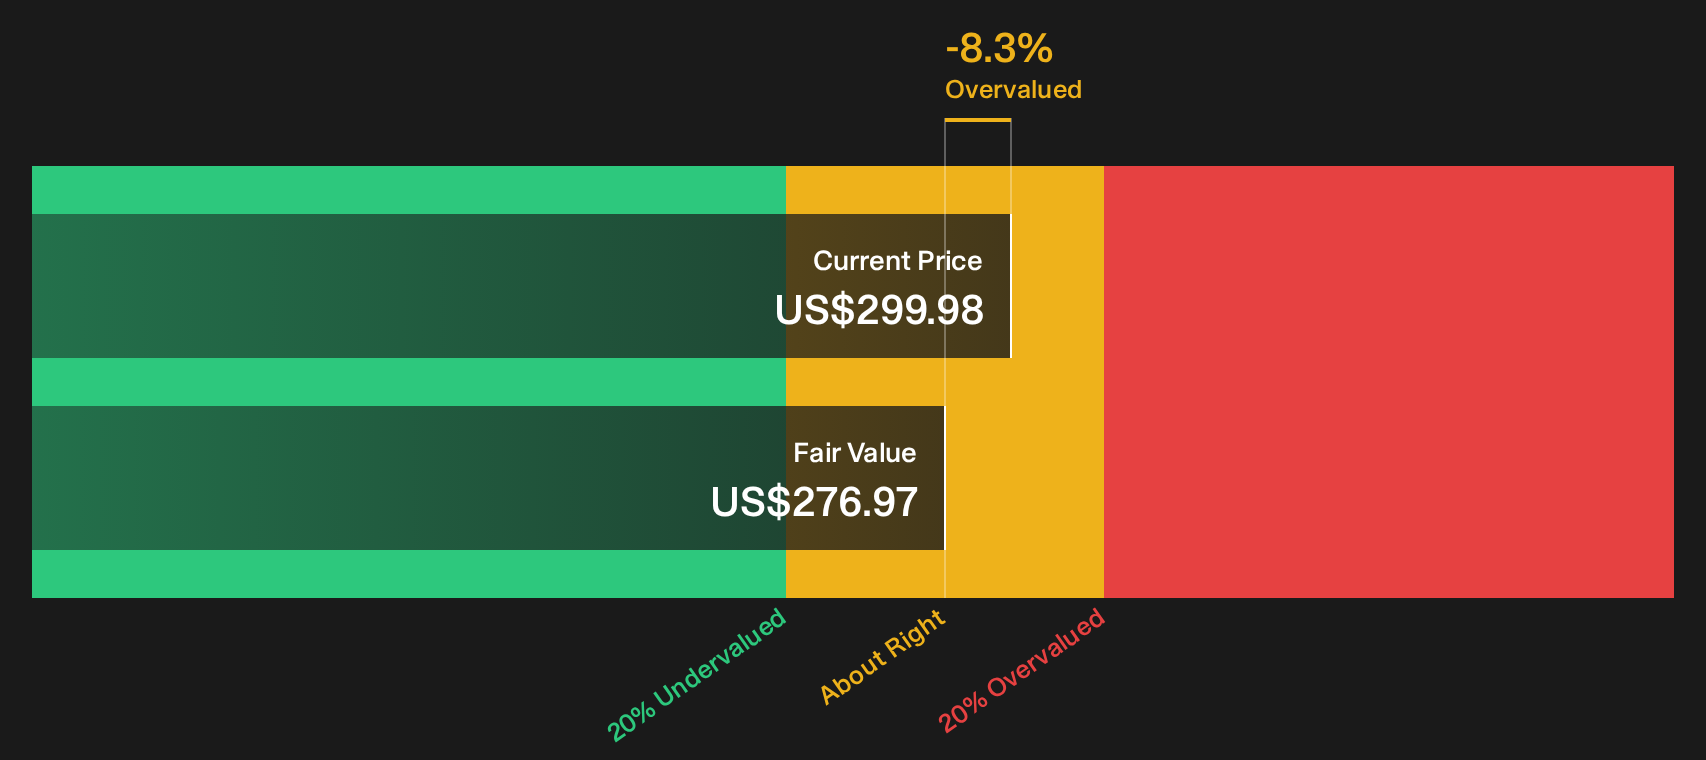
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Home Depot for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Home Depot can either paralyze or prompt action. Move quickly, examine the data, and weigh both sides with 3 key rewards and 2 important warning signs
Looking for more Home Depot sized investment ideas?
If Home Depot has sharpened your focus on valuation and timing, do not stop here. The right watchlist today can shape your options tomorrow.
- Target potential mispricings by scanning a focused universe of resilient opportunities through the Simply Wall St screener in 35 high quality undervalued stocks.
- Prioritize income by zeroing in on companies that combine higher yields with staying power using our screener of 7 dividend fortresses.
- Dial down portfolio stress and search for steadier performers across sectors with our curated universe of 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com