
How Earnings Estimate Upgrades At Insight Enterprises (NSIT) Have Changed Its Investment Story
- Insight Enterprises has recently seen analysts revise earnings estimates higher, supported by its exposure to AI-related infrastructure, cybersecurity services, and hybrid work solutions that tie directly to client demand for modern IT environments.
- The concentration of upward estimate revisions without offsetting cuts suggests improving confidence in Insight Enterprises' mix of higher-margin cloud, consulting, and managed services, compared with its more commoditized hardware reselling activity.
- We will now look at how these upward earnings revisions may influence Insight Enterprises' investment narrative for long term oriented investors.
Scan other IT and AI infrastructure plays showing similar estimate momentum by reviewing the 88 AI infrastructure stocks alongside Insight Enterprises' recent revisions.
Insight Enterprises Investment Narrative Recap
To own Insight Enterprises, you need to believe that its pivot toward cloud, AI, cybersecurity, and managed services can steadily outweigh pressure on lower margin hardware resale. The recent momentum in earnings estimates points to confidence in that mix, but the near term catalyst still sits in execution on higher margin contracts and renewals rather than short bursts of share price strength.
The biggest risk right now is that large clients continue to delay bigger infrastructure and AI projects, which would slow growth in those richer solution areas. Vendor program changes and Insight Enterprises' debt load also matter, yet the recent estimate trend does not fundamentally change those operational trade offs.
The most relevant update is the cluster of upward earnings revisions for Insight Enterprises over the past two months, with no cuts. That pattern aligns with the B Momentum Style Score and Zacks Rank #2, and it indicates that analysts see something improving in the underlying story, particularly around profit mix and execution.
For catalysts, that revision streak is tied directly to expectations for AI related infrastructure, cybersecurity contracts, and hybrid work projects that could support earnings over the next few years. The risk side is unchanged. Client spending hesitancy, vendor program shifts, and acquisition integration still sit in the background, even as near term sentiment has turned more constructive.
Insight Enterprises' current narrative projects revenue of US$9.9b and earnings of US$392.5m by 2029, which implies forecast revenue growth of 4.9% per year and an earnings increase of about US$182m from current earnings of US$210.5m.
Uncover why Insight Enterprises' fair value indicates a 6% potential upside to its current price that could narrow quickly.
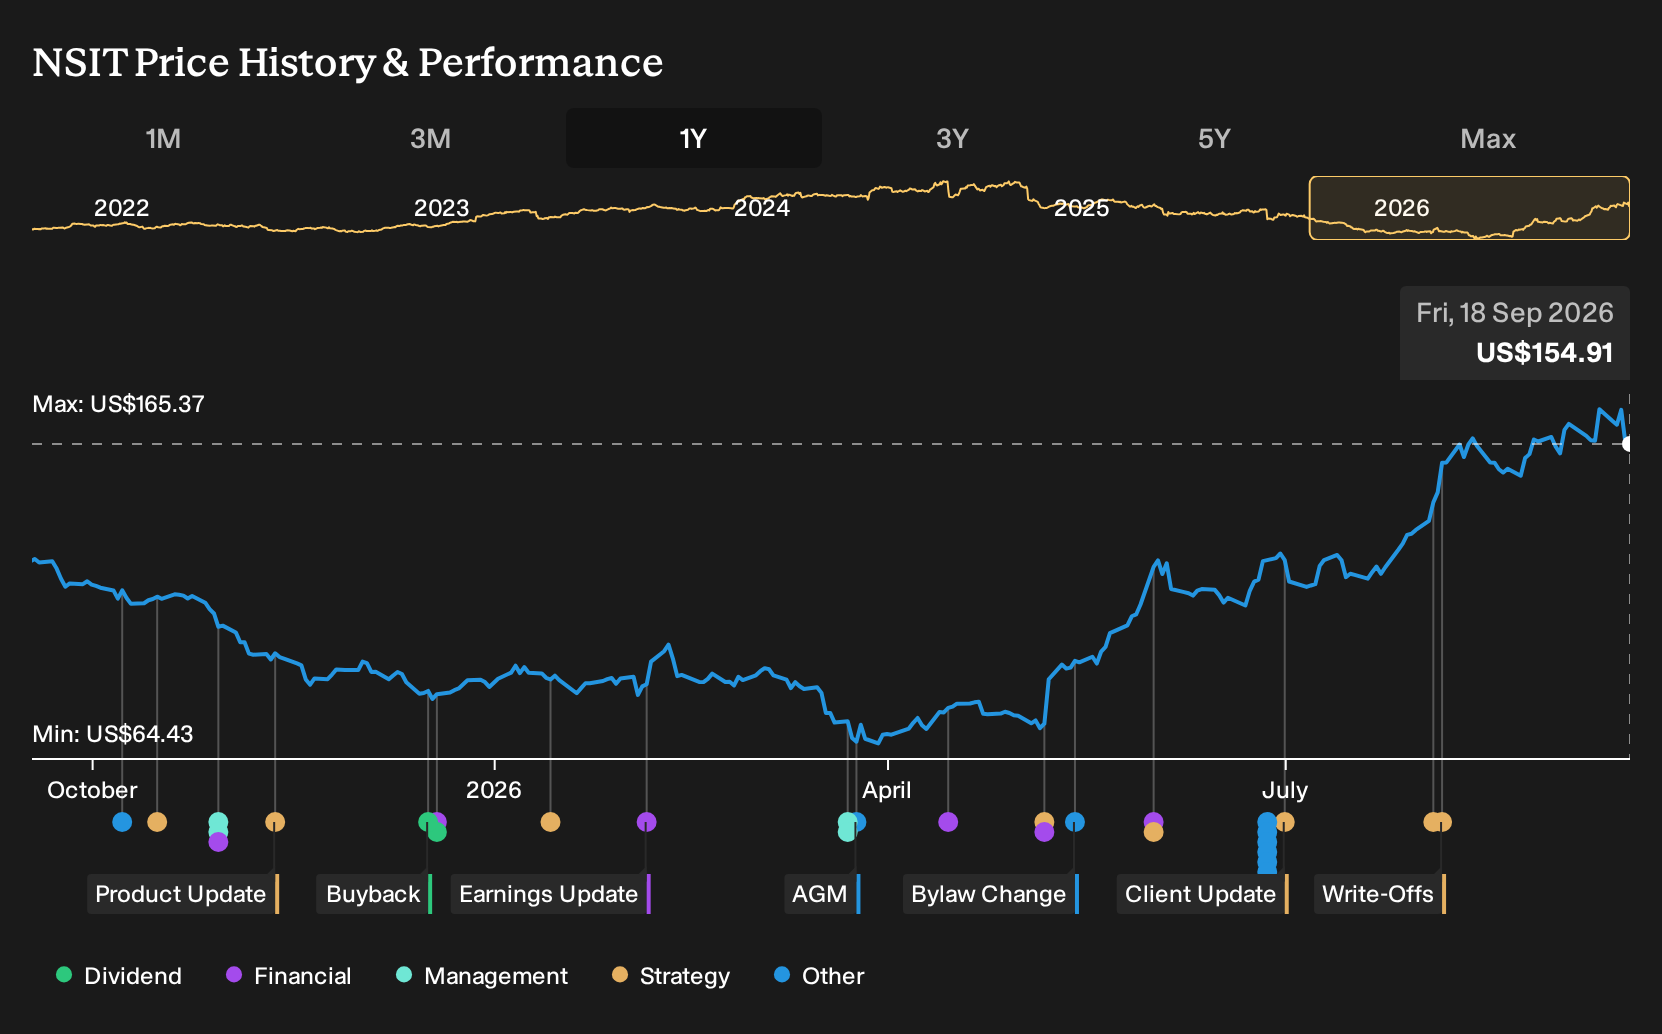
Exploring Other Perspectives
Some of the most optimistic analysts focus on a different catalyst for Insight Enterprises. They lean heavily on the device and infrastructure refresh cycle, with prior forecasts pointing to US$9.4b of revenue and US$352.1m of earnings by 2029. That is a more upbeat story. Use this news to test which storyline you find more convincing, since both views were formed before it happened.
Explore 4 other Insight Enterprises fair value estimates, including one that suggests as much as 14% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Insight Enterprises research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Insight Enterprises. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Insight Enterprises' overall financial health at a glance.
Looking For More Investment Ideas Beyond Insight Enterprises?
If the Insight Enterprises story has sharpened your thinking, use that momentum to scan a wider field of opportunities that fit your own risk profile and return goals. The Simply Wall St Screener lets you filter for financial strength, valuation, income potential, and more so you can build a watchlist that actually reflects how you like to invest.
- For investors who want potential growth without ignoring downside risk altogether, start by reviewing 30 resilient stocks with low risk scores that may offer a steadier ride.
- If income is a priority, consider the high-yield opportunities surfaced in 7 dividend fortresses that focus on businesses paying 5% or more.
- For those hunting for lesser-known opportunities with solid fundamentals, widen your search through 16 high quality undiscovered gems that might not yet be widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com