
Houlihan Lokey (HLI) Opens West Palm Beach Office, Is The Stock A Bargain?
Houlihan Lokey (HLI) has just widened its footprint in South Florida with a new West Palm Beach office, while also adding senior leaders in New York and São Paulo to deepen its capital advisory reach.
The new West Palm Beach base and senior hires land at a time when Houlihan Lokey’s 1-year total shareholder return is down 36.36% and the year-to-date share price return has fallen 25.97%, even though the 5-year total shareholder return of 49.93% still points to a much stronger longer run.
Spot similar financial advisory players that may be setting up their next leg of growth with our hand picked 16 high quality undiscovered gems as Houlihan Lokey pushes into West Palm Beach and Latin America.Houlihan Lokey is expanding into West Palm Beach just as the share price has retreated sharply. Do those new offices and senior hires tip the risk reward in favour of buyers at today’s valuation, or not?
Most Popular Narrative: 16% Undervalued
The most followed narrative currently places Houlihan Lokey's fair value at $154.50, compared with a last close of $130.55. This frames the recent share price slide against a higher long run valuation anchor based on modeled cash flows and margins.
Expansion of business lines (notably Capital Solutions and secondaries) and continued emphasis on senior talent recruitment are enhancing sector and product breadth, positioning the firm to capture incremental market share and drive incremental revenue growth. Investment in strategic client engagement (such as large-scale flagship conferences) and enhanced digital capabilities are expected to reinforce client relationships and operational efficiency, supporting both revenue growth through deeper client penetration and stabilization or improvement of net margins.
See why 7 investors see Houlihan Lokey as 16% undervalued.
Result: Fair Value of $154.50 (UNDERVALUED)
Still, if U.S. deal activity stays muted or if high compensation costs squeeze margins, the Houlihan Lokey upside story could lose momentum quickly.
Find out about the key risks to this Houlihan Lokey narrative.
Another View On Houlihan Lokey’s Valuation
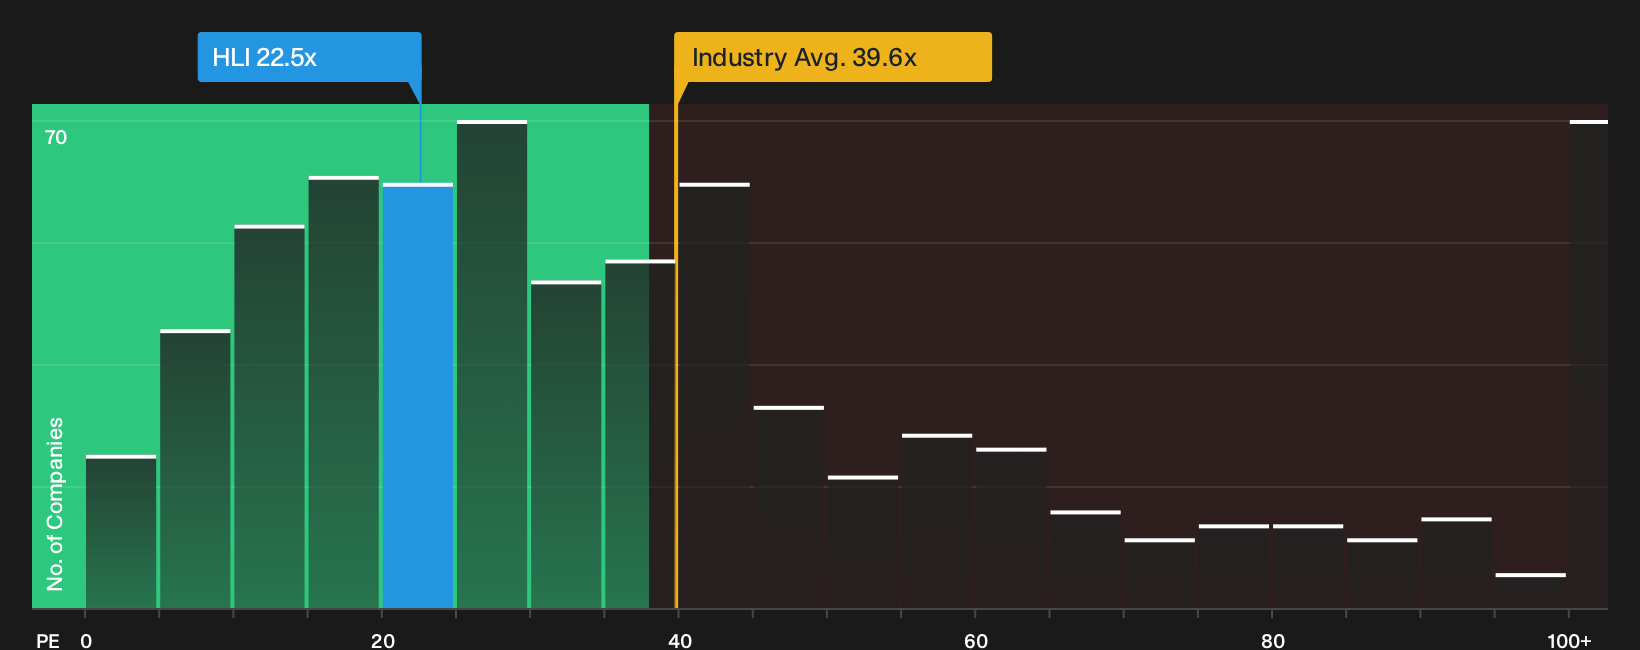
On a simple earnings ratio, Houlihan Lokey looks less clear cut. The stock trades on a P/E of 22.5x, which is almost double similar peers at 11.5x, yet still below the broader US Capital Markets group at 39.6x. Our fair ratio estimate sits lower at 14.6x, which points to meaningful re rating risk if sentiment cools.
Investors weighing that gap against the SWS DCF output can use it as a sense check rather than a verdict. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Houlihan Lokey's valuation make this a stock readers may want to judge on the hard numbers themselves rather than headlines. If you want to move quickly from the headline story to specific upside drivers, start by reviewing the 3 key rewards.
Looking for more Houlihan Lokey sized ideas?
If Houlihan Lokey has sharpened your focus on valuation and quality, do not stop here. Use the Simply Wall Street screener to quickly surface fresh ideas.
- Target resilient balance sheets and disciplined fundamentals by scanning the list of solid balance sheet and fundamentals (23 results) that meet strict financial strength filters.
- Hunt for mispriced opportunities by reviewing the 35 high quality undervalued stocks that combine quality metrics with attractive valuation signals.
- Prioritize income plus staying power by checking the 30 resilient stocks with low risk scores designed for investors who want steadier return profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com