
Grindr (GRND) Could Be 26% Undervalued As Premium Growth Story Builds
Grindr (GRND) continues to trade around recent levels, with the share price last closing at $15.40. Recent returns have been mixed, which keeps attention on how the business is actually performing.
Recent moves have been fairly muted. However, Grindr’s 90-day share price return of 17.11% and year-to-date share price gain of 15.70% contrast with a 1-year total shareholder return that is still down 3.69%, hinting at improving momentum after a softer patch.
Scan how Grindr’s momentum compares with other app based platforms by reviewing the hand picked 16 high quality undiscovered gems that share strong fundamentals but still fly under most investors’ radar.
For Grindr, a 90 day rebound alongside a slightly weaker 1 year picture puts the focus squarely on price. Do current levels still offer a compelling risk reward profile for new buyers?
Most Popular Narrative: 26% Undervalued
Analysts who follow Grindr closely see a fair value of $20.80 per share, compared with the recent close at $15.40, and tie that gap directly to expectations for growth and profitability over the next few years.
Ongoing shift toward value-added premium tiers, coupled with planned pricing experiments and the introduction of more differentiated features (such as mapping, intentions-based products, A-List), positions Grindr to lift ARPU and improve net margins over time. Investments in proprietary AI infrastructure (gAI) and enhanced in-app experiences (such as mapping and local discovery) provide differentiation and are expected to affect user engagement and retention, thereby supporting recurring revenues and long-term earnings growth.
See why 8 investors see Grindr as 26% undervalued.
Result: Fair Value of $20.80 (UNDERVALUED)
Still, the Grindr narrative relies on continued user monetization and disciplined spending, so any slowdown in revenue growth or sustained cost pressure could quickly test this valuation story.
Find out about the key risks to this Grindr narrative.
Another Take On Grindr’s Valuation
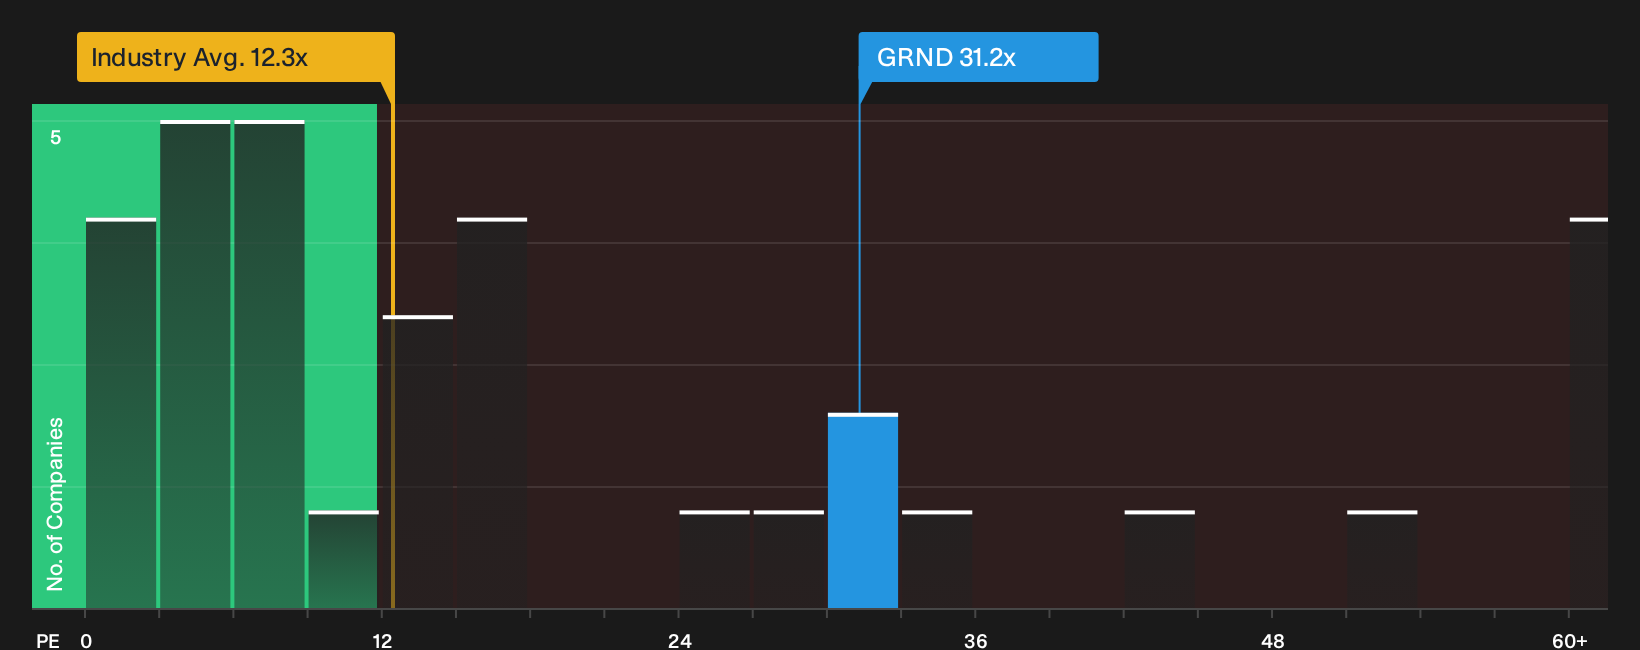
The first story on Grindr leans heavily on analyst targets and narrative forecasts. A different lens comes from its current P/E of 31.2x versus a fair ratio of 22.2x, with the US Interactive Media and Services group and peer set closer to 12x. That gap points to richer pricing on today’s earnings, even with growth expectations. How comfortable are you paying a premium now for a thesis that plays out later?
To see how those earnings multiples stack up against underlying fundamentals in more detail, review the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views on Grindr’s pricing and outlook are clear. Use that tension as a prompt to move quickly, compare the data, and test your own thesis against the 4 key rewards and 3 important warning signs
Looking for more investment ideas beyond Grindr?
If Grindr has your attention, do not stop there. Use a few focused screens to uncover other opportunities that fit your style before they move without you.
- Target reliable income streams by scanning companies that appear as 7 dividend fortresses and could help anchor the more volatile parts of your portfolio.
- Spot quality at a discount by reviewing the 35 high quality undervalued stocks, then see which businesses match your expectations on balance sheet strength and earnings resilience.
- Reduce sleepless nights by focusing on the 30 resilient stocks with low risk scores, where steadier profiles may balance out higher risk growth positions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com