
Rocket Companies (RKT) After Seller Concessions Hit A New High, Is Fair Value In Sight?
Rocket Companies (RKT) is back in focus after new data showed home seller concessions reached 44.7% of U.S. sales in August, the highest August share since at least 2020.
Against that backdrop, Rocket Companies has seen its share price slide, with the stock down 11.77% over the past 30 days and 38.18% year to date. The 1 year total shareholder return has declined 40.08%, but the 3 year total shareholder return remains positive at 54.61%, suggesting shorter term momentum has faded compared with its longer run performance.
Scan how Rocket Companies fits alongside other housing related plays by reviewing our hand picked list of solid balance sheet and fundamentals (23 results) that may handle a softer mortgage cycle with more resilience.
Rocket Companies now trades meaningfully below both analyst targets and an estimated intrinsic value, even after recent gains in revenue and net income. Is that discount caution well placed, or has sentiment swung too far?
Most Popular Narrative: 31% Undervalued
On the most followed view of Rocket Companies, a fair value of $17.70 sits above the last close at $12.29. This raises a clear question about whether current pricing fully reflects its business model and housing exposure.
The market may be ascribing premium value to Rocket's data ecosystem and cross-sell capabilities from the expanded "FinTech ecosystem," but this could prove overly optimistic if younger demographic cohorts delay home-buying due to persistent affordability problems, thus dampening anticipated growth in customer lifetime value and overall revenues.
See why 35 investors see Rocket Companies as 31% undervalued.
Result: Fair Value of $17.70 (UNDERVALUED)
Still, the picture for Rocket Companies could change fast if housing affordability worsens further or fintech rivals force heavier spending to protect margins and market share.
Find out about the key risks to this Rocket Companies narrative.
Another View On Rocket Companies Valuation
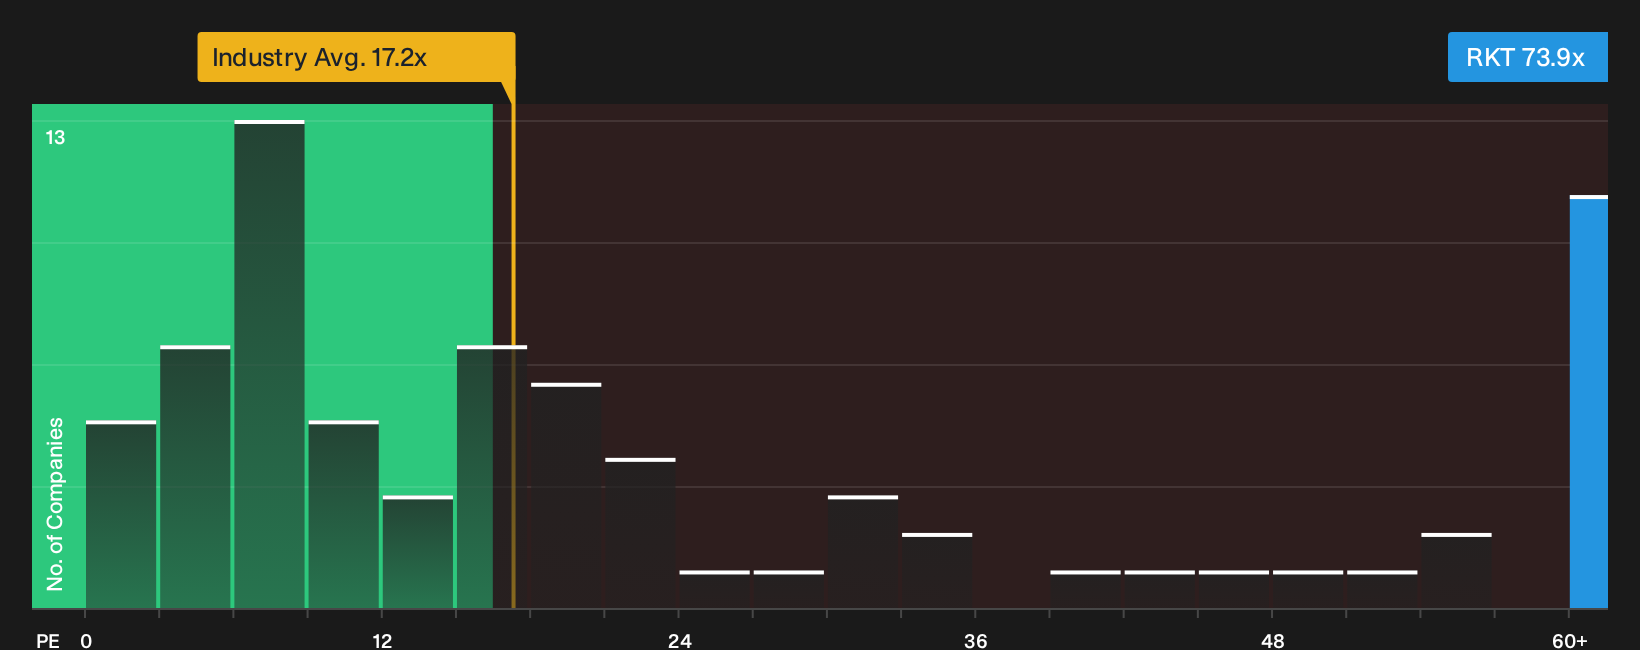
The story looks different when you step away from fair value estimates and focus on simple earnings multiples. Rocket Companies trades on a P/E of 73.9x, while the US Diversified Financial industry averages 17.2x and peers sit near 39.6x. The fair ratio sits at 31.3x, which suggests investors today are paying a rich premium for each dollar of current earnings. That kind of gap can reward you if growth plays out, but it also raises the risk that any disappointment on future results hits the share price hard. How comfortable are you with paying more than double the fair ratio for this level of profit?
For a closer look at how that earnings multiple compares with the wider market and where it might leave room for repricing over time, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Rocket Companies valuation and sentiment can be confusing, so move quickly and test the data yourself by starting with the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Rocket Companies?
Do not stop with Rocket Companies. Broaden your watchlist now, compare different risk and reward profiles, and give yourself more ways to put cash to work intelligently.
- Target potential upside by scanning 16 high quality undiscovered gems to find companies that combine strong fundamentals with less crowded attention from the broader market.
- Protect your downside first by exploring 30 resilient stocks with low risk scores that aim to keep balance sheets and risk scores front and center.
- Seek value opportunities by reviewing 35 high quality undervalued stocks that pair quality traits with prices the market has not fully rewarded yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com